This Italian startup makes $1.5B a year reviving zombie apps
Italian startup Bending Spoons buys struggling apps like Evernote and Meetup, then fixes them with custom tools and elite talent. They've turned this into a $1.5 billion annual business by acquiring cheap zombie apps, diagnosing four core problems, and applying proprietary fixes that most founders miss.
Chapters
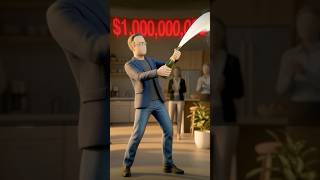
On the fifth floor, a man with glasses pops champagne. His company is now worth $1 billion. Phones around the room light up. Messages stream in from investors. Congrats on building a rocket ship. Ten years later, the same man is working from home. Scrolling Reddit it's so slow, it's unusable. There's so many bugs. I wish I switched to notion earlier. He opens another tab to check financials, but Evernote hasn't made a profit for years. He starts writing his resignation. Then an email hits his screen. It's marked urgent. An acquisition offer from a company based in Milan. No one on his team has heard of them, but the number is 50% higher than any other offer they've gotten. He accepts. The takeover begins immediately. An Italian man fires most of the team. By noon, a new crew arrives. Europeans, fresh out of college. Within two years, Evernote is profitable again. But this isn't the work of private equity. It isn't a buy and flip, and it isn't a one off. It's been done 20 times in 10 years, all by one company, across apps. Just like Evernote. Dying but not dead. This is how Bending Spoons revives zombie apps at scale. By building a startup repair factory that's been profitable since day one.
I remember we were making half a million a year. Now we're making a billion.
But first, you quickly need to know why they don't start from scratch. Because it unlocks the company's entire playbook. For Luca Ferrari and his co founders, the insight came after their first startup failed in 2013. They raised a million dollars, went to market, and flopped. Here's what he said about it on a podcast.
We crashed and burned by being arrogant in thinking we knew what the market would want.
So they took the money that was left and founded bending spoons in 2013. Only this time, they didn't build. They bought a broken keyboard app for roughly 10,000 dol, made it better and turned a profit, used that money to buy a second app and bring it back to life, then did it over and over again.
We let others seek product, market, fit, and then we acquire their company and try to make it even better.
This strategy powers the repair Factory, and in 2025, it was valued at $11 billion. So how did they go from fixing one zombie app to reviving 20 of them? What you're about to see is Bending Spoon's playbook. First, let's start with a surprising fact about the business model.
You know what? We have never lost a bid before.
How is this possible? It's because they see a different future than everyone else. Other buyers model an exit in three to seven years. Bending Spoons models Lifetime ownership we acquired to hold forever.
We never sell.
Luka calls this 25% private equity 75% tech company going deep on changes to product engineering and design. Decades of compounding improvements.
I think we're a hybrid. It's almost like a private equity had a baby with Google.
This is why they sometimes pay double the next offer. So how do they know what to buy? Acquisitions are guided by three signals. One Software people already love Evernote is my secret weapon with a strong brand and loyal user base. 2 Management is stuck and either can't or won't revamp the company and three a clear path to profitability based on changes they would make.
We buy businesses where almost all the value lies in existing customers or users.
In other words, they execute better on what already works. The next question is how do they do that? Well, once they acquire a company, it goes on the operating table. Bending Spoons sends in a strike team like an emergency medical unit. They examine the patient for four organization sprawl, inefficient costs, gross margin leaks and under monetization. The diagnosis is similar across acquisitions, but the treatment is almost always custom.
It could be rewrite the software, rearchitect the cloud infrastructure, launch lots of features, redesign the ui, optimize monetization and marketing, rebuild big chunks, sometimes the entirety of the organization.
Here's three examples. At Rimini, they rewrote every line of code and added features. At meetup, they fixed 400 bugs and cut bloat. At Wetransfer, they reworked pricing and limited free usage. Two things are consistent though. They improved the product for paying users, then raised prices on the core offering.
We've really focused on what these customers painfully needed.
The result? Retention always goes up. But that still doesn't explain how they make decisions at scale or move so fast. What's interesting is Bending Spoons doesn't build consumer products from scratch, but they do build tools for reviving Zombies.
More than 50 proprietary technologies, some of which could easily be sold as a B2B business, maybe worth hundreds of millions.
Not all of them are public knowledge, but here's what I found in my research. Before they acquire Lumen converts raw data into clean insights and crystal finds targets. And after they acquire three tools power the transformation. Pico answers Will users pay for this? Minerva automates the big decisions what to build, what to cut, and what to charge. And Pantheon gives every app access to the same AI infrastructure Strike teams simply plug newly acquired companies into this platform. Within days, they know exactly what's broken and how to fix it. Once it's profitable, the strike team moves on and the tools travel with them.
It's so easy to allocate people to where they can create the biggest impact. That makes a ton of difference.
The thing is, is though tools don't revive zombie apps on their own. Elite operators do. Talent mobility is important, but talent density is the key to the entire repair factory.
We think about the jobs we offer as our most important product.
In 2025, 800,000 people applied. They hired 250. That's a 0.03% acceptance rate, which is tougher to get into than Harvard. Here's how they find operators worth Custom AI screens applications for potential. It also filters out people it thinks won't handle the intense culture. Next, candidates face assessments they call harder than Google, Amazon or Meta. It's testing three talent, motivation and problem solving skills. New hires start in Milan and get a document called Controversial Principles. Then they spend three months soaking up the culture before joining a strike team.
You learn faster than anywhere else. Most of our general managers who run businesses on average 50, $100 million in revenue.
The compensation makes it worth their while. Bending Spoons has been described as a little Goldman Sachs in Italy, paying London and New York salaries in Europe. But what's interesting is there's no bonuses or equity grants.
Those kind of incentives tend to hinder relationships. They tend to make things more transactional. It's more difficult to have a proper problem solving session where all we're thinking about is how do we win together.
So how do they keep their elite operators? Raises are tied to impact only. There's also a unique system for employees to build meaningful stakes.
Anyone can convert a portion of their compensation up to a certain limit to stock options at a stage.
The result of this whole thing is pretty impressive 1% annual turnover. Most companies lose 10 to 20% of their people every year. With a team of just 700, that's bending spoon's real moat. Talent density without churn. But none of this works without funding. Which brings me to the final page in Bending Spoon's unusual playbook. They didn't raise venture capital until they were nearly 10 years in.
We really wanted to build this with a multi decade view and we felt that it was quite dangerous to relinquish control so early.
They bootstrapped for five years, reinvesting profits from each acquisition into the next. When they were ready to go after bigger deals, they took out loans. Remember, they've been profitable since day one, and banks trusted their cash flows. By the time they raised their first equity round, Bending spoons was making $100 million in annual revenue. And investors aren't limited to VCs. There's a bunch of celebrities who have also bought in, including the Weeknd, Ryan Reynolds and Andre Agassi. Most startups raise equity early, take on zero debt, and hope they grow fast enough before the money runs out. Bending Spoons flips that model. Today they've raised roughly 3 billion in debt for acquisitions and 700 million in equity for operations, all without giving away.
Much control and reinvest in making our platform more powerful. So build better proprietary technologies, better access to talent, and go after new, bigger acquisitions.
That's how Bending Spoons revives zombie apps at scale and according to analysts, it's a strong match for current markets. There's a growing number of dead unicorns and companies trading below their IPO. Insight insiders say bending spoons has 5,000 companies on their acquisition list. This stacks up 2025 was their biggest year yet, over 3 billion invested in Vimeo, AOL and Eventbrite alone. The deals are getting bigger, but the thesis is still.
More from Hiten
The Library of Minds: "The Social Network Ruined Startups" | Hiten Shah 4x SaaS Founder
This startup repair factory is worth over $11 billion #entrepreneur #founder #productmanagement
This is how a $40 billion crypto cult came crashing down #crypto #terraluna #stablecoin #dokwon
This is the only casino the government can’t shut down #gambling #tech #startup #founder