Leases and Loans Feeling the COVID-19 Pain
In this Continuing Legal Education (CLE) webinar, attorney Phil Wong provides a comprehensive update on how the COVID‑19 pandemic is affecting commercial real estate leases and loan financing. He begins with a survey of federal, California, and Bay Area shelter‑in‑place orders, distinguishing essential from non‑essential businesses and highlighting the scale of the stay‑at‑home directives. He then explains the two California executive orders (N‑2820 and the statewide residential eviction moratorium) that temporarily halt evictions for both residential and commercial tenants while preserving rent obligations. The discussion moves to loan relief, covering voluntary mortgage forbearance programs offered by banks, specific residential loan forbearance terms (up to 90 days, fee waivers, no credit reporting), and multifamily loan forbearance options under FHFA guidance and the CARES Act (30‑day increments, eviction bans, and payment extensions). Wong analyzes contractual defenses to performance, detailing the four‑factor test for force‑majeure clauses, the impact of pandemic‑related government orders, and the common‑law doctrines of impossibility, impracticability, and frustration of purpose, with illustrative case examples. He outlines recent bankruptcy law changes in the CARES Act, notably the expansion of the Small Business Reorganization Act’s Subchapter 5 debt limit from $2.7 million to $7.5 million, and other adjustments to Chapter 7 and Chapter 13. Practical considerations follow, including the limited applicability of business‑interruption insurance, property‑tax penalty relief options, and tax filing/payment extensions. The session concludes with audience questions on the enforceability of personal guarantees in bankruptcy and the public‑policy limits on waiving impossibility‑type defenses. Wong emphasizes ongoing monitoring of legal developments and offers follow‑up support.
Chapters
So welcome to Ramone's Continuing Legal Education Series. This webinar is entitled Leases and Loans: Feeling the COVID-19 Pain. My name is Phil Wong, and I'm a partner with Ramone. I have a law practice in the areas of commercial litigation, real estate, and bankruptcy. I used to work out of Ramone's San Francisco and Silicon Valley offices. And now I am working from home, or more accurately, as I have heard others say, I am at home during a crisis trying to work. I think that's an important distinction. For this webinar, we're going to cover an update on COVID-19 restrictions from federal, California, and San Francisco Bay Area perspectives, its effect on leases, its effect on loans. We're going to touch on the CARES Act, which is the Coronavirus Aid, Relief, and Economic Security Act, as it pertains to possible bankruptcies and other related practical issues. Please feel free to raise questions in the chat area, and we'll do our best to monitor that during the webinar. We'll also reserve about 10 minutes at the end for questions and comments from the group. I am also always available for any follow-up questions via email or telephone. So let's get started. We'll start with an update on COVID-19 restrictions. First, in California, on March 4th, the governor proclaimed a state of emergency to exist in California as a result of the threat of COVID-19. And he ordered all individuals living in California to stay at home, except as needed to maintain the continuity of operations of the federal critical infrastructure sectors that we now know as essential businesses. Most of you may already know that California was the first state among many to direct people to stay at home. And at present, there are about 283 million people in at least 35 states, 79 counties, 28 cities, the District of Columbia, and Puerto Rico that are being directed to stay at home. That was, that was a shocker for me in terms of statistics. So let's let that last statement sink in. 283 million people are being directed to stay at home right now. This crisis is already affecting over 85% of our country since January 21st, when the first case was confirmed in the U.S. There are 16 critical infrastructure sectors whose assets, systems, and networks, whether physical or virtual, are considered so vital to the United States that their incapacitation or destruction would have a debilitating effect on security, national economic security, national public health or safety, or any combination. And the President has identified 16 critical infrastructure sectors. They're listed here. Let's take a few seconds to allow you to review the 16 critical infrastructure sectors. And while you're looking at them, maybe think about how many of your businesses are not in these critical sectors. How many of your clients' businesses are not in these critical sectors? How many of your tenants? Maybe how many of your borrowers? Essential businesses. Over 35 states have now imposed restrictions on which businesses can stay open during the COVID-19 outbreak. The exact definition of essential varies by location because it is up to the local jurisdictions to decide, but there are some businesses that almost all locales have deemed essential. They include the following. Those, uh, 16 critical infrastructure sectors that we just saw on the last slide are basically broken down into essential business categories. Again, let's take a few seconds to review these categories and think about how many of your businesses are essential businesses. And how about your clients' businesses, the businesses of your tenants, the businesses of your borrowers? Now on to non-essential businesses. These are businesses that are generally recreational in nature. They do not provide groceries, health or financial support, or utilities. Restaurants fall in this category, but most locations have allowed restaurants to continue to operate as long as they close dining rooms and switch to exclusively takeout and delivery. These are the businesses largely agreed to be nonessential. So when I look at this list, I question how these non-essential businesses are going to survive. Can some of them still sell their goods or services online or remotely or via delivery? Are there entire businesses completely shut down? I believe the answer to that is that many of these non-essential businesses are entirely shuttered. And then these are businesses for which the category varies by region, whether they're essential or nonessential, or whether portions of these businesses may be essential. Many nonessential businesses have been forced either to shut down entirely or to severely curtail their business activities. Such businesses generally have limited ability, if any, to pay payroll and other expenses such as rent. For most businesses, payroll and rent are the two major expenses each month plus debt service. How much cash or liquidity is held by these businesses? In general, I suspect not a relatively large amount, given that the coronavirus crisis started really without much warning. Now let's look at the San Francisco Bay Area update with regard to COVID-19 restrictions. The current shelter-in-place order for the Bay Area was recently extended, and with it comes new regulations for the restaurants and grocery stores still in operation during the pandemic. The counties of Alameda, Contra Costa, Marin, San Francisco, San Mateo, and Santa Clara, as well as the City of Berkeley, have extended their shelter-in-place orders from April 7th to May 3rd. Grocery stores and restaurants must prepare, implement, and post a social distancing protocol that includes measures to protect employee health, to prevent crowds from gathering, to keep people at least 6 feet apart, to prevent unnecessary contact, and to increase sanitization. The San Francisco Bay Area implemented these orders to shelter in place early, all in an effort to flatten the curve and help our healthcare systems and workers avoid a peak in patients needing hospitalization. I understand from recent reports that there may be some preliminary indications that those efforts are paying off, but the next few weeks, particularly probably the next 2 weeks, will still be critical to see how effective we have been at flattening the curve. The order also expanded the types of essential businesses that are allowed to remain open. And they now include service providers that support residential property transactions, like notaries, title companies, and realtors. Also included are funeral homes and cemeteries, with funerals being limited to 10 attendees. Moving companies, rental car companies, and ride-hailing services that enable essential activities are also allowed to to remain operational. And all of these businesses are required to pare down their operations to the bare minimum. From the real estate perspective, it's helpful to see that home sales are deemed part of essential businesses. However, given the incredible rise in unemployment, the high volatility in the stock market, and the uncertainty of the duration of this crisis and our response. It seems to me that the volume of home sales will slow tremendously as buyers exit the market, at least for the time being. It's also incredibly sad to see funeral homes and cemeteries added as essential businesses. The order also provided more restrictions on the use of certain public spaces and activities. All playgrounds, dog parks, public picnic areas, and similar recreational areas have now been closed to the public. The use of shared public recreational facilities like golf courses, tennis courts, basketball courts, pools, rock walls is prohibited, and those facilities must also close. Sports requiring people to share a ball or other equipment is prohibited unless it solely involves people in the same household. And most construction, both residential and commercial, that is not related to critical infrastructure sectors is prohibited. These restrictions make sense to me as part of our social distancing objective. But I get the sense that a large portion of construction activity in the area is not related to essential businesses, so this will be another sector of the real estate industry that may suffer substantially. Next, we will turn our attention to the effect on leases. In California, Governor Newsom has issued two executive orders with regard to evictions. The first is Executive Order N-2820. This executive order authorizes local governments to impose a moratorium on evictions due to the COVID-19 pandemic. It applies to both residential and commercial properties. Many local governments have already moved forward and adopted local ordinances, including San Francisco, Los Angeles, Sacramento, I believe San Diego, and many others. This executive order does not waive the rent obligation of tenants, but allows local governments to defer action until May 31st. An important point to note here is that commercial tenants are included in this eviction moratorium. Here's some of the specific text of this executive order. Local governments may exercise its police power to impose substantive limitations on residential or commercial evictions and shall only apply when the basis for the eviction is nonpayment of rent or foreclosure arising out of a substantial decrease in household or business income or a substantial out-of-pocket medical expense. The decrease in household or business income or the out-of-pocket medical expenses was caused by the COVID-19 pandemic or by any local, state, or federal government response to COVID-19 and is documented. The order also says that nothing shall relieve a tenant of the obligation to pay rent nor restrict a landlord's ability to recover rent, and that these protections shall be in effect through May 31st unless extended. Note here that tenants still owe rent and that landlords can still recover rent, but that tenants can remain in possession of the premises. So evictions are what are being curtailed for the time being. The second executive order is a statewide residential eviction order, and it pertains to residential tenants who previously paid rent when due provided landlords with written notice of the need to delay payment of rent due to reasons related to COVID-19 and can document the changed financial circumstances. This is different than the first executive order in that it is a statewide protection and no local adoption is required. This executive order will also be in effect through May 21st— May 31st, sorry. And again, nothing in this order shall prevent a tenant who is able to pay all or some of the rent due from paying that rent in a timely manner or relieve a tenant of liability for unpaid rent. So again, note that tenants are still liable for unpaid rent but can remain in possession of the premises for the duration of these orders. We'll move next to discuss the effects on loans. On March 25th, the Department of Business Oversight secured support from national banks, state banks, and credit unions for temporary delays in mortgage payments and foreclosure sales and evictions for homeowners who have economic impact from COVID-19. This relief is not mandated by the government. So let's note here that banks are voluntarily supporting payment and foreclosure forbearances. There is no government directive to do so as of yet. Let's next talk about relief for residential loans in California. Those who are struggling with COVID— with the COVID-19 crisis may be eligible for the following relief after contacting their financial institution. A list of participating financial institutions can be found at that website, but they pretty much include all the major banks that you can think of. If you are impacted by COVID-19, these financial institutions will offer mortgage payment forbearances of up to 90 days. For at least 90 days, financial institutions will waive or refund mortgage-related late fees and other fees, including early CD withdrawals. Financial institutions will not start any foreclosure sales or evictions for 60 days. And if you are taking advantage of this COVID-19-related relief, Late or missed payments will not be shared with credit reporting agencies and will not affect your credit score. To me, this seems like very reasonable relief for every homeowner to pursue. I understand the response time to a forbearance request varies by lender and could include waiting on the telephone for hours to speak to someone. One point that I recommend to all borrowers is to confirm when the missed payments will be due. Of course, a preference is to add them to the end of the loan by extending the term, but I hear that some banks are asking borrowers to catch up on all payments after the forbearance period, which seems unrealistic to me. Now let's talk a little bit about relief for multifamily loans. On March 23rd, to support multifamily property owners during the COVID-19 national emergency, the Federal Housing Finance Agency announced that Fannie Mae and Freddie Mac will offer multifamily property owners mortgage forbearance with the condition that they suspend all evictions for renters unable to pay rent due to the impact of COVID-19. The eviction suspensions must remain in place for the entire duration of time that a property owner remains in forbearance. The forbearance is available to all multifamily properties with an enterprise-backed performing multifamily mortgage negatively affected by the COVID-19 national emergency. Multifamily properties seem to be the only commercial product type to have the current attention of the government during this crisis for obvious reasons. Again, I would recommend to owners of multifamily properties to pursue this relief, but also to confirm when the missed payments will be due. The payments should be added to the end of the loan by extending the term, in my view, and not become due when the forbearance period expires. Buyers. There is also some relief for multifamily loans in the CARES Act, which is the Coronavirus Aid, Relief, and Economic Security Act that was just recently passed by the federal government. The CARES Act contains several provisions that assist borrowers of federally-backed multifamily mortgage loans who are experiencing financial hardship because of COVID-19. Here are some of the key provisions. Borrowers of federally-backed mortgages with multifamily properties may request a forbearance from loan servicers if they are current on their payments as of February 1st and affirm they are experiencing financial hardship due to the COVID-19 emergency. The CARES Act provides that upon receipt of a request meeting the above requirements, a servicer will grant a forbearance of up to 30 days. The forbearance can be extended for up to 2 additional 30-day periods, provided the extension request is made during the covered period and at least 15 days before the current forbearance period would expire. Once again, I think it is important to understand the terms of the CARES Act's forbearance. In particular, when and how will borrowers be obligated to pay the missed payments? Hopefully the term of the loan will be extended by the same amount of time as the forbearance, and missed payments will not be all due at the end of the forbearance period. Also, under CARES, it sure seems like you need to be requesting the forbearance, and as soon as you get the forbearance, you need to request it again because you cannot obtain a 90-day forbearance under the CARES Act. Um, instead, they need to be made in 30-day increments, and you also need to apply 15 days before the current forbearance period would expire. A multifamily borrower receiving a forbearance under the CARES Act has restrictions imposed on it, including that it may not, for the duration of the forbearance, evict or initiate the eviction of a tenant solely for nonpayment of rent or other charges. Impose any fees, penalties, or other charges to a tenant for late payment of rent, and may not issue a notice to vacate until after the expiration of the forbearance. The forbearance period can be terminated at any time upon the request of the borrower. These conditions for a forbearance under the CARES Act mirror the conditions for homeowners under the bank's voluntary relief programs. We should also note that the CARES Act defines a federally-backed multifamily mortgage loan as any loan other than temporary financing, such as a construction loan, that is secured by a first or subordinate lien on residential multifamily real property designed for occupancy of 5 or more families that is made, insured, guaranteed, or assisted in any way by any officer or agency of the federal government. The CARES Act defines covered period as a period commencing on March 27th and ending on the first to occur of the termination of the national emergency concerning the COVID-19 outbreak. And December 31st. So multifamily under this program is a 5-plex or more. Those multifamily property owners should pursue this relief. I can imagine many residential tenants in apartments having difficulty paying their rent for multiple reasons: job loss, layoffs, medical expenses, etc., etc. Also, Note that there is potential relief regardless of the priority of the loan. Relief for other commercial property loans. The bad news is that there appears to be no current program for any government relief for other commercial property loans. The CARES Act, though, is very likely not the last government stimulus legislation, so definitely stay tuned. In the meantime, borrowers and lenders may need to resort to contract law to determine how COVID-19 affects their rights and obligations. I understand the lender community has been engaging in significant lobbying efforts with the federal government for relief. Which may ultimately allow commercial property owners some form of mortgage relief or forbearance. We'll move next to discuss defenses to performance, and we'll start with force majeure clauses. They are contract provisions that relieve the parties from performing their contractual obligations when certain circumstances beyond their control arise, making performance inadvisable, commercially impracticable, illegal, or impossible. In the U.S., the analysis of whether a force majeure clause may be employed to excuse performance is based on the facts of a specific case and the language of the applicable force majeure clause in question. When U.S. courts analyze a force majeure clause to determine if it applies to a certain instance of non-performance, there are 4 key factors: the precise language in the force majeure clause, evidence that the force majeure event was unforeseeable, proof of causation between the force majeure event and the resultant non-performance, and evidence that the effects of the force majeure event are so severe that contract obligations cannot be performed. The court's inquiry largely focuses on whether the event giving rise to non-performance is specifically listed as a qualifying force majeure in the clause at issue. Even if a party can surmount this requirement, it cannot invoke force majeure if it could have foreseen and mitigated the potential nonperformance, and performance is merely impracticable or economically difficult rather than truly impossible, unless the specific jurisdiction or contract at issue specifies a different standard. Recent and continuing COVID-19 developments may impact whether the outbreak and/or its effects constitute force majeure. I think the main takeaway here is that the specific language of your force majeure clause matters. So I would suggest that you review the language carefully and see if this pandemic arguably qualifies. COVID-19's classification as a pandemic by the World Health Organization will trigger a force majeure clause that expressly accounts for pandemics. Having said that, the declaration of pandemic by itself, without reference to pandemics in a force majeure clause, will not automatically constitute a force majeure, given the court's focus on whether the event is specified within the contractual language. Clauses that are silent on pandemics, epidemics, or other viral outbreaks are likely to be insufficient for a force majeure defense due to COVID-19 unless courts liberalize the force majeure analysis to account for current realities. If a force majeure clause specifically covers COVID-19 as a qualifying event, In light of the World Health Organization's declaration, parties seeking to invoke the provision will not need to establish the event was unforeseeable, but will still need to show that they took steps to mitigate the damage and that performance is truly impossible or meets any other standard the clause requires. With this pandemic, we are in uncharted waters as to how courts will apply force majeure clauses to the current crisis. Please stay informed as to current developments, developments on the pandemic and in particular our response. In the meantime, I recommend documenting any efforts you can do to mitigate your damages. Recent government regulations intended to contain the COVID-19 outbreak may similarly make it easier to invoke a force majeure clause not previously triggered by the virus. Ever-expanding government restrictions on travel, movement, sheltering in place, and large gatherings have resulted in significant business interruptions and widespread event and travel cancellations, with a particularly salient impact on the event tourism, restaurant, airline, venue rental, and sports and entertainment sectors. Businesses may be able to invoke force majeure provisions to excuse any contractual non-performance resulting from these measures if the clauses at issue enumerate government orders or regulations that make performance impossible. Definitely keep an eye on this area of the law as this crisis may allow the law to evolve on this issue. As with clauses triggered by the World Health Organization's pandemic declaration, government regulations that make performance impossible does not end the court's analysis, and parties seeking to avail themselves of force majeure must still establish inability to mitigate along with impossibility of performance, or such other standard as the clause requires. As a result, companies should continue to closely monitor COVID-19 developments and their potential impact on contractual performance and take and document all reasonable steps to mitigate where possible, their effect on business operations. Recent events, including the declaration of COVID-19 as a pandemic and the implementation of travel, movement, and gathering restrictions, have altered the force majeure landscape in a manner that may impact the availability of such provisions to non-performing parties. Again, it would be prudent to document all the efforts to mitigate damages such as any efforts to curb expenses, get forbearance relief, and the like. Next, we'll talk about some non-contract defenses to performance: impossibility, impracticability, and frustration of purpose. In the absence of a force majeure clause in a contract, parties are left to the common law contract doctrines of impossibility, impracticability, and frustration of purpose. Typically, courts have a narrow view in applying these defenses to a particular factual situation. For impossibility, The defense is impossibility in the nature of things. The impossibility must be in the nature of the thing to be done and not in the inability of the promisor to do it. So one example is that one who binds himself to a contract which cannot be performed without the consent or cooperation of a third person is not relieved of liability because of his inability to secure the required consent or cooperation. As another example, after a hotel contracted with a country club to extend golfing privileges to the hotel guests, the court excused the hotel from paying for club privileges for its guests because, without fault by either party, the hotel was entirely destroyed by fire. Note that mere unforeseen difficulty or expense does not constitute impossibility and ordinarily will not excuse performance. The hotel case that I mentioned is in the minority of cases that excuse nonperformance for impossibility. On balance, courts have been reluctant to excuse nonperformance. On the grounds of impossibility. There also are a number of California statutes that have some support for the proposition that a contract or term that is impossible to fulfill is void. Civil Code Section 1441 states that a condition in a contract, the fulfillment of which is impossible or unlawful, or which is repugnant to the nature of the interest created by the contract is void. Section 1511 states that performance is excused when such performance is prevented or delayed by the operation of law. That same code section also excuses performance when it is prevented or delayed by an irresistible superhuman cause. And Section 1596 states that the object of a contract must be ascertainable by the time the contract is to be performed. So what does operation of law mean? What exactly is an irresistible superhuman cause? It is something akin to an act of God. Impracticability. Where after a contract is made, a party's performance is made impracticable without his fault by the occurrence of an event, the non-occurrence of which was a basic assumption on which the contract was made, his duty to render that performance is discharged unless the language or the circumstance indicate the contrary. Here is an example excusing non-performance. After the outbreak of World War II, the United States government ordered a shipping substitution of one set of goods for another. When the party who contracted for the original goods claimed a breach against a supplying party affected by the U.S. government order, The court excused performance, holding the risk of such government action is not one that the owner has agreed to bear, even in the absence of a force majeure clause, and it is not one that by common practice and opinion he should be required to bear. Note that the L.N. Jackson case is a Second Circuit case, so it is not binding in California. I think the L.M. Jackson case is also an example of, quote, operation of law from the last slide. Frustration of purpose may also excuse non-performance and ordinarily pertains to supervening events. It may be established where, at the time a contract is made, A party's principal purpose is substantially frustrated without the party's fault by a fact of which the party has no reason to know and the nonexistence of which is a basic assumption on which the contract is made. It is not enough that a transaction will become less profitable for the affected party or even inflict a loss. The frustration must be so severe that it is not fairly to be regarded as within the risks the party assumed under the contract. Frustration of purpose is another defense that courts tend to apply sparingly. So here's another example. A government order restricting the sale of new automobiles during World War II did not excuse a party's contractual obligations under a lease, even though 90% of the gross volume of the business was derived from new car sales. The California Supreme Court reasoned that the sale of automobiles was not made impossible and that if a government regulation does not entirely prohibit a business but merely restricts it, a lessee is not excused from performance. The court also relied on the facts that the lessee was an experienced automobile dealer, and at the time the lease was signed, risk of war was reasonably foreseeable. As another example, in a landlord's action for declaratory relief regarding a lease of a building in the Japanese community to a Japanese tenant for the purpose of operating a hotel and renting office space. The tenant defended on the ground of frustration of purpose because of a civilian exclusion order that excluded all persons of Japanese ancestry from the area in which the hotel was located. On these facts, the court held that the evidence was insufficient to establish that the value of the lease had been destroyed so as to relieve the tenant from his obligation. To perform. These two cases show that it may be very difficult for many non-essential businesses to use frustration of purpose to excuse non-performance. A restaurant or other retail tenant could still sell goods— sell its goods via pickup or delivery, so it would seem that shelter-in-place restrictions do not entirely prohibit their business. This would seem to be a very difficult outcome, though. So on the other hand, an emergency war measure during World War II which ordered cessation of all outside lighting at night, including neon signs, excused nonperformance under a lease. The court found that even though it remained possible to light the signs during the daytime, it was not the desired object to be obtained by the parties and held that if a government order frustrates the purpose of a contract without the fault of either party, the parties are excused from further performance. So what about other nonessential businesses? Perhaps businesses like theaters, gyms, bowling alleys, salons, Event locations such as sports stadiums, museums, casinos, shopping malls, and the like may have a better argument to excuse nonperformance, as it seems the entirety of their businesses have been shut down by the government's response to the coronavirus. Has the purpose of their contract been frustrated by the shelter-in-place orders so that they are excused from performance? We'll have to see. We should also note that it's possible for the duty to perform to be suspended rather than excused or discharged. Let's move next to discuss the CARES Act and a possible increase in bankruptcy filings. As you know, the CARES Act is primarily targeted to provide emergency assistance and healthcare response for individuals, families, and businesses affected by the 2020 coronavirus pandemic. The CARES Act makes some important changes to various provisions of the Bankruptcy Code, including importantly the Small Business Reorganization Act. The SBRA created a new subchapter under Chapter 11 for business reorganization that is commonly referred to as Subchapter 5 and aims to give small businesses a faster and less expensive option for reorganizing under Chapter 11. Under the SBRA, a business qualifies to file a case under Subchapter 5 if its debts are in the amount of about $2.7 million or less. Under the CARES Act, though, Section 1113, it increases this debt limit from $2.7 million to $7.5 million. As a result, the CARES Act will allow many more businesses that may benefit from a Chapter 11 reorganization to take advantage of the new subchapter provisions, including the more relaxed requirements for confirming a plan of reorganization. Reorganization. The impact of this change significantly increases the number of small businesses that should consider a Chapter 11 reorganization as part of its plans to recover from the COVID-19 pandemic. Note that Subchapter 5 is itself a new law that only became effective in February of this year, so we really have no statistics or anecdotes about the volume of businesses using it. This crisis, though, will surely increase its use, and the increase by the CARES Act of its availability to small businesses will support that increase. The CARES Act also makes some adjustments to Chapter 7 for liquidation and Chapter 11 for wage earner bankruptcies. These changes to Chapter 7 and Chapter 13 are not as newsworthy but are still important changes to those debtors. Well, the last note here is that all of these changes are applicable for 1 year after the CARES Act becomes effective. There are also some other related practical issues. That I think we should discuss. Insurance for business interruption— unfortunately, it may not be available to cover for loss of income due to the COVID-19 crisis. This type of insurance provides coverage when a policyholder suffers a loss of income due to direct physical loss or damage to covered property. It does not generally cover loss of income due to market conditions, a slowdown of economic activity, or a general fear of contamination. Nor does the policy generally provide coverage for cancellations, suspensions, and shutdowns that are implemented to limit the spread of the coronavirus because these are not a result of direct physical loss or damage. Thus, it appears business interruption losses resulting from these types of events may not present covered losses. So that's mostly bad news about insurance, but I do not regularly practice in the insurance area. But I have many colleagues who do. Property tax deferral. While the April 10th deadline for paying the second installment of property taxes currently remains unchanged, penalties and other charges resulting from late payments due to the COVID-19 crisis may be waived. Tax collectors may waive late payment penalties under certain circumstances. Note that this relief is discretionary and will be evaluated on a case-by-case basis, and that taxpayers unable to pay by April 10th will need to request relief and demonstrate to the tax collector that the inability to make a timely payment was due to the COVID-19 pandemic. Los Angeles County's tax collector has set up a special team to process penalty relief requests, and other local tax collectors are starting to discuss the same thing. Federal and state income tax referrals— deferrals due to the COVID-19 pandemic. Federal and most state income tax returns have been deferred to July 15th, and that includes tax payments. So this April 15th, we may have less meaning than it used to because tax day is now July 15th. We're running up against our time limitation here, so this would be the time that we should answer and discuss any questions or comments. I have seen— while those comments are being gathered, I have seen some forecasts that predict this recession will be deep and it will be fast. They also seem to indicate that a recovery will not start until the fourth quarter of this year, if not later. I'm also very concerned about the health of our financial institutions, particularly lenders and servicers in the securitization arena. I understand that lenders must continue to make payments to bondholders or otherwise service their own debt. Even if borrowers are unable to make their loan payments. So where will the buck stop? Who will be left holding the empty bag? We did learn a lot from the Great Recession, though, and I believe the leverage levels of lenders are much lower and reasonable than 12 years ago, so that should definitely help. It's definitely a very difficult time for everyone. One thing I keep telling myself is that we will get through this crisis together. Okay, I see a couple of questions here. Let's see. Is a provision to a personal guarantee of a commercial lease that states the guarantee remains enforceable even in a bankruptcy by the guarantor enforceable? So generally speaking, if the borrower files for bankruptcy bankruptcy, that, that should trigger a guarantee of a lease. So I don't know the specific terms of the lease and the guarantee that you're asking about. But then I think you're asking is if the guarantor itself files for bankruptcy, is that— does that trigger the guarantee? Normally bankruptcy defaults in a contract are not enforceable as ipso facto clauses. So there are a couple of provisions in the bankruptcy code itself that specifically identify bankruptcy defaults as not enforceable. So I can get you those code sections citations afterwards. Nick Wheel also has a question. Holding aside COVID-19, in general, it seems like it would be tempting for a lease agreement drafting landlord or management company to try to say get a tenant to waive impossibility, impracticability, frustration of purpose. In other words, essentially to enter the lease as is. Are you aware of voiding as against public policy such a waiver clause, even assuming conspicuous language, language, initials by tenant, etc.? So Nick, I have not looked at that question. Um, it seems to me that the first thing that pops into my mind, uh, though, is unconscionability. Because if a tenant is forced to agree to essentially waiving a bunch of defenses to performance at the outset, there's unequal bargaining power between the landlord and the tenant, and it may be unenforceable. The waiver may be unenforceable as unconscionable. If anybody has any comments too, or you're welcome to make the comments to the group. I just wanted to mention that I'm always available for follow-up questions or comments via email or telephone.
All right. Is that all set there, Philip?
Yeah, I just wanted to thank everyone for participating in the webinar. I hope you found it useful and maybe even interesting. Remember to keep your social distance and to keep washing your hands. And I just wanted to say thank you and stay safe.
Perfect. Just a reminder, everyone, an email will go out tomorrow that will be from us. It'll ask you to respond with your state and bar number, and then we will send you your certificate as well as the slides.
Thank you.
If you have any questions, feel free to contact Phil or myself.
Have a good day.
More from Jessie
Non-Competes and Confidentiality Agreements & What to Consider When Closing a Merger or Acquisition
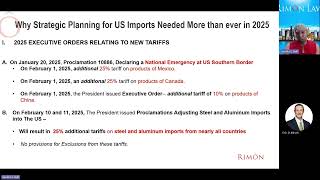
Strategies to Minimize Duty Liability in the U.S. Heightened Tariffs Environment
Coffee Talk: Navigating Leave Laws: Ensuring Compliance and Managing Employee Absences Effectively
New Year, New Laws: Significant Employment Law Developments in 2024 and What to Expect in 2025