How Do I Exit and What Happens Next with Justin Kan, Jess Lee and Mike Marquez
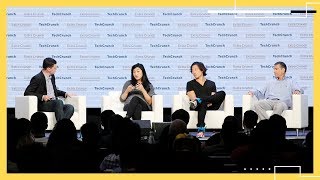
Justin Kan, Jess Lee, and Mike Marquez discuss when and how to sell a startup. Start building relationships with potential acquirers early, focus on making a great company first, and keep sale talks quiet to avoid distracting your team. You'll need a champion inside the buyer's company, and timing matters: sell when it accelerates your vision, not just because investors want liquidity.
All right, thank you so much. And we look like we're filling the crowd. There's still some seats on the right and left for those standing in the back. But I'm really excited about our panel right now. How do I exit and what happens next? I think particularly at Disrupt and particularly at TechCrunch, we talk a lot about groups growth and building startups and going for the stars. But at some point, all startups exit. They either get acquired, they go to the public markets, some go bankrupt. And the part of the discussion today is to start talking about how do you start to think about exits? When do you start to think about it? When, as a founder, do you start to reach out to investment bankers? And so I'm super excited to have three founders on stage. All the way on stage. Right. Mike Marquez runs one of the leading investment boutique investment banks here in Silicon Valley, which is Code Advisors, which was started 10 years ago, has run dozens and dozens of M and A deals and financings, and has done more than $100 billion of transactions. Thank you so much for joining us. Next we have Justin Kahn, CEO and founder of Atrium, a law firm for startups. Formerly, Justin was at Y Combinator. And finally, we have Jess Lee, partner at Sequoia and formerly the founder and CEO of Polyvore. Thank you so much for joining us. So I want to start with you, Jess. You exited your company Polyvore a couple years ago to one of our many parent companies, Yahoo. When did you start to think about exit opportunities in that context?
So, to be honest, I thought about it too late. I thought about it when it was time. And I think the lesson I took away from that, which was what happened to me was I realized it was probably time, and so I started to spin up these conversations, and I didn't have all the relationships I needed in place. And so the advice that I would give is, as founder, as CEO, part of your responsibility is, you know, you have to set the vision for the company. You have to set the culture and the team, and you have to make sure you don't run out of money. And part of running out, not running out of money, is having those options. Right. So having, you know, just the same way that you build relationships with investors, you should spend at least a little bit of time building relationships with partners who could eventually become potential acquirers, I think being known to them. And so that time when you need to have that phone call is not the very first time you've ever had that phone call, which is kind of what happened to me, in some of the situation, in some of my conversations, I would say you need to start doing that earlier. It's not like a huge part of your responsibility, like you shouldn't spend a ton of time on it, but a little bit of time upfront. Investing in that longer term relationship is really important because I think while it is a transaction between two companies, it's a transaction between two people. And people care about buying a team and the people that run a particular company. And it's important to have that relationship not be completely cold at the moment when you need to have a transaction perfect.
And as a reminder to the audience, if you'd like to ask questions, this is an interactive panel. Open up the TechCrunch Disrupt app. We're in the how do I exit and what happens next panel. And you can ask questions to me and I'll look at this iPad, assuming the WI fi still functions. But Justin, going to you real quick. So you both exited several companies and now you also run another startup. How do you, how do you think about exits now with Atrium?
Well, I haven't sold a company for a long time, so this might be like last year's textbook, but before, I would say like in my, you know. So I started this company, Justin TV and then eventually turned into Twitch and we ended up selling Twitch to Amazon for a lot of.
And.
I think that in that there's really. I actually think I had the opposite experience of Jess, where we thought about exiting like too much. We were very desperate and thirsty and we really wanted to sell the company. At a certain point when we were about maybe three to four years in, it was like we were very fatigued. It was not going so well. It didn't look like it was going that well. It looked pretty flat. So this is when we were adjusting tv. We were like, oh, we should try to sell the company. And so we were desperate. We were so desperate. We actually, we got into this conversation with Google and they were kind of interested and we just let them interview our entire team, which you should never do. And we like clearly wanted. And then eventually they were just like, your team's not good enough and we're not going to do this deal. And then the second time around, you know, we ended up four years later kind of going back to the, back to the. Well with Twitch, it was a completely different scenario, you know, because we were like, the company was doing much better actually. It was growing. We had like a really strong community. There were very strong network effects and community effects now and Things were looking a lot better. And so my lesson there was really like, you know, the best way to sell your company is to actually build a good company, not to, like, have a dog shit company and like desperately try to sell it through some know, I always thought there was like some formula or something, but. But actually, just focusing on the company was the best thing that we could have done.
And, Mike, I think you might actually be one of our first active investment bankers ever on stage at any disruptive history of 16 years here, what does an investment banker do in Silicon Valley? And particularly for founders who probably think of you as Wolf of Wall street, suits and ties at Goldman, what goes on in your life?
Sure, yeah. So, you know, now obviously I don't have a suit, so. And just to echo a lot of what Jess and Justin had said, you know, a lot of the work that I do, especially with companies, is help them start to think about exits much earlier. And again, this isn't put a for sale sign up on the company when you're a month old and actively shop the company around. But again, everyone's heard the adage, you know, great companies are bought and not sold. But the corollary to that is you have to be known to these acquirers in order to be bought. And that happens with what Jess was saying, developing these relationships well in advance of an acquisition, whether it be to that acquirer or whether that be once someone does start to express some interest, then you can decide, is this the best possible outcome for you, both in terms of price and in terms of company. And so a lot of the work that I do in the upfront is helping companies to develop that sense of how do you reach out commercially? Who should you be talking to? How should you be talking to them? How do you start to develop these relationships? And then as that starts to develop and as companies start to express some interest, to Justin's point earlier, how do you interact with them? Do you allow them to interview all of your employees? Do you allow them to have free reign of all of your information out there? A lot of that is the advice that I work with in companies. And how do you navigate through that in a way that, you know, isn't disruptive to you and, you know, helps to get them the information and then all the way through the process of, you know, helping to negotiate the transaction? And frankly, the most value that I provide is actually getting the deal done. And so that's what I do.
So I want to open the floor to everyone here. So when you as a startup Founder as an investment banker advising founders, like what is the responsibility for a founder to consider exit opportunities or to create them? Should they be doing that all the time? Should they be receiving any sort of inbound, should they be ignoring it if they feel like everything is going right? You know, what responsibility do they have?
Sure, I mean, I'll answer and then maybe everyone else can add on to it. I would say kind of similar to what Jess had said earlier. Like a CEO's responsibility is, you know, first and foremost keeping the company alive and giving it options. And so just as much as you hear, you know that one of the core functions, functions of a startup CEO is raising money and how you're always raising money until you're not raising money. It's the same way with exit opportunities. Right. You should always be thinking about and developing these relationships well in advance of that. And again, the reason why is because you should be more in control of this. Hopefully this is an outcome that's a cake and eat it too type of scenario. It's a, this is a great partnership that we really wanted and it's an acceleration of our vision and it's the best price and the only way that you'll know if it's the best company and the only way they're going to be willing to pay the best price is if you spent the time to get to know them. And so I would say 100% the founders, one of the founders responsibilities is developing this. Now again, that's, you know, balanced against all of the other things that a CEO needs to do as well. But again, there should be a little piece of it that you do early on.
I think that like in the beginning, your responsibility as a founder is to just find product, market fit, work on your product. And then once you have a product that people want, you want to figure out how to get in the hands of more people. And that's when it starts to become really valuable to know everyone in your market and in adjacent markets. And at a certain point in your company, you know, it is your responsibility to like actually be out there talking to all the people who could be strategic partners for you or distributors or where there is some sort of a creative partnership. And those are generally the people who are going to turn into an acquisition. And so I like to think about it like you should be knowing those people, building relationships with them, thinking about what you could do with them, but not necessarily like trying to sell your company.
Let me ask you, who drives the momentum around a sale? You know, let's Say you're going through a process and you're like, you know, Justin, like you said, you know, you're desperate. I want to get something done. Like, who actually is going to get that all the way to a close? Is it the founders? Is it the investors? Is it investment bankers, Is it the corporate development officers who trying to drive towards a sale?
Usually it's not your investors, in my experience. I mean, I don't know, I don't have that many data points, but I think it's really, you need a deal champion inside that company who really believes in the accretive value of owning your company. And if you don't have that person, then it's really not going to get done. So really finding, getting somebody at that company who's like, we need to buy this company because of X, Y and Z reasons, it's really good for us. Hopefully that person's the CEO, but maybe it's another executive in the company. I think that's super important and that's kind of a prerequisite to getting a deal done.
Yeah. I would also say it's interesting to sort of compare and contrast it with the fundraising process. With the fundraising process. You're, as a founder, you're kind of pitching like, I'm a unique, special snowflake and this is who I am and this is what our company does. And here is the timeline for the fundraising. And, you know, you try to line things up schedule wise so that you get an answer by a particular time. I would say with M and A, it is a lot less about you and it's more about the acquirer.
Right.
So I think at first what I did was I made the mistake of going in and saying I'm a unique, special snowflake and kind of reusing my same fundraising pitch. And I kind of realized over time, like, you have to fit into the strategic priorities of the acquirer. So then I started to do a little bit more homework and I looked at each of the acquirers and I thought, what is their strategy? What, who's the right champion, to Justin's point, inside this company and how do we actually fit as a strategic asset into this company? And then I started to change the pitch a little bit to be more about them and their strategy and where we fit in. And so it was still pitching the same company, but with like a slight twist on like the value prop, because it was slightly different for every company, for every acquirer. And I didn't control the timeline.
Right.
Oftentimes M and A might be Triggered by the acquirer maybe has known you over multiple years. You have that once a year coffee and they're like, wow, we just decided to invest in gaming. And so what's out there? Like, well, I've known Justin for the longest time and it just sort of fits what we need right now. And it's like sort of an internal trigger more than an external one. So sorry, sort of a, it's, it's their trigger, not necessarily yours. I think it's very hard to just conjure an acquisition unless there's competitive dynamics. And oftentimes it's triggered by what's actually going on inside the acquirer.
Yeah, yeah, no, I mean, I agree exactly with what was said. And again, spending the time with the acquirers is exactly for that point. It's to help understand how you best could fit into that. What you can help to accelerate how they, you know, how strategically important what you are doing is to them. And again, with multiple potential acquirers. Right. Spend the time with them. And the way that I like to think about this is, you know, first and foremost, you know, as Justin said earlier, great, great companies, when they, you know, when they have a great outcome, it's because they were great companies. That's what you started with, Right? And so first and foremost, like, focus on that, focus on building a great company. But with that said, building relationships with these other outside potential acquirers, it can be a win, win. Right. It could be a commercial relationship or it could be an acquisition. And that's the way you should be thinking about it as well. This could be a future partner, whether this be an acquirer or not.
So many of you have worked on multiple sides of these tables. So you've been founders, investors, advisors, and sometimes there's tension in that relationship. Right? Sometimes your investors want to sell and maybe cash out. The founders do not, or vice versa. Maybe the founders are sort of checking out and the investors want you to go farther. How do you sort of navigate differences of opinions either in between different investor classes or just from the tension on the board?
You know, I mean, I've been in a number of situations where there have been, you know, investors that have been pushing for a sale or, you know, they have a, you know, timeframe that they're trying to adhere to. What I found out is in general, that doesn't lead to a great outcome. Right. Like just because an investor wants to sell right now, as Jess mentioned earlier, you can't really control timing. So there could be a whole bunch of reasons for why now isn't Right. It could be because we're too early and we haven't demonstrated product market fit. It could be because we don't have enough relationships here for them to know how to properly value us. A whole bunch of reasons. And so for that, what I think is a better way to navigate this is, again, it's great to, to be able to engage in those conversations and find out why, because there's a bunch of other solutions that may solve that problem. Right. An investor may have a fund that's ended four or five years ago and needs to get some liquidity. That doesn't necessarily mean the company needs to be sold. Right. There's secondary transactions. There's other things that can be done to get that investor the liquidity that they need. But I think the best way to navigate through this and again, whether that be investors or whether that be, you know, board members or founders or whatever it is, because sometimes there's founders that have difference of opinions, you know, kind of amongst themselves. But talking it through and finding out, like, what are you really, truly trying to, what's the problem here? And let's try to creatively solve it. I think that's the better way to handle it, rather than a, there's someone here that wants to sell the company. We need to sell this right now. And some investors I've seen that have been more aggressive around that. And that's never a good thing. Right. Trying to do some things on their own without the, you know, the rest of the company on board with it. And like I said, I don't think that ever ends up in a good situation.
Either of you want to answer?
If not, I agree with that, 100% agree.
Yeah.
Let me move on. So this is also addressing one of the audience questions here. Your CEO, you know, there's a sale process going on. The board's kind of committed. You're going through a process. Maybe there's an asshole like me who works at TechCrunch who's leaking data about what's going on in the sales process, that we got something from Google or Yahoo. How do you handle employee questions about this? You're at a TLDR or whatever they call these TGIFs on Friday, and one of your employees goes, hey, are we, are we being sold right now? Like, am I going to have a job next week? Like, how do you, how do you think about, you know, leading through that sort of situation?
I, I tried to keep our acquisition process quiet. It's just very distracting for the team. And you have so little control over it. I'd be very transparent about pretty much everything else at my company. P and L, like cash, Runway, metrics, fundraising process. And the fundraising process is different is because you kind of control the timeline. For M and A. I kept it very, very quiet to a very limited number of people. And that was actually one of the hardest things for me personally, because I was so transparent with the team and to suddenly be, like, mysteriously out of the office or sick at home when I was actually flying to New York or pitching somewhere, it was really that. That was part of the hardest part of the process was the not being able to be completely honest with the team. But I think you don't want to set up the team for some grand expectation. You just don't know what happens. Right. It's just not done until it's done. It's like 50%. One of my mentors told me it's 50 probability until the money is in the bank.
Right.
And so just believing that it was really. I preferred not to share it with the team to get there. It was just too much of a distraction if it was leaked, though. I mean, I think you have no choice but to be. I wouldn't recommend you lie to your team. So I think you just have to say, yeah, we are exploring some conversations, but who knows what will happen? Odds are never great in these conversations. And we should just keep. The most important thing is to build a great company.
Yeah. Can I just add to that? I mean, it is an incredibly distracting process, as these two know. And so again, adding the additional layer of having employees who aren't fully aware of everything going on, it makes it even more distracting. And as Jess said, you don't. The deal's not done until it's done. And so to bring you kind of your team through these kind of fits and starts all the way along can be an incredibly jarring experience. And at the end of the day, we keep saying this over and over again. Build a great company. You know, taking your team and saying, oh, we're not going to do this because we're going to get sold. Oh, wait, we're not going to get sold. So do this. Wait, we are going to get sold. Like, that's not the path towards building a great company. And so, again, as painful as it is, and I've worked with a lot of CEOs who are similar to Jess, where you're completely open, this is one area where you're doing a benefit to all of your employees by keeping it, you know, kind of A little bit more under wraps. Again, what I found is once you do, employees are very understanding of, you know, kind of that kind of what needs to happen there. And then once it is done, I'm sure Jess did this as well, you come clean and you say, hey, listen, this is what happened. I'm really sorry I wasn't sick that day, but this is what happened. And so, again, it is a little bit more of a cathartic experience for the CEO as well, but it is incredibly distracting. And so managing that is key.
Justin, I want to ask you, I mean, you've coached a lot of founders, obviously, you know, through Y Combinator, I'm sure today, as an angel as well, how do you address exit opportunities in a fundraiser? Is that something that founders at the Seed or the A or the B, should they be addressing that in those conversations? Either what they personally want or maybe the potential opportunity in a company?
I mean, I think the thing that we always do at yc, and really, I would say it's true, what I tell people today is just like at the seed stage, a stage, you don't really want to be thinking about that, and I don't think you really want to be talking about that with potential investors, because I do think that's an adverse signal, whether it's true or not, that you want to, you know, we would sell the company for whatever, 50 million bucks. I don't think that's inspiring to investors who want, you know, want to believe anyways that yet want much larger outcomes. So I think it's really, you know, you should just focus on building a good company at that early stage. You know, that's the number one thing you need to do.
I mean, this might sound odd coming from an investment banker, but everyone knows I'm a different type of investment banker. I don't believe companies should ever actively be looking for an acquirer.
Right.
Like you should be actively working on building a great company. Now, that said, you should be opportunistic in how you think about this. You should build the relationships as we talked about before. You should try to maximize the outcome as it comes. But as Justin said, you know, kind of especially in the early days, you're going to create substantially more value by creating a great company than you are by looking for someone to acquire you at that stage.
And even actually at the later stages, when I've been, you know, in C stage companies or, you know, companies have raised a lot and have a real product, and they've always said, oh, maybe I should check the Market and see if I can get an acquisition versus, like, what our next fundraising round would be at. You know, those acquisitions, you know, talks that they try to generate have never really. I've never seen that work in that way when they're trying to run it concurrent with a fundraising process. Super. Well.
So one of the questions from the audience, how do you know when it's the right time to sell? Like, is there a moment in each of your companies, and particularly for Jess and Justin, when you were like, nope, this is definitely like, we're done, and we need to, like, find a way to exit.
There's nine zeros.
So when the number gets big, I.
Mean, I think it's always the. Again, this is where there's no kind of concrete answer. This is why, like, you know, if this was easy, then everybody would be a CEO. Everybody would, you know, have a startup. At the end of the day, you're always trading off, you know, kind of the risk reward that. And again, hopefully in an acquisition, this isn't a, we're done. We don't want to do this anymore. Hopefully, this is a great outcome where it's. It's an acceleration of the vision that you wanted to build from the beginning. Hopefully, that's what. And at some point in time, you meet the right acquirer. Right? You meet the right, you know, in the kind of. You've developed the right fundamentals of the business and the price is right. And you look at, okay, what's the value that I could create on my own versus partnering with someone? That gets me the scale of a salesforce. It gets me the scale of distribution or gets me the scale somewhere else, and I accelerate this vision, okay, now is the time. Right. Those numbers are lining up the trajectory of what I can do, and the acceleration that I can get through a partner is right. It's kind of similar to, you know, when's the right time to find your spouse? It's very similar. Right. It's not. You need to. There's no kind of formula for X, Y and Z, and here's your spouse. It's much more. When is the timing right and what does this feel like for you?
So, Jess. Oh, go ahead.
Yeah.
So I'll just say what happened with us. We were about, I think, seven and a half years into the journey, and I'd had a team that had, like, come really far along that journey with me, and I felt like, oh, my God, I need to. Some of these people have been with me for so long, and I just really owe them and for us, what had started to happen was we, we were in the middle of the desktop to mobile shift and we built a great business on the desktop platform and we were not having as much success on mobile. And so I could see that at some point we needed to reinvent ourselves for mobile. And I thought, all right, reinventing ourselves for mobile, we'd have to change the product, we'd have to do a lot of different things. We'd tried multiple things and it hadn't yet been clicking. And so I was like, all right, we are back to the early seed product market fit hunting stage in mobile for our business. And that I know from experience could take anywhere from like one to four years. And I thought about, okay, do I, do I have the energy to do that and does this team have the energy to do that and are we willing to take the risk of continuing to go on in this state? And as I was thinking through that, honestly, two acquirers reached out in the same week and I was like, maybe this is a sign. And so then I started to pull the trigger and like talk to more and more of the acquirers. But for me it was, it was a lot of the decision came down to like, what's the right thing to do for this team here? I thought about will they stay through having to like pivot our way into a brand new mobile app or not? And what do I owe the team? And so that, that, honest, honestly, that's how I thought about it.
A little less facetious answer on my part is I think that, you know, you really want to put yourself in the headspace where you can make a rational decision. And I think that lots of found, you know, I've been there myself a lot of both times, you know, on their acquisitions, well, all the ones I've been part of. But then also with a lot of founders I've advised where, you know, they're burned out or tired, you want something, want to do something different. And I think that's so they think like, okay, I'm going to sell my company and then like it'll, everything will be better then. And I think the actual answer for founders is really to try to create an equilibrium in there because you don't really control whether an outcome is going to happen at any given time, even if you wanted to, or you're burned out. You want to create a situation where you are okay with what is going on, like in your company, like running your company every day and you're not like desperately seeking something else, like some sort of like acquirer to come deliver you from, you know, your present day sorrows. And, and I think that too many founders are looking for. They really think of this acquisition as like, okay, it's just something that's going to happen that's going to save me. Whereas really what they should be focused on is getting right with their, like every day at their company and being more at peace with what's going on in their company, like accepting kind of what's happening. I think that's something I wish so that when they do have someone coming and saying, hey, I want to buy your company, they can make a right rational decision. Not like, oh, I'm tired. Yes.
So each of you, including Mike, what are the factors that go into selecting you went through this process. And I'm addressing an audience question here. You have a couple of different suitors, maybe a couple of different options, different prices, different, maybe quality of companies, maybe a couple of different, other kinds of terms. Like when you were thinking about how to exit, what was sort of the criteria that you were looking for in selecting between offers or, you know.
More from Jess
Sequoia Partner & CPO Jess Lee: What Great Founders Do Early and How AI Will Change Consumer Apps
Sequoia's Dannie Herzberg and Jess Lee on Building an Enduring Firm | Upfront Summit 2022
Creating B2B2C Marketplaces Lessons from Wonolo - Jess Lee, Sequoia; Yong Kim, Wonolo
"Lessons Learned in My Startup Journey" at Founders Embassy's Borderless Summit 2018