How Startups Can Survive and Thrive in a Downturn
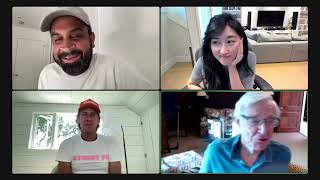
Jess Lee from Sequoia, Dennis Crowley from Foursquare, and Alan Petroff discuss how startups survive downturns. Extend your runway and cut nonessential spend first. The downturn creates recruiting advantages and market share opportunities for companies that focus on organic growth and meet customers in person.
Good afternoon, everybody. Happy hump day. We are getting a lot of folks to join our session this afternoon, so thank you for joining. We're going to kick off now. This webinar roundtable is called How Startups Can Survive and Thrive in a Downturn. It's a very timely topic and we're really happy everybody could join us. Quick reminder before I introduce our incredible panelists, you can submit your questions anytime via the Q and A button in the Zoom webinar. And now, without further ado, and as I announce each panelist, you can magically appear on video. First is Jess Lee, a partner at Sequoia, a great friend. She was formerly the CEO of Polyvore, before that at Google, and she's amazing. Just wave to the world. Awesome. Dennis Crowley, also a dear friend, a legend in New York Tech, co founder and chairman of Foursquare, previous to that, Dodgeball, which was also acquired at Google. I think you guys may have overlapped back in the day. And last but not least, a legend among legends, a living legend. Alan Petroff, thank you for joining. Alan is founder of Apex and Graycroft. He's got an incredible book out by the way right now called no Red Lights. We're going to drop the Amazon link in. It's a mandatory purchase for everybody on this webinar. It's an incredible read, by the way. I was just telling these guys I read more of it than my wife's latest book, don't tell her. Alan's also running the marathon this year. Walking, running the marathon this year at age 88. So he's an incredible inspiration to us all. But thank you everybody for joining us. I'm going to kick off with you. With more than half a century in venture capital, you've invested through more recessions than anyone here. How do you think this moment compares to past downturns? And how worried should we be?
Well, thanks, Nihal, for being so gracious in your opening remarks. You know, I am living through this like everybody else and my new firm, Primetime Partners, which is focusing almost all on startups. We see the issues you're talking about, but you know what's concerned me for the last year or two is that almost everybody I deal with, and I don't want to refer to people on this call, have not lived, did not live through 99 to 2001. And they have a very positive attitude. Everything is going up. And every entrepreneur sees everything the last couple years going up. And most venture capitalists see everything going up somehow. 2008 didn't hit as much. I think that there's still a moment of euphoria that people haven't come to realize that there are cycles and that we are probably in one now. And the question is what the depth is. The question is to get ready for it. But how this compares so far mild compared to what could be. But clearly it's a moment in time to get hold and to prepare for it. Even if it hasn't hit you yet, you may have it happen, but in a way it's a positive that it's. Think of it as a I hate to refer to the Supreme Court decision, but maybe they let loose two months in advance this terrible Roe vs Wade decision let a little air out of the maybe what we've seen the last two months is kind of decompressed a little bit and made people look carefully, more carefully than they had been.
Jess Polyvore I know when you took the helm was kind of right around the time post financial crisis, like when you were running the company, kind of what was going through your head at that time?
Yeah, we, we started before 2008 and had a pretty good ride. Found product market fit and we were growing. Then 2008 hit and I remember seeing the sequoia rip good times presentation and it had a lot of the prediction of the coming crash what was going to happen. I remember a slide that said death spiral and the founders who react quickly would survive versus those who are too slow. And I just remember that the most compelling thing for a mint was like move quickly. We were really small at the time so there wasn't a lot to do. But I remember thinking like wow, this, this, this grave warning is pretty scary. We did manage to eke out a Series B at that time of like $5 million now know might be a large seed. And I think what happened was we got really, really good at growth, organic growth. So we figured out before the term growth hacking existed how to grow on Pinterest, grow on Tumblr, grow on through SEO. And I think some of those practices and being forced to do that made us one of the consumer companies that like stuck around for longer and was always able to like thrive on our own community talking about us. And I think hopefully that's something you'll see now with less capital available with like you just, you really need to eke out your survival. I think you'll see hopefully stronger companies built.
Yeah, very interesting. So it's made it made you more disciplined probably during that period. And Dennis, also you serve for Square right around the Same time.
Yeah. I mean, the thing is, I was just coming off of, I just left Google at the time and I was kind of decompressing, trying to figure out what to do next. And I remember around that time just being like, there's no companies. I did just like the hype of that previous cycle was kind of ending. I was like, there's no companies I really want to go work for. Let's go, let's start something else and start from things from scratch. And you know, what we experienced like in the early days of FourSquare, the first one year, two years, 2009, 2010, is that there was a lot of people in that similar mindset that were working at bigger companies and bigger jobs that were looking at what was happening in the market. And the economy is kind of a chance to reset their own, I guess, like, internalization of their careers and what they wanted to do next. And so it was easier for us to go and recruit talent and build a pretty amazing team in New York, which just at the time hadn't really hadn't been done from a startup. I remember when we were starting Foursquare, everyone said, oh, so this is great. You guys started in New York and you're gonna move out west. It's like, no, no, we're not gonna move out west. Like, we live here. We're gonna build this company here. It's like, yeah, but you can't build an engineering team in New York. It's like, we'll figure it out.
So it was probably helpful in your recruiting, right? Like during, like building it early. Like at that time, right when folks were on the market, there was a lot of access to talent.
Yeah, yeah. I mean, Google, if anyone had built a world class engineering organization in New York, it was Google. And I was just coming out of Google and the first couple hires we had were all out of Google. And the joke was always that took us about a year or so, but we reproduced the lunch table that we used to sit at in the Google cafeteria in New York. We just did it at Foursquare world headquarters down in Cooper Square, just poaching one person at a time. Mostly because they were just ready to leave. They had spent time at Google and they were ready to move on to the next thing.
Totally. You know, actually it was interesting. And LP this morning said, I asked him how long this thing's gonna last. And he said, you know, the longer the party, the longer the hangover. And this party was what, 12 years long or more, Alan. I mean, you know, You've seen a few of these iterations, I guess how, you know, how long should we be prepared for this? And I guess what's one piece of advice you have for younger founders who have never seen a bear market before?
Well, I think one of the bigger differences today is that I do think that most companies that I've seen have adequate cash or more than they did in the 2000 bird or 2008 perhaps. I think I can remember with horror every single week there was one of the companies in the portfolio couldn't make Friday's payroll. And I haven't seen a company yet. Oh, I'm sorry, I didn't realize my video was off. I haven't yet come across a company either recently or in the last couple years that you know, not been able to make a payroll. So I think they're probably even though everybody is out and now wants to raise a follow on round. I think in general companies are for the most part you can't generalize. But I think for the most part companies have more cash, are more comfortable, have more running room than there's not as much of this running out of money. The other thing I would say that these kind of times give you an opportunity for a halo or shadow over your head to say listen, we have to cut and it's a good opportunity to cut, as GE used to do. Remember every year they cut the lowest 10%. I always thought that was a terrible policy, but that's how they kept on upgrading. They got rid of the lowest 10%. Well, I'm not saying you do that, but if there are people you've been thinking about getting rid of, you can do it under the halo or the shadow of a tough economy and getting tighter for it. The other thing is I think there's, as Dennis said, it's easy to recruit in times like this because there are going to be more people around. They're not, they're not as arrogant in thinking they're going to have five opportunities. They may accept your offer a little quicker and a little more realistic basis. And the other thing is I and I'm not sure how much it applies to people on this line, but I always remember learning from it was either Procter, I think it was Procter and Gamble or but maybe Unilever saying the time they increased share of market was always in bad times. And I know it's not the same as a startup, but this is a time when people will be making moves that may give opportunities for people to go in and capture a Piece of business they might not have been able to get under other circumstances.
Yeah, there's a quote that somebody told me. I'm probably getting this wrong, but it's like easier to overtake other cars on the highway when it's raining.
Okay, great. I like that much better than what I said. Much shorter.
It's also a lot more dangerous to overtake other cars on the highway when it's raining. But Jess, at Sequoia, like, what do you guys, what are you guys telling your companies? I mean, obviously, you know, death spiral in 08. You know, everybody has seen kind of that the 50 page memo as well from last month. But what do you tell your companies right now?
Yeah, we called an all hands for the entire founder community about a month ago and then went through three or four different topics. Forecasting, fundraising, and then leadership in uncertain times. And I think it's no different than what Alan was saying. Like, this is a time to overtake, but you just need to survive first. So folks are all in different places. And so I think it's. There's no one single piece of advice, but the first is probably survive. And then, you know, I think the creativity breeds constraints and I think now is finally the best time to recruit. Honestly, that's probably one of the biggest benefits, I think. We've been in this crazy talent war for so long where you're competing with faang with crazy offers, everyone is recruiting everyone, and now suddenly we're entering this time where I think you'll finally be able to get a high concentration of really great talent and folks who are more missionaries than mercenaries. So I do think that, you know, I think it's. There's gonna be a little bit of a freeze for a while, it seems. But this is the moment to take advantage of the fact that if you do have the capital and you do have product market fit, now is a great time to find great people.
Dennis, in that vein, I know right now, you know, you're kind of back to creating, you know, a few different projects on your plate. Feels like it's a great time to kind of build. Not to steal, you know, Mark Andreessen's words, it's time to build. But what are your thoughts in terms of like building now, you know, versus like a year ago, two years ago, when there was like crazy access to capital. There are a lot of tourists on the investor and the founder side, and now they're gone.
Yeah, I feel like there's certain times in the cycle where there's just a lot of Noise, right? And I think there's been a lot of noise in the crypto space and the NFT space. And because there's so much noise, it's easy for people to look at those spaces and like, oh, it's just all nonsense. There's nothing right there. But there really are interesting projects that are going on. They're just buried under a pile of things that maybe are less interesting or won't survive. And I think these periods, what they do is, you know, they're like the great reset, right? Like, some of those companies go away, some of them get acquired, some of them get acqua hired, you know, some.
Go out of business.
And the interesting ones survive, right? Like, you know, I don't know what the version of this quote is, but like, you know, there's always capital for good companies, right? Like, capital's scarce when you don't really have something interesting, you don't really have something that's working. You don't really have something where people can't see the product fit. But like, if you're kind of toying around in just areas, then, you know, opportunities arise. I think one thing that's different is back when we started Foursquare, there was something new. At the time, the iPhone was brand new. That was a big technological change. We were just messing around with different mobile stuff before then. There hasn't been anything new in a while. Watch VR, Arkansas. It's there. But what's going to be the next thing that resets everything, gets people excited? Is it some mainstream application of crypto? Is it Apple's magical glasses? Is it something else? So when we talk about when do you pin the end of this cycle, it might be just another generation of hardware which then spawns another generation of experiences that need to get built.
And that could be, I mean, the mobile analogy of 08 could be the web3 analogy today, potentially. There are a couple of questions on the investment side that came in. And Alan, for you, Prime Tom or Graycroft, how do you decide in this environment which portfolio companies to keep funding and which ones do not meet a performance standard? Does discussion today inform portfolio companies to optimize that funnel? How do you think about that?
I think two of the biggest problems in the venture business and probably in every industry, one is how to say no to someone and do it gracefully. And the second is to decide deciding which companies you want to keep supporting. I try to follow a. I don't want to say rule because I certainly violate it all the time, but I think about it a company that I've invested in a first round and say to myself, do I still think the management is as good as I did when I paid the investment? Do I still think the market opportunity as big as I thought it was? Do I still. Do I think the product development has come along as much as I had anticipated. I mean, how far are we behind? And the economics work as well as I thought as the margin analysis or whatever. I use my metrics. Has that changed now? It's very simple. If all four of those. If I don't like the management, the products development is slow and the market is, you know, et cetera. That's an easy decision. The problem arises when you have one that still is valid or maybe even two. You know, I'm not making a rule, but I'm just saying it's a guideline because I think one of the big problems is rounds A, B, C, D, E, F, G. I mean, they go on and on. And I know there have been cases when, you know, round H has worked, but if you, if I can, if you allow me, I can tell you a very, very quick joke. And there's a book called the Green Hills of Africa written by Ernest Hemingway. And they're sitting around the fire one night and they're. The white hunters are out shooting lions. And one turns to the other and says, do you think they got one? And he says, one. One shot made. I'm sorry, three shots, maybe two shots. No, I gotta reverse myself. One shot, maybe two shots. Yes, three shots. Heap shit. Which in effect was applying that if you gotta shoot three times, you gotta lie and you probably missed it. So I think that, you know, it acts as a little caution for later rounds. I think, you know, one should be more circumspect about. And we all get tied in and we all wed get fall in love with our companies, our entrepreneurs. But. And it's a hard decision, but I think this is a good time for discipline.
Yeah, maybe. The only thing I'd add is I think the most precious resources is time and in particular the founder's time.
Right.
Like if you're. I mean, it's so. It's so hard. So blood, sweat and tears going into your company, right. I think sometimes you have to have the honest conversation of like, where is this company going? If you've put four years in, where are we going to be in four years? And you know, usually that conversation's not that much of a surprise and you just really need to figure out like, where. Where are you going? And do you want to keep going. So to me that's all usually the ultimate driver.
I want to fix my, my joke that I screwed up one shot neat, two shots, maybe three shots heap shit. I think you get it anyhow and it is true. You know, when you go, if you have one round and that's all you have to invest, you can be sure that company is going to be some form of winner. And I'm not saying you need two or three, but it does help you discipline yourself.
Jess, has your bar gone up in this environment?
I don't think the bar has changed. I think prices have come down basically. But the bar I think is still the same. We're still looking for outlier founders, enormous markets or potential markets and a lot of hustle and velocity from founders. It's just now there aren't 20 term sheets or like $100 million valuation on a pre product, pre revenue, pre launch company. So I think it's really just that prices have adjusted because the capital has dried up. I mean we just did, you know, we're still definitely open for business. Did an investment a precede two weeks ago and we actually just announced our, the launch of Sequoia Arc in the US Sort of our take on a, on an accelerator for Sequoia. But that opened earlier yesterday actually.
Awesome. Yeah, I heard an analogy. It's kind of been a moving target. But the $20 million A, you know, which is standard dilution of 20% kind of 100 post is now, you know, the 13 million dollar A. Right. So like the 100 million post kind of has gotten compressed to kind of 60, 65 post. Let's see where, let's see where it ends up. But yeah, to your point, prices are coming down.
One of the things that happens is, and I don't want to say it's definitely happening now, but entrepreneurs tend to, to have obviously a very positive outlook. They wouldn't be doing that. And they look around and they see what people raised money at last year and they are still, my experience has always been in a bad time, they are kind of hung up on a previous plateau and it takes a while till they emotionally get accepted. The fact that if they started out to raise at 100 million, then as you said, it's a 60 million valuation. It's not an easy adjustment and they need time to absorb that and live with it. And so when the market declines, the ipo, the stock market declines, you don't automatically see private deals adjust to it overnight. It takes a while and I think we're going through that period of adjustment right now to getting used to the fact that the whole level set may be lower.
Dennis, founding businesses now, how are you. How are you adjusting to this, to the, you know, to the new level set?
Yeah, you have to adjust both the projects I'm working on, Street FC and Living Cities. Like, we've, we've successfully raised capital, so we've got enough to keep us going. Like, there is a conversation about, hey, do you want to, you know, should we consider raising more just to get us through the next two years?
Right.
You can give yourself 18 months, Runway, but do you really want to give yourselves, like, you know, 24.
A little bit more?
But I feel pretty fortunate that we were able to button both of those up. But it was still, it was happening during the time when things were kind of winding down a little bit. And it kind of goes back to the point that, like, hey, we're a pretty good team and we've got a pretty good story. And, you know, I think we were, you know, for both projects, we're examples of those companies that like, oh, yeah, this thing has a good chance of succeeding. Let's invest in it. I think the thing that's totally different and I think both Jess and Alan were hinting at it, is the talent market is just totally different. Right. Before you go talk to someone, like, there's no way I'm going to leave my gig at Google. And then I'm like, well, now there's a hiring freeze and I don't know what's going to happen. And even if I was looking, I'm not going to get six job offers. And you guys are pretty early and you have enough money. So, yeah, this is a good path for me to take. Just able to have a different type of conversation with a different level of seriousness that we maybe weren't able to have six months ago, eight months ago with some of the same people.
Very interesting. Yeah. And even like the Unicorns and Decacorns with a lot of folks that have their options kind of underwater now, right?
Yeah, yeah, yeah, of course.
Especially what's happened kind of last year, you know, with. With like these insane financings. So I think that talent is like, kind of feels like they're ready to go.
Also, a lot of people were pretty crypto rich, you know, six months ago that aren't so much now. Like, maybe I should go get a different cake. Maybe this, maybe this isn't the nest egg I needed it to be.
You know, you mentioned something interesting. 18, 24 months, Runway. At ENIAC, we're kind of trying to have our portfolio minimum 24 months, if possible. That means going back to, you know, even reopening the last round and adding cash to it. What other things, and this is kind of open question for the panel. What other things should founders be mindful of in this time besides Runway?
What are you spending on and how quickly are you spending it on things? I think when capital is easy to get, you're less mindful of it. And then when it's like, hey, we gotta make this stretch a little bit longer, maybe we shouldn't do this on site. Maybe we don't need to go to this conference. Just things here and there. And also just being mindful of, okay, we've got a team of X amount of people. We're not gonna double that. We're gonna make it go with a couple more people, but not double that. Right. And just kind of being realistic about the hiring expectations.
Times like this, you get more efficiency out of the employees you've got. That's for sure. And it's also in times like this that if you're selling a soft product or service that is not necessary. I mean, like, I hate to say it because I believe in the. In it. But if you're in the PR business or marketing services, it's so easy to cut that, and it's so easy to cut your ad spend, even though it may hurt you and it may. May be the wrong. But it's. You reach for those kind of things and it's more short range than long range thinking.
I also think you have to pay really careful to pay very close attention to the mindset of your customers. Like your consumer company. All your customers suddenly feel probably poorer going through what looks like. Looks like it might be a recession. And then on the enterprise side, budgets are getting cut, you know, your friends are being laid off. And so I. The customer mindset's also shifting towards, like, less of the. Like, you don't want to be a company that learns six months later that you were in the nice to have category all along. Like, do you need to shift your product positioning to be a little bit more about efficiency or cost savings? Do you need to, like, brand a little bit differently? I think it's. It's going to hit consumer more quickly. It'll show up right away, but I think in enterprise, it's going to take a while to trickle down.
Yeah, that. Those are incredible takeaways.
Neil. Dennis wanted to come in.
Oh, I was waving at my kids. Sorry. Trying to hide up here. And I see them in the window.
Like, hey, I'm alive. Dennis, don't try that at Sotheby's or Christie's. You'll find out you bought it.
That's hilarious. But yeah, Runway spanned. Discipline your customers. It's interesting, right? A lot of the B2B SaaS revenue forecasts now are seemingly being affected because they're selling to other SaaS companies. Right. That are also that are cutting spend. So it's kind of like, okay, maybe time to reforecast. Maybe look to.
I'll give you a suggestion, not the everyday suggestion. I think this is a very good time to get out of your seat, in your chair, in your house and go meet your customers. Actually do some visits in person and get a sense of what is happening at the customer level rather than try to interpret over zoom. It has a different dynamic. I know it's a lot of extra work, but you can pull a lot of market information by, you know, visiting the customer.
I love that. Yeah, that double clicks on what Jess said about kind of really getting to, to know your customers. Like, like, like, you know, kind of re invent that relationship as, as times are changing. Well, guys, we are at time. This has been a really action packed and very informative panel. Again, really appreciate all of your experience. You know, like I said, I think I posted in the chat out, I was very nervous getting up here because you guys are legends and friends and really appreciate your time in the middle of the week, in the middle of a bear market. And I'm hopeful that a lot of these nuggets folks will take away with and inspire them to build better companies. During this time, you can reach out to any of these incredible folks, Dennis, Allen and Jess on Twitter. They're all active and that's probably the best way to get in touch with them. And you can reach us at Twitter as well at eniacvc or Nahal Mehta. And thanks to Anthony and Nadal for putting this panel together and have a great rest of the week and a great holiday weekend, everybody.
Thanks for having us. Thanks for coming.
Thanks.
Super fun.
Bye.
More from Jess
Sequoia Partner & CPO Jess Lee: What Great Founders Do Early and How AI Will Change Consumer Apps
Sequoia's Dannie Herzberg and Jess Lee on Building an Enduring Firm | Upfront Summit 2022
How Do I Exit and What Happens Next with Justin Kan, Jess Lee and Mike Marquez
Creating B2B2C Marketplaces Lessons from Wonolo - Jess Lee, Sequoia; Yong Kim, Wonolo
"Lessons Learned in My Startup Journey" at Founders Embassy's Borderless Summit 2018