How the Rich Use Multifamily to Avoid Paying Taxes (Full Strategy)
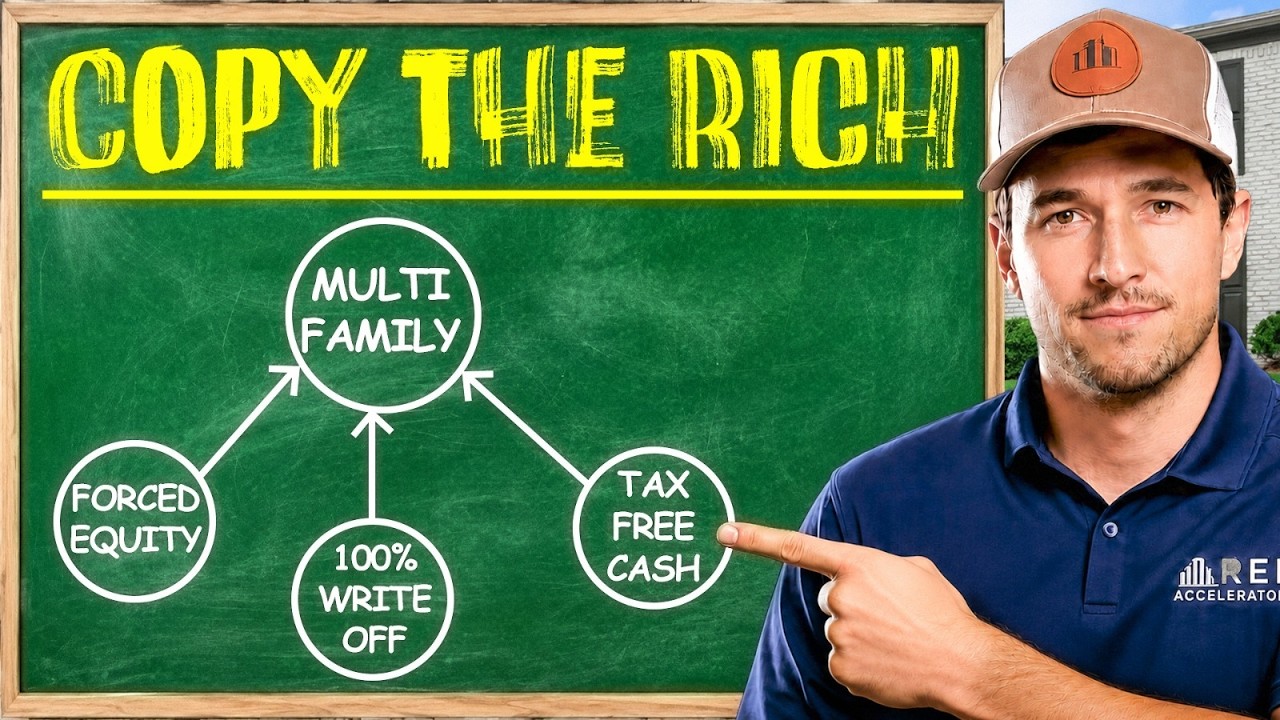
Jonathan Cronin shows how real-estate investors use multifamily properties to defer or avoid taxes. He walks through forced appreciation (an 88-unit building bought for $4M, valued at $7M), tax-free equity extraction via refinancing or 1031 exchanges, and cost-segregation studies that can write off 100% of assets in year one, creating $1.5M in tax shields.
Chapters
So how do the rich use multifamily to avoid paying taxes? So look, you probably heard about all the cash flow side of multifamily, being able to scale multiple units instead of one by one single family, right? But one of the most rarely talked about benefits, one that most people don't talk about, and honestly, the one that the rich care about the most, is that multifamily, what it does for your tax bill. There are strategies inside of the tax code that legally allow you to pay less in taxes and most high-income earners never even know they exist, or most of them don't know about the full benefits. All right, my name is Jonathan Cronin. Together with my partners, we've built about a $550 million real estate portfolio and climbing, and we've been able to help thousands of high-income earners just like you get into multifamily and start keeping more of what they make. So whether you're looking to passively invest and just put money somewhere and not worry about it, or whether you're looking to actually get in the full benefits as a sponsor or as an operator, this video is going to for you. All right, guys, so there's 3 key strategies I'm going to walk you through on exactly how to multiply your wealth, compound it tax-free. All right, completely tax-free. We're going to walk through that. The foundation of the whole process is how are multifamily values created, tax-free multiplication, and then the third step is bonus depreciation. Everybody loves that word, and you're going to love it too once you understand it. So whether you're trying to protect your capital right now, make it more efficient, and, and not use so much of it in properties and raise capital from investors, allow other people to get in the properties and still get your tax incentives. We're going to talk about exactly how to do that. So let's start with step number 1, multifamily values. How do we even assess a multifamily value? How is it created? Well, I'm gonna share an example. So we have an 88-unit property right now that we purchased for $4 million about 2 or 3 years ago, which is cool because 2 or 3 years ago was when a lot of people were making bad decisions, buying a lot of property, and now they got stuck. All right. So they're coming up for their debts maturing and all kinds of different things. I'm gonna show you how we avoided that. But the way these things are valued is you take the NOI, the net operating income. All right. So your income minus your expenses gives you your NOI or your profit on the property. All right. Before debt, before CapEx, you have the NOI. And then what an appraiser does or what someone does to value that property is they take the NOI divided by a cap rate, a market cap rate. All right. And that cap rate for this property is 6.5%. What happens is you take your NOI divided by your cap rate and that gives you the value of the property. All right. So the beautiful thing about that is that cap rate is determined not only by deals that have sold in the past and what they sold for, but also how much your income is. Right. So if I were to be able to create more income, so decrease expenses or increase rents, increase income, I get a higher value for my property. And so that's exactly what happened with this 88-unit. We were able to increase the income by $185 per unit per month. And the way we did that was many different things. We buy what's called forced appreciation. That's our strategy is we look at other properties in the area. We say, okay, market rents are here, we're down here. What do we got to do to the property? Increase the value, increase the quality of life to the tenants. Make them feel like the property is improving. And then we increase the rents to the market value where the other apartment complexes are currently charging for an asset that stabilized like we're going to get it. Okay. So the other way we did it was we increased efficiency of the property, decreasing expenses. So we changed out management, made the property run better. And so that gave us $185 per unit per month. All right. So if you do the math, $185 times 88 units times 12 months, that gives you an equity increase and then you divide that by the cap rate, 6.5%. That gives you $3 million in equity creation. All right. So this is why people love multifamily. Equity creation was $3 million. All right. Now, we did go under contract just recently to sell the property for $7 million, bought it for $4 million. And now 2 to 3 years later, we are under contract to sell for $7 $1.2 million. Now I'm going to walk you through two different strategies here because you can sell the property and still move that money tax-free, or you can refinance the property, which is actually our preferred way, our preferred method. But in this situation, it made more sense to sell. But if you, if you look at the math, we're going to end up paying off our investors about $1.5 million. So about $1.2 million is what they put in it for the down payment to help us buy the property.. And then on top of that, about $300,000 is what their equity growth created. So they're able to actually make a lot more money. Plus they were getting preferred returns every year. So they walked away really well and we're doing the same. We're $1.5 million after you subtract the $3 million is what we now have in equity and what we have to roll over into the next property or do the next deal. Okay, so or you can take it if you want to pay some taxes on it. Right. But that's not what you're here for. Refinance. Okay. So if we were to take this property now and refinance it, the value is $7 million. 80% is what the bank is going to give us on a loan. Right. Because when you refinance, you're essentially just putting a new loan, you're paying off the old loan and you're getting ideally better interest rates. You're getting agency debt, you know, stabilized debt, stuff like that. So it's a lower interest rate. And so what they're going to do is they're going to give us 80% of the value of the property. So they're going to give us $5.6 million. And what that means now is we got to pay off the debt and we're going to pay off the investors. And then what we're going to do is take the leftover and go to the next step. But $5.6 million, the bank is going to give us on this property minus your $1.5 million paid to the investors, minus $3.3 million in debt. Again, this is rough numbers. You have to check out the video where we actually break down the exact numbers.. That'll help you guys. But that gives us a total of $800,000 that we now have and we still own the property. So in other words, cash flow is about $30K a month, give or take, $30,000 a month. Plus we just took out $800,000. Our acquisition fee, the fee that you typically charge in a syndication to be able to buy the property, fix it up, all that kind of stuff that goes to the general partners, which is you. Right? If you're going to buy this property and then that's $120,000 that we pay ourselves for that. And then your net worth, this is what's exciting. Your net worth now went up because you have equity in this property on top of the debt, right? You have equity that the bank wouldn't give you, right? That equity, you now have $1.4 million added to your net worth. And again, this is something you can do with $0 out of pocket if you want. Now, I mean, this is something you can absolutely up to your discretion. We like to put our own money in our own deals because we love it. But we've also raised 100% of the equity. And typically we have so many investors that want to invest with us that we do put ourselves last and we'll end up raising the entire equity amount, the down payment amount needed just from our investors. So, but this is absolutely done. In fact, a lot of our clients and people that we work with, they do it with $0 out of pocket and they do very well. And that's a great strategy. Okay, so now we're going to move on to step number 2. How do we actually take that money, that $800,000, if we were going to refinance, how do we take that $800,000 and actually put it, multiply it tax-free? Okay, well, first off, $800,000, the reason it's tax-free is because it's debt. All right. The bank gave us that money, so we're not paying taxes on it. We're paying what is considered debt. All right. So if you were to sell the property like we're doing, we're going to immediately use a 1031 exchange. All right, so you need— I've got a video on how to do 1031 exchanges. But if you're selling something and you want to roll that money tax-free, you just do that strategy right there, which gives you a timeline of— I believe it's around 180 days to identify and buy a new property. And then you get a qualified intermediary to come in and monitor the process. They hold the money and you move it into the next deal. Okay, so right now we have a 90-unit deal in Atlanta, Georgia, where we are paying $7.2 million for this property. Now you say, dang, you know, you got a 90-unit for $7.2, but an 88-unit for $4 million. Well, first off, it's in a better— it's in a nice area. It's worth it. Okay, so the rents are way higher than probably double. So we're getting this deal actually at a steal. There were people who put in offers at $9 and $10 million, which, by the way, this whole process, buying an 88-unit deal 2 or 3 years ago and then buying a 90-unit deal, you can absolutely do this whole process in just 2 to 3 years. And that same year we bought the 88-unit, we can buy more units. Same to this year, we're buying more deals. So all of this compounds as you just give focus and time to this investment. Now, if you're a limited partner or somebody who says, I just want to place money somewhere and I just want to see it tax-free, okay, well, we're going to talk about that as well. But this 90-unit deal, $7.2 million, the seller actually is all in on this property for 13 $1.8 million. The seller's taking a $6.6 million loss on this deal because he was in the same situation I was talking about earlier where the debt is coming mature and he just can't make it work financially because the interest rates spiked. Okay, so your down payment on a $7.2 million deal, I believe we're actually going to be all in about $8.5 after we budget closing costs, renovations, all that kind of stuff. Our down payment, what we're going to do, it's going to be about $2.7, $2.8 million. We're going to take that $800,000. And if you want, you can move it as a down payment into the next deal. All right. And then you can raise the other $2 million to come up with the full down payment. All right. Or you can save that $800,000. You can use it for random costs like your closing costs. You can use it for building your business, hiring people, whatever you want to do. You can take that and move it tax-free. Free into building your business or whatever you want to do. And then you can just raise the rest of the money. But for this, say, let's just say $800,000 plus your $2 million. All right. Now what we're going to do in the future, in the next couple of years, we're going to increase the equity by $3 million, just give or take. All right. We have a full breakdown of this deal as well that you can check out and it'll show you exactly our plan as far as forced appreciation. We're decreasing expenses big time on this property and then cash flow. So Now we take our $30,000 cash flow that we were making on this other deal and we're going to bump it up within 2 years to be $80,000. Once we actually get this property stabilized, we're going to be able to cash flow $80,000 per month. All right. So this is how wealth is built tax-free. And again, you can come in with $0 and you're able to do this fairly quickly. So then acquisition fee on this property, $150K. So that's $300,000 or $270,000 there. So that's how you build wealth. You compound and multiply. Okay. Tax-free. Now, the last strategy, bonus depreciation. Let's talk about it, because what's going to happen with this property now that we have this 90-unit deal, it's closing here in a couple of weeks. We are going to do what's called a cost segregation study on it. And this is what is amazing. You know, Trump just rolled out the big beautiful bill, I believe last year. And what that means is that we can now take depreciation losses, things that would typically be wrote off on your taxes on 5, 10, 15-year schedules, right? Things like your light fixtures, different, different things in the property that you would actually go and examine carpets and things like that that depreciate and you get the tax benefits from it over 5, 10, 15 years.. And now you can take all those things and bunch it up into year 1. All right. So that's what the big beautiful bill and the cost segregation study, the bonus depreciation means. It used to be, you know, 40% you could depreciate in year 1. Now it's 100% you could depreciate year 1. So what that math actually looks like is in year 1, we can take, just say, a $7.2 million deal. We can take just say 20% as a rough estimate. You know, again, that's going to be based on the cost seg study. And the bigger the deal, the better. But, you know, right here you're going to be able to take $1.5 million and split that up over your other investors or whoever you have on the deal. I've seen deals work out. It just— it's based on how you structure the deal. But you can put that $1.5 million all to you or you can put it all to the investors., or you can split it up evenly. You can kind of do what you want. It's a beautiful thing about real estate. It's your deal. You can do what you want. But now what's cool is that $1.5 million can become a tax incentive for your income. You have to be a professional real estate investor. So I think what that means— again, I'm not a CPA. You need to have a good CPA for all of this. But that would essentially mean that you spend a lot of time per year. I forget how much exactly it is you have to spend on real estate. But as long as that's a significant portion of your time, you can take those losses, take the bonus depreciation, and actually put it on your active income. So you can go from— this is technically passive income losses. You can take that and put it on your active income. Again, get a good CPA. And then also, if you have a good CPA, you can even roll that over. Say you only needed $300,000 of tax incentives. You can roll that over into years to come. And that's why most multifamily investors don't pay taxes, and that's exactly how you can do it as well. Look, I hope this helps you. If you are right now looking at trying to roll over taxes or trying to roll over properties into tax-free vehicles, let us know in the comments. If you have any questions about this, put it in the comments. If there's any videos you want us to make, let us know. We'd love to make it for you. And make sure to like and subscribe. And look forward to seeing you next time. God bless.
More from Jonathan




NEVER Buy an Apartment Building Without Checking These 5 Things (I'm a Real Estate Attorney)





