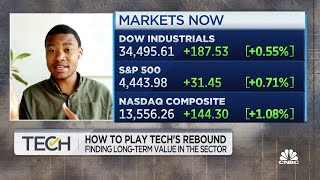
Interview segment with Kanye Maqubela (Kindred Ventures) discussing macroeconomic effects—notably inflation and interest-rate hikes—on tech funding and valuations. He notes a sharp Q1 funding slowdown and falling prices since the market peak, but argues that high-quality software with strong growth and margins remains attractive; allocation must be selective. The discussion contrasts enterprise software resilience with consumer-facing hardware risks (supply-chain and demand softness).
Kanye, good to have you back. Thanks for helping us start off the hour. So many cross currents right? You got rates and the trajectory of rates. What's going to happen there? There seems to be some softness in tech at the consumer end. Others argue that's going to be made up for by stronger IT spending and the enterprise. How do you process all of this?
First of all, it's good to see you and happy one year anniversary on Tech Check. Congratulations on a great year. The most important thing to start really think is inflation. So the CPI print today seems like the market has react well too because I think it was a point 5% expectation it was only point 3% but these are huge numbers. We're looking at inflation at the, at the level of 8.2% and this is across multiple categories. And so we are really moving into an unprecedented era. And all these rate hikes that you were talking about in the previous segment are really going to start to have a big impact on investors comfort in being tied up in stock like the liquids and privates in particular. That said, I want to put some things into context. Q1 the funding slowdown was huge. The mega round was down 30%. Q1 was down 19% from the previous quarter just in tech. And since the top of the market, which is probably November, prices have dropped hugely. But growth is still there and the margins are still there. If you just look at the natic emerging cloud, growth rates since November are still north of 40% and margins are still north of 70% and so there still is an opportunity for growth but you do have to be hyper selective as you know about which sectors you're going to be allocating into. And we have a strong view that software, but not just software, but there's high quality software which mixes growth and profitability, which makes it margin and then certain sectors where there's actually real particular interest for us.
Where does that leave your interest on hardware given potential consumer softness and obviously production issues in Asia?
Hardware is interesting and again it's one of those things where you have to look one level deeper. And we actually have an investment in a number of hardware companies where we think that the services side of the harbor businesses are really, really interesting and important but supply chains are going to be challenging. And so when we're thinking about where there's going to be some pressure, the supply chains are continually going to be pressured. And you see what happens in Shanghai, see what's happening in China with the lockdowns from COVID and that's actually going to have an impact that's downstream from us still. We haven't yet priced that in, so that's where there's going to be some challenge. But on the positive side of the ledger, cy fintech vertical SaaS, you still see an opportunity for trading multiples there that are going to be very healthy on the basis of the growth, which again has been really high as compared to the S and P and even as compared to the greater nasdaq. Okay, so Kanye, if you're looking at collaboration tools, if you're looking at fintech, maybe if you're looking at multi cloud management within software, particularly enterprise, where are you most excited? I'm most excited about a couple of areas. Fintech has been amazing in the last quarter. It was actually a record M and a quarter for Fintech. There's just been so much consolidation, but there continues to be a huge amount of real interesting innovation that's happening. The neobank rise has been totally amazing. The intersection with crypto and so the defi fintech intersection is proving to be a really important story for this year. Cybersecurity is another one that's really interesting. Obviously layering in what's happening in Europe, there's going to be increased scrutiny. Many of companies that don't have strong cybersecurity. And in terms of vertical SaaS, we're still in a 20 year bull cycle of integrating software into the enterprise and that continues to be a great. You just have to be very selective to optimize for companies who have margin structure.