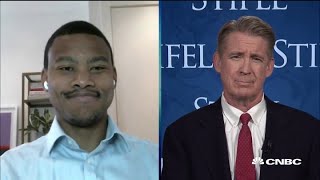
Panel discussion (YouTube, June 2020 excerpt) exploring market effects of COVID-19. Kanyi Maqubela (venture investor) describes a sectoral bifurcation—winners tied to digitization (supply chain/logistics, fintech, digital health) and losers in consumer-facing industries (retail, hospitality, travel)—and argues early-stage VC sees increased innovation while late-stage faces valuation compression. Barry Bannister (analyst) emphasizes consumer-demand risks, weaker GDP, and that recent market gains (large run-up from March) may consolidate; election/tax-policy risks are raised near the end.
Chapters
Kanye, I want to start a bit broader because we talk about the markets themselves a lot. But for a venture investor, what is happening right now kind of in aftershocks of the market volatility, the dip we had some of the economic displacement and the pandemic effects. Are you seeing startups shutting down, running out of cash, or are they holding on?
The funny thing about this is that it totally depends on the sector. And so what you're starting to see is a pretty noted bifurcation between those stocks that are starting to see really strong performance. For example, in the supply chain, logistics sector, financial technology, digital health and wellness. But on the other side, you're seeing a sharp dip in consumer demand coming from retail, hospitality, travel industry. So the interesting thing about COVID and the lockdown is it's actually created a bifurcation driven by digitization in the lockdown as much as the economic impact on the economy.
Barry, does that translate into equity strategy betting on not just the overall markets where we are now, but more based on industries or specific stocks?
Well, one of the factors has been the coronavirus, which is just rolling from northern latitudes to southern latitudes and also from the northern hemisphere to the southern hemisphere recently. It will impair person to person businesses in terms of confidence and that will affect back half gdp gdp. And you've got to consider that person to person businesses, this would have been all of the job growth in the last 10 years. So people are going to suffer for this, unfortunately. So that plus the fact that we came very far very fast from March 23rd to July, excuse me, June 8th, I think we were up 45%. Nasdaq and S& P. We're just going to consolidate here for a while. That's our view.
There's so much uncertainty right now and with the recent uptick in coronavirus cases in this question across the country of whether or not the reopening should continue or maybe should be even pulled back. How does that impact your outlook both near term and over the next year?
In terms of me, I think the, the issue for us is just the outlook on the the states that are affected is that people are more cautious. You know, this happens naturally. It doesn't require a government man. And as people pull back, you'll see less on the consumer side. Business won't respond with capital spending. GDP estimates will be weaker than expected. And a weaker recovery is not something that was discounted in the market when it ran up 45% in two and a half months.
From the venture, for your perspective, sorry, go ahead.
Yeah, sure. From the venture standpoint, it's a little bit different, especially at the early stage. So economic dislocation forces innovation. And so if somebody gets laid off from the economy and decides that it's time to start a passion project, working from home is jumpstarting a number of new companies and there's more demand for at home content creation. So actually at the early stage, we're of the belief that disruption creates change, which requires innovation, and it's a very valuable time to be in the very early stage of the business. That said, at the late stage you are going to see some of the valuation compression as consumer demand inevitably dips. And one of the interesting things to note about the late stage of the private markets in terms of valuations is that you have seen year to date a modest inflation of valuation multiples. But Nasdaq is up year to date. There may in fact still be some value in our corner of the market compared to the equity.
A. Barry, one of your recent notes calling for 3,100 at year end cited shifting election trends. Some of the polls bear that out this week, which you said threaten the tax cuts. Gary Cohn's being quoted this morning saying he'd be okay with the corporate tax rate going back to 28. Do you think those concerns are going to start to get discounted more in the market?
Well, Cohen served in the administration and probably got some tax breaks for being a government official. I mean, I think for the rest of us, having a 10% hit to S and P profits due to the tax rate reverting back to 28% would be a negative. It's not something we would particularly like at a time when capital spending is weak and consumers are skittish. So no, I disagree with Gary on that completely.