Institutions SECRET To Making MILLIONS Trading🚨
9 Sept 2026 · 1 min
0:55
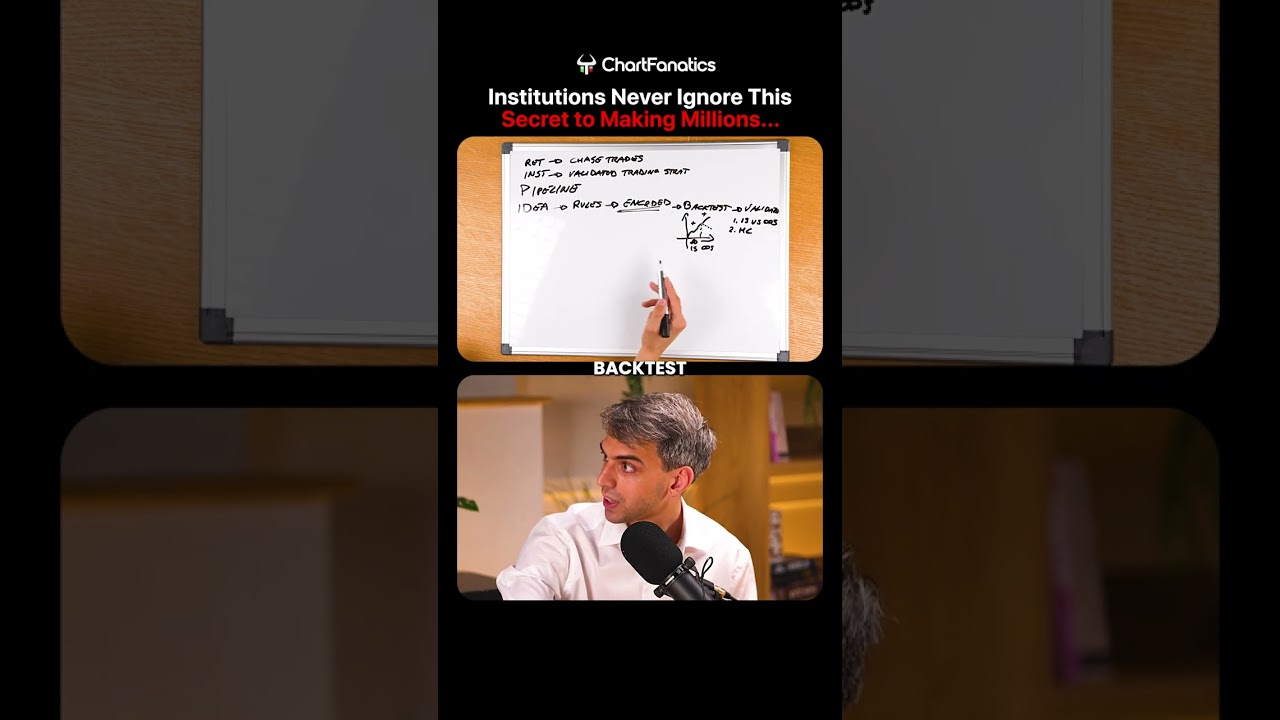
In this segment, the speaker outlines the two‑phase validation process essential for institutional trading strategies. First, the data is divided into in‑sample and out‑of‑sample sets: the in‑sample set is used to develop and fine‑tune rules, while the out‑of‑sample set tests those rules on unseen data to detect over‑fitting and gauge real‑world viability. Second, a Monte Carlo analysis is performed by reshuffling the order of all back‑tested trades thousands of times. The dispersion of resulting equity curves indicates the strength of the strategy’s edge—tight distributions suggest a robust edge likely to perform live, whereas wide dispersion signals a weak, unreliable edge.









