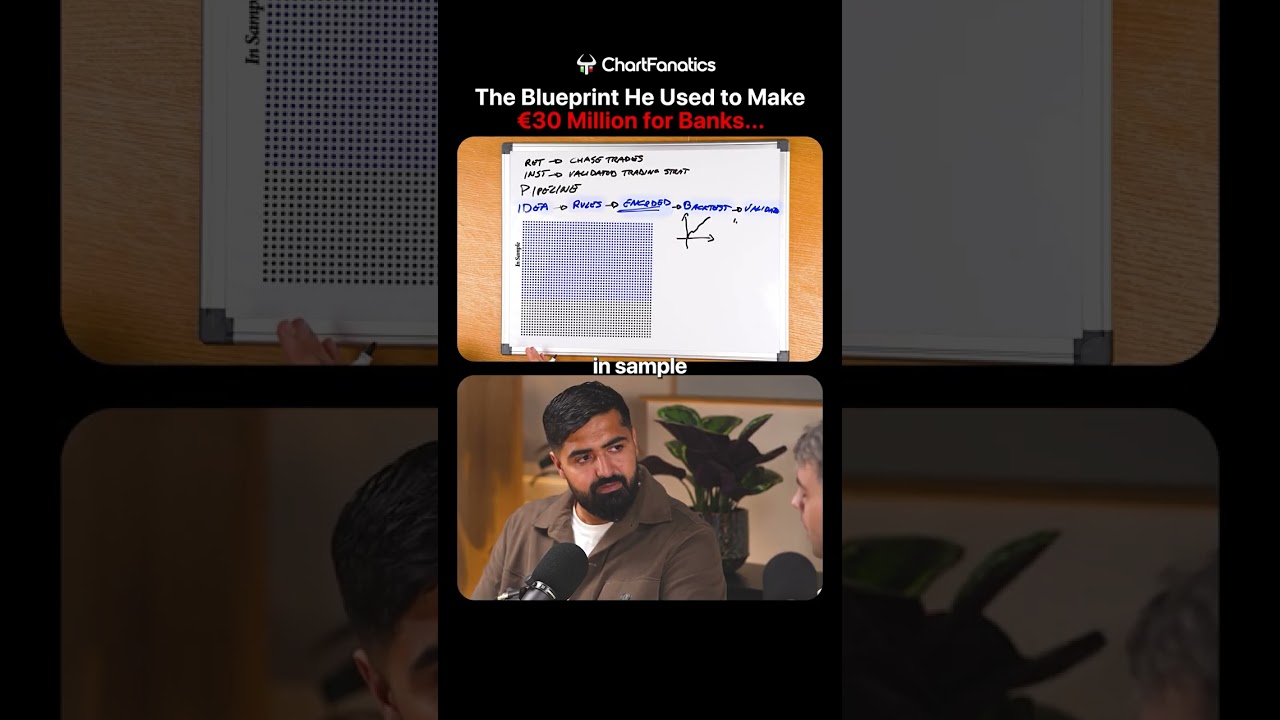
A trader who made €30 million for a bank walks through how institutional traders build strategies: code the idea, backtest it, split data into in-sample and out-of-sample sets to catch overfitting, then run Monte Carlo analysis by reshuffling trades thousands of times to test if the edge is real.
Chapters
I made more than €30 million for the bank. And this is the pipeline that every single institutional trader follows. And this pipeline starts from getting the idea, defining a set of rules, encode it, leveraging the power of your ChatGPT, and then backtest. You translated it into a piece of code to just replay history. And this one is going to give you one single equity curve. Then we need to validate. And usually it's divided in 2 phases. One is splitting your data between in-sample and out-of-sample. In sample data is where you're going to work on your rules, adding, removing parameters, fine-tuning the parameters until you find a strategy that looks like it's behaving correctly in sample. And afterwards, feed the same rules to unseen data. If your strategy is still performing good, it means that you didn't overfit and there is a high chance that your strategy will work well with live data. And the second step is Monte Carlo analysis, just taking all the trades of your backtest, reshuffling the order of the trades, and then you repeat this process thousands of times. The bigger is the dispersion from the top equity line to the bottom, the weaker is your edge. And once all of these steps are completed, only at that point we reach the final phase, which is live trading.