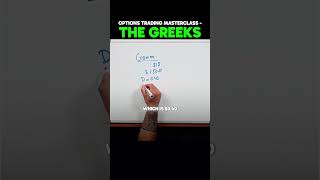
Kardec Trader walks through how Delta and Gamma affect option prices as stocks move. Starting with a stock at $18 with a $1.50 premium and 0.40 Delta, he shows what happens to your profit when the stock hits $19 and $20, and why implied volatility matters for trading.
Questions this video answers
$0.13
$0.40
$1.50
$18
Chapters
Gamma and implied volatility. These are two things you need to understand how to catch those crazy moves. The job of Gamma is that it gives us a number. So let's say 10 cents and the delta is 40 cents. It tells us that rate of change of Delta if $1 move happens. Let's say the stock is trading at $18 and the premiums are $1.50. And we have the Delta which is $0.40. Gamma is $0.13. Stock price DOL we have $19 and then we have $20. So right here going from 18 to 19, premiums are $1.50. Right. So when it goes from 18 to 19, we're going to add $0.40. So the new price is going to be $1.90. Now when this happens, the new Delta is going to be 40 plus 13, which means it's going to be $0.53. So when it goes from $19 to $20 here it was $0.40 here. Now it's going to be 53 cents. So which means from one do the new cost is going to be $2.43. So this gives us an idea of how much we're looking to walk out of the trade. If it makes two dollar move.