Balance Sheet Deep Dive for Real Estate
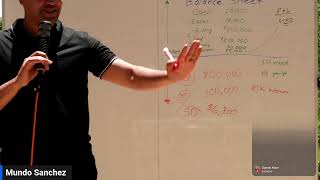
A solo breakdown of real estate balance sheets covering DSCR loans, closing costs, escrow accounts, and amortization. Learn how loan structures and financial details actually work when you're managing property investments.
What is up, everybody? I am here live in Pigeon Forge, Tennessee. So I'm at one of the properties about recently with a couple business partners. I don't know if you can see the mountains in the background. You should be able to see them. But man, what a beautiful view. So we are actually here where I'm here with my family this weekend setting this property up, doing some cleanup. It had just gotten painted, so furniture is just all over the place.
Right.
So come down here and actually all the outlet covers are all off. So that's fun. I didn't realize how many outlet covers are actually in this house. So that's taken a couple hours. I'm probably like 80 done with that. Just getting things situated, getting in order. I just finished a podcast. I did the podcast here on this deck. We are actually tearing down this whole deck. You can't even really see. Well, you can see one of the posts here. We're tearing down this whole deck and redoing it. So that was actually an unexpected thing that came up on this property. So it's a three story deck and we pretty much tore it down just down to that foundational level and rebuilding it. And we actually had the Pigeon Forge police department come out and issue a stop order. And we had to get a permit. So we didn't even know that this deck didn't have a permit originally from whatever, you know, whoever built it right from a prior owner. And we didn't think we needed a permit because we were just doing an improvement to an existing fixture. But apparently we needed a permit so we had to stop. Everything we're doing took about three or four weeks. Now that we got a permit, we're going to be doing this. We're going to be rebuilding this next week from our contractor. And I just get to enjoy the beautiful view. It's way prettier on the second and third level. And so what we're actually doing with this property is we're turning it into a corporate retreat. And it's also a place where investors, whether that be, you know, owner club members that are looking to host their own workshops, that's what this place is going to be catered. And this is something that I've been wanting to do for probably four or five years. Well, actually, let me take that back. It's actually something I've been wanting to do for, I'd say the probably past year and a half in my head. I wasn't going to be able to achieve that in four or five years from now. So this property the way that I won't get into, you know, the reason why we're doing it. But I had some mindset issues around that. It was like, oh, you know, my brand isn't big enough.
Right.
I'm not at that level of success where I can, you know, host work, workshops and doing that kind of stuff.
Right.
So I'm pushing past that mindset issue, and we're doing it right. So I'm going to be holding a workshop here at this property in Pigeon Forge, Tennessee. You're going to get this beautiful mountain view in. I'm thinking about doing it in, like, the middle of September. So we have a couple more trips here that we're going to be working on this property. And that's the end of my spiel of why I'm here in Pigeon Forge. So today I'm actually going to dive into real estate accounting. So I'm going to do some deep dive, super technical stuff on the balance sheet. There's not a lot of content around this, so I figured I would give some value to people today. And I got my whiteboard here. You can't see it yet, but I'm going to bring that into the picture. But I wanted you to at least get a little peek at this beautiful view in the mountains. And I'm not monitoring the live right now. There's probably no one even watching this, but I don't care. Uh, I can't see the comments because my computer's way back there. But when I transition into things, if you want to leave a comment. Last time I went live, I could not see any comments on Facebook, just so you know. So. But I was seeing all the comments on YouTube. I'm sure there's like, some sort of setting once I become more familiar with how to go live, maybe I'll figure that out. But I know I can see the comments on YouTube. I just can't see them on Facebook. So I'm going to go ahead and dive into real estate accounting. We're going to break it down for you. So I got my whiteboard. I'm going to adjust my camera for a second, and so that way you can kind of see. I'm sorry I took away the view of the mountains, but we're going to dive into balance sheet stuff today. So I'm going to zoom the camera in a little bit. Actually, I'm going to go inside. Be right back. All right, so I got a few seconds of nice cold air, so let's dive in. Let's talk about balance sheet. I'M excited to get into this. So I'm going to talk about. I'm going to go back and forth to my computer just to kind of reference the balance sheet so that way I don't lose my talking points and I want to make sure that I get capture everything. We're going to talk about the balance sheet when you buy properties. So let me just write that in here. I'm writing this so I can test to see if you guys can actually see it on the screen and then we can dive into that. Let me check that out here. Okay. You can kind of see it, but it's zoomed in enough to where I can write and you guys can see it. Perfect. Awesome. So when you guys buy a property. So I'm talking more specifically of getting like a DSCR loan. You know, maybe you're doing a morbi method, or maybe you're just getting a DSCR loan just to get a DSCR loan. And so let's say the purchase price is a million dollars, right? Buy a nice little property like the one we're sitting at right now, it's a million dollars. What's going to happen is, well, if we're being honest, most of you guys are probably just handing your accountant at the end of the year a pile of crap of documents and just saying, here you go, figure this out. And then because you didn't do any document retention or really any prep work whatsoever, your accountant's going to have to sort through all this mess. And you're probably not doing that very timely. You're probably doing it once a year. And then you're wondering why your accountant's sending you like a $6,000 bill. Well, it's because you just handed them a huge amount of work for them to do. So. All right, hold on one second. So let's say you purchase a million dollars, right? So what happens is you have two financials, mainly two financial statements. I won't get into the cash flow statement today, but we're going to talk about the balance sheet. So you have your profit and loss statement. And that's typically what everyone manages in terms of monthly performance, right? Your monthly income, you know, the rent income you're receiving, whether that be LTR or str, and then your expenses, right? So part of your expenses, and this is one thing that a lot of people don't realize is that your mortgage payment, so your piti, right. Not all of that is on your P and L. So in your head as an operator, and this is how I look at it too. As an operator, I'm like really fixated on cash flow. Right. I know my mortgage payment is this with piti, you know, the principal, the interest, the property taxes, the insurance. And I know what my income is and I know what all my other ancillary expenses for property management, maintenance, reserves, any other stuff that I spent money on for the month equals my net cash flow. Right, got it. Pretty easy. Well, from like a financial statement perspective, your PITI is not fully recognized on the profit and loss statement. So what is recognized? The interest expense, the interest portion of your monthly payment. So let's say you have a $5,000 monthly payment, where in this case it's probably more like $6,000. Let's just say it's $6,000. Let's say $5,000 of that is interest. So that is the portion that you will put on your profit and loss statement. It's going to be interest expense.
Right.
The other thousand dollars is going on your balance sheet. So when you record the purchase of your property, this is going to be, you know, we're going to call this, we're going to say actually yeah, let's just. I don't know where the line's going to be, but we're going to say this is our assets line here, right? So we're going to have assets. We're recording this million dollar property that we just bought as an asset, right? So when you record that million dollar property that you just bought, most of the times you're not paying cash, right. You're going to be paying debt a lot of times. Now whether you did a Morbi method or whatever, right? We're going to pretend in this scenario that you did a Morbi method. And when you're buying real estate, you're not just buying the $1 million property and that's it, right? You need to cover a whole lot more than that. You have closing cost that you need to consider, which can be pretty significant closing cost, right. You have loan origination fees. My favorite conversation to have. Well, now it's not even a conversation. I just expect it is when you're getting a DSER loan, your lender says, oh yeah, our origination fee is, you know, 0.5% or 1% or one and a half percent or whatever, right. And then you get to the closing table. Keep in mind, you know, you're really not getting, normally you're not getting a ton of communication as far as financial visuals. Like you may get a basic preliminary term sheet and it may say, hey, origination Fee is this, right? But what they're not telling you is all the other ancillary expenses that start showing up. Oh, we have a underwriting success fee and like what the heck is that? Like to me, origination and success fee, underwriting fee, like whatever you as the lender are charging me, that's loan origination cost to me. You know, that's just how I look at it. So they'll come in as like a loss or like they're trying to differentiate themselves on pricing and tell you it's like, oh, it's 0.5% or 1% or one and a half percent or whatever that number is. But then when you get to the closing table, which by the way, once you're at the closing table it's too late to back out unless you just want to kill the whole deal, right? Because at that point your seller's like ready to rock and roll and if you back out, it's not going to be good, the deal's dead. So they know that they being the lenders, they're going to put that on you as far as leverage. Then you start seeing the documents at closing table. There's all these things, right? You got this underwriting fee. Oh, by the way, we have an in house counsel and we have our attorney look over these documents. We're just going to charge another $2,500 on top of that, don't worry, you know. And by the way, the mortgage document and all the documents they're using, they're repeatable documents as far as like they're literally copying and pasting. They're, all they're doing is like updating the address, updating the name of the borrower, updating, you know, a couple other things. I don't know how long it takes them, maybe 10 minutes. It's probably automated at this point. And they're charging you for the privilege of that for their attorney to review. Now the attorney's obvious, basically doing a lot more. You know, they're going back with back and forth with title, but honestly it's a lot of back and forth with title that they really don't need to be involved. Like it's stuff that's already been hashed out. But the lender has to do that to protect themselves and you know, for all these other reasons they have to market it, you know, after they close they have to market that note and you know, give assurances that they have an attorney review all that stuff to make it more attractive, whatever. But those are all still expenses by the way it is extremely hot. So if you see me sweating, it's because it's, it's pretty high. It's got to be like 95 degrees out here. I did not know that when I went live. So you have a lot of expenses. The other thing that people don't tell you about is when you are using a DSCR lender every single time they're requiring, oh, I just felt some shade. That feels nice. Every single time they are going to require you to prepay at closing. The first one year insurance policy in full at closing. Take a million dollar property, you know, like this though, like the one I'm sitting at, right? The insurance cost was over five grand. So that's five grand right there, boom at closing that you may not have even known about or was planning for. Like that's not an insignificant amount of money, right? Then you have to escrow three months worth of property taxes. Every lender is different. You're going to have to escrow three months, sometimes six months. It just depends on the lender. And then my favorite little surprise, I've only seen a couple lenders do this. Sometimes they'll come back and ask you to pre fund into escrow at closing. Three months worth of mortgage payments. Sometimes I've even seen six and I've had this happen to me. So imagine that surprise when you get to the closing table and they're telling you you need, you know, going back to the payment. We're just, if we're just saying in that example earlier it was $6,000, imagine funding $18,000 plus the $5,000 of prepaid insurance, right, for that policy, plus all these origination fees that you, you know, origination fees that they never told you was included, but now they're real. Plus another one that I love is when they are quoting you the interest rate. They'll tell you, oh well, we got you at an interest rate at 7.5% and depending on who you're talking to, if they're transparent, sometimes they are, sometimes they're not. They won't tell you that in order to get you your seven and a half percent they charged three points. So now you're talking about another thousands and thousands and thousands upon dollars. So you could very well easily be 30k deep in unexpected cost at closing between escrow requirements that the lenders, you know, saying that they need. And the reason why some lenders, Well, I can't think of a logical reason why some lenders will require three months or six months. I do know why Logistically, why they do it is because they close on a loan, they fund it, they turn around and sell that note. And to prevent issues in transition from loan servicers, they want the three months of escrow, mortgage payments sitting in escrow already accounted for. So that way when there's a drop between escrow companies, at least this is why I think the reason is they have the money, right? They handle the applyments of payments and they don't have to worry about like, because they don't do a really good job of like communicating. No one's reaching out to you. You know the guy that most of the times, unless it's someone you have a really good relationship with, most of the times, if you just kind of googled a DSCR lender and found one, like they're not going to call you up and they're not going to be your buddy after closing, like after you close, like they're on to the next one, right? It's a transaction. They're not going to be engaged. You're not going to call them up and be like, hey, I got this problem. They're gonna be like, why are you calling me? Call customer service and wait 17 hours on old, like that's what they're going to tell you. They're not going to tell you the 17 hours part, but I'm going to tell you the 17 hours part because that's reality. And you got, you got all these expenses, right? It's going to be well over $30,000 depending on the loan, right? This is kind of a drastic scenario, more based off of a million dollar property. Obviously if you're buying a $200,000 duplex, it's going to be a lot less. So my point in that being that you're not going to have just $1 million of closing or of funding needs, you're going to have a million one, a million two or whatever. If you structured, depending on how you structure the deal, you know, if you brought a lot of equity, like if you brought a lot of cash to close, obviously your debt is going to be a lot lower, right? Your loan payment is going to end up being like, you know, let's say you put $250,000 of equity in your, your liability is going to be 750,000, right? But if you're doing something like a morbi method, your equity is not going to be that much because you're refinancing your equity out of the property after closing, right? You close and then in a separate refinance transaction you're refinancing the equity out of your property. Right. So again, I'm just making up numbers. These aren't real. I'm just throwing stuff on the wall.
Right.
So let's say you have. Now we're getting down to the liability section. So I'll just write that, write that down. Actually, let's make this red. So we got liabilities here. Hopefully you can see that.
Cool.
Perfect. Let's say we have a loan. I'm going to say first. So when I say first, that means like the first position mortgage. So we're going to say that the loan was for $800,000. Right now we're doing an 80% LTV. Actually, let's make it now. We can leave it there. We can leave it. Actually, no. Actually, yes. Sorry, I'm changing my mind. Usually I don't Recommend Going to 80% LTV is because your interest rate, that's usually the tipping point where your interest rate, like skyrockets, it's going to be so much higher. So, like, usually the lenders would love for you to be lower.
Right.
75% is kind of to peak. When you get to 80%, that's always been like the magic number of, like, increased risk. The lender doesn't want to take on the risk, so they'll do it at 80% LTV, but they're going to jack up the interest rate to the point where you can't cash flow, and it's going to kill the deal.
Right.
So whenever I see these deals posted online of like, yeah, you can, you can take down this property with no money net out of your pocket after a refinance, but you got to get an 80% LTV, 85% LTV. I'm like, yeah, this deal is not going to pencil out. So. But to keep things simple in my head, for this example, we're going to say it's 80%. Just know I don't recommend doing 80%. So we're gonna say that is 800,000 first. Before we go further, I need a water break because it's. It's really hot. Don't worry, I'll keep it quick. Okay, cool. Oh, I didn't even have the comment section pulled up. I'm sorry. Now I have the comment section. So if anyone has any questions, they could definitely ask me and I'll just kind of keep an eye on it as I go. But again, on Facebook, for some reason I can't see the comments, but on YouTube, I can. So hop over to my YouTube shameless plug. You should probably subscribe to my channel and leave a comment there. So we have the $800,000. That's the first position mortgage, right? So if you're doing something like a Morbi method where you've closed on it, you injected equity into the transaction and now you're going into a second transaction. Now, whether that's recorded second position, or if you partnered with a seller, however you want to do it, right. I'm just going to put in here second and I'm going to put, let's say, how should I structure this as an example? I'm going to leave it at $200,000. Actually. No, let's increase this. So I'm going to make this $300,000. So we've at this point, you know, we've leveraged, over leveraged this transaction, right? You know, so this point, you're probably not even getting that much back at closing for like capital reserves because you have all these different things that you have to pay for that. I mentioned previously when I talked about, you know, the loan origination fees, the closing fees, you know, if you paid the agent commission, you got to pay all that stuff, all those expenses that I was talking about a few minutes ago. That's why the transaction is over leveraged, because you're not just buying the property for 1 million, you're buying the property for 1 million plus everything that I just mentioned. So now we have this $1.1 million worth of debt here, right, as far as our liabilities. So let's talk about like recording some of those other. Let me pull up, I'm going to pull up a real balance sheet. You won't be able to see this, but I'm kind of looking at it as my cheat sheet here of one that I recently did. And we'll just kind of walk through some of that stuff. So we have the asset. Oh, I wish I would have drone the asset, that $1 million asset. A little bit lower on the screen so you can see it. That's fine. I'll just, I'll make it work. So when you look at your balance sheet, you're going to have things. This, this really drives me crazy, honestly. Like I would normally have the assets like down here, but I'm not going to erase this. Or actually I am getting it right. I can't stand it. I'm going to erase it.
All right.
Okay, cool. That wasn't too bad. So let me pull out the green for this one because I like assets. Assets are cool. Let's pull green so you have your cash.
Right.
And by the way, if there's any accounting nerds on this call, I'm not going to have this balance sheet actually balanced. Like, there's going to be things missing on this. I know that I'm not going to walk through a full balance sheet reconciliation because I'm only going to be on here for like probably another 15, maybe 20 minutes because I got to go do some stuff with the family. I've been trying to, you know, just do one fun thing, get them out of the house. And then, you know, the rest of the day I'm going to be cleaning up the property. So keep in mind, I'm not going through a full balance sheet reconciliation. I am fully aware it's not going to balance. Okay, so let's say you have cash here, right? But I'm just going to kind of walk through high level what some of those items on your balance sheet look like you're going to have. I don't know, whatever. Whatever you have. Like, let's say you have $25,000. Actually, I'm going to say 20. I'm going to see if I can get as close as I can to realistic numbers as possible. I have $20,000, right. Then I have escrow accounts. So when I was talking and you can. I'm just again, I'm keeping this brief in terms of the naming conventions just for the sake of simple illustration. So this escrow would contain what I would typically do. I think what I did on mine. Let's see what I did. I broke out the escrow for the mortgage payments. So I have one pulled up here where I actually had mortgage payments that I had to pay for three months in advance. So if we take this example and you know, we're just kind of building off the $6,000 monthly payment. Let's just say it's $18,000, right. That we have in escrow. So we classifying that as an asset and we're keeping that recorded as our escrow payments. And the reason why you want to do this, I know most investors, they're probably not going to do this right here, that step whatsoever. I've had so many escrow companies, Celine Finance, not that I'm name dropping, you know, Celine Finance, they suck. Like they are the worst at keeping track of your escrow payments. I've had to fight so many battles. I've wasted so much time getting on the phone with them and making sure that my escrow accounts are right. So many hours. And I'm I still have an active one. Right now they're telling me I have a shortage. And I'm like, no, there's, there's no shortage. I had to like walk them through the whole thing. I recorded a zoom and broke down step by step from day one, from closing and just work through the whole thing and they still can't figure it out. But anyways, this is why I keep meticulous records on the escrow situation. Because I want to know what's happening every month. I want to know next month when, when that loan payment gets made. I want to see that loan payment get, bring, get this balance brought down, right? That's what I want to see. I'm going to move that off the balance sheet or it's going to reduce the numbers on the balance sheet. And then I'm also, you know, on the P. L. As that payment happens, I'm going to expense that as interest expense, you know, that whole loan payment that we were talking about between principal, interest, taxes, insurance, all that stuff. So as the months go on, I'm going to be reducing and clearing out that escrow account because I want to keep a ledger of like, okay, this month, this is what my escrow account looks like. And I'm reconciling that to the mortgage statement to make sure that that is actually happening.
Right?
So that's what I have up there. So another thing that I do after closing and again, I'm completely making these numbers up. You have your assets section, right? So earlier when I had the $1 million. We're going to put. We're going to split this off. I'm making this up. I don't know what it is. Let's just say it's $800,000. We're going to allocate $800,000 of the purchase price to, on the asset side, to buildings. And then what we're also going to do is we're going to create a land account. So this is, you know, these are both, these are still this whole section here where I put assets, right? We're going to put land. So we're going to do $200,000 of land right there. And the reason why we're doing this and how you can find this information, you can go to like your property record card, you know, whatever is recorded for the county, whatever you get on, like your property taxes. There's a property record card that like breaks out what the built with a. The building value is and what the land value is. One second, I can't see Myself anymore because I don't have the screen there. Okay, cool. You're going to be breaking that out according to that sheet, right? So if it says your land value is worth $200,000, that's what you're going to record. And the reason why you're separating that out is because you can't depreciate land. So I'm separating this $1 million purchase between land and building because I can depreciate building. The building value, the portion of the building. And when you go and do a cost segregation, you're going to want to know this information because you're not going to be able to depreciate the land. So that's why I have that split out on the balance sheet. Hopefully that portion makes sense. Let's see. Let me go over here, See what else we got. Yeah. So I got building. I got the land in this property. I had some improvements that I made. I had to. You know. Unfortunately, a furnace broke down, so I had to get a furnace. I capitalized the furnace. So now we're going to talk about deferred financing cost. I re. I'm running out of space here. I should have left more room. I really doubt anyone is doing deferred financing cost. So what I'm doing is actually taking, you know, some of those, like, financing costs, you know, those loan origination fees, like, all the costs associated with the loan. I'm actually taking that and putting that on the balance sheet because that's what, you know, you're supposed to do. Actually, I don't know what other people are doing. I suspect most people are probably expensing all that. I don't know. But I'm putting that. Unfortunately, I would love to expense it, but I'm putting that. I'm just going to call this df. Deferred financing. Deferred financing. You know, I was making a big hoopla about this being so expensive. So let's go ahead and make it expensive. Let's just say it's. I think the number I was throwing around was 30. Oh, my gosh. I just got stung by a bee. Holy cow. We're gonna pretend that didn't happen. But see, it was in the middle of digging into me. I don't know if it fully dug into me. I. I felt like a pinch, and I saw a bee. It looked more like a wasp, honestly. But I don't feel any pain at the moment. Sometimes I don't feel the pain till later. But I think he was, like, getting ready to sink his Teeth into me. He didn't get me yet. He might get me later, but not yet. Okay, so back to this. We got $30,000 of deferred financing cost. So what I'm actually doing is I'm amortizing that over the life of the loan. So it's a 30 year loan. I'm going to be expensing that on my profit and loss statement every month for the life of the loan. And that sounds like a lot of work. It is a lot of work. Honestly, when you first set all this up, like when I first set up the balance sheet for buying a property this way, like with a DSCR loan and all that, I don't know if I really tracked how long it took me. I want to say it probably took me somewhere between six to 10 hours somewhere. That's a wide range. Let's say eight to 10 hours. It was a long. I did it over multiple days. I think I planned on doing it all in one day and realized how much work it was. So it definitely took me like a really good solid four or five hours. And then I did a couple hours here, a couple hours there. So it took me about 8 to 10, we'll say about 8 to 10 hours. It's a lot of work. But once you set it up, it's usually, you know, pretty automated. Like, for example, I use REI Hub for my accounting system now. I'm just in the middle of transitioning. I did a live, a six and a half hour live last week. If you didn't see that, it was on Wednesday night. It's on my YouTube channel under the live section. You can see that I went into a much deeper dive on like how to use REI Hub. But for here, like you said, this $30,000 up, you record that. And then I set up like a reoccurring entry every month. So that way it expenses that portion that I'm allowed to recognize on my profit and loss statement as an expense. So it's not too bad because I'm not physically going in every month and making a manual entry to expense that. So overall, not too bad. And I ran out of space here. So we also have. Let's see. I'll squeeze it in, bro, it is steaming. I'm gonna start talking faster because I'm about to pass out. Plus I'm not sure if that bee is coming back for round two. So prepaid insurance, you know, I mentioned what I think I said it was over like $5,000, right? So we have $5,000 prepaid insurance. Now, whenever we get to the point where we're recognizing that expense monthly, so what I'm doing monthly is that expense, depending on how the, the actually, yeah, that's, that's what I'd be doing. I'd be expensing that monthly. So as the months go on, every month I'm taking what that month, that annual value is divided by 12 and like expensing it. Does that make sense? So I'm reducing that. And every time I'm making this, like, if I just do. If I just pretend right here. Actually, I don't know if you can kind of see off to the side. Hopefully you can. I'm just going to draw a little P L section every month. I'm going to take this $5,000 and I'm going to expensing it. You know, I don't know what that is. 250amonth, whatever. If that math is wrong. Sorry. So I'm going to be expensing that every single month onto my profit and loss statement, recognizing my insurance expense. Hopefully that makes sense. So that kind of wraps up the asset section, if that makes sense. And so what else do I have on the liability side? I'm not going to take the time to add all this up. You know, obviously at the end of the day, you want your assets to equal your liabilities and equity. And that's why, you know, it's called the balance sheet, because it has to balance at the end of the day. But in the interest of time and in the interest of me not getting stung by wasp, we're going to quickly run through this. So we have the liabilities, we have the $800,000 that we talked about as the first position mortgage, then we have the $200,000 that we talked about as far as the second position of whatever we did.
Right.
Makes sense. So now we owe. Here's. You know, how we talked about on the P and L, we're expensing this monthly. So what you're going to do monthly is when you make this monthly payment, that $6,000 monthly payment. Where's my black? I'm not going to get it. What we said as an example, again, I don't have an amortization calculator up right now, but what we said as an example is that 5k was interest and 1k was principal. And so when I keep referencing the $6,000 payment, you know, if we really start adding it up, if your mortgage company or loan servicer requires you to escrow, which in this case we are because that's why we have an escrow account. The property taxes and insurance. Your, your monthly payment is not $6,000. Just so you clear it's going to be a lot higher than that because this is really just. That $6,000 is really just the principal and the interest portion. You also have the taxes, the property taxes. So you got that monthly cost. Then you also have the. Which is in this escrow account. Like, I didn't break all that out, but you, you have that stuff in there, right? Then you're also going to have the. So you got the property taxes, then you got the insurance, which we kind of broke out that a little bit. But you're going to be paying that every single month. So it's not going to be just 6,000, it's going to be higher. But let's just roll with this example. So every month that happens. Let's say next month you're going to have this reduced by $1,000. So now you're looking at 799.99, right?
999, right.
That's going to be your balance next month. And every month it's going to be reduced by $1,000. Now, in reality, in your amortization schedule, you're going to have like a, probably a dynamic principal amount. Like it's not going to be $1,000 every month. But generally speaking, I'm just rounding. Let's just say it's $1,000. So we have $1,000 reducing every month. And then the other $5,000 that we have over here, which makes up your six between principal and interest, that's going to get recorded on your profit and loss statement as interest, expense, water break. I'm cooking. I am cooking. All right, we're going to wrap this up because this was meant to be just a very quick session, so hopefully that makes sense. Every month this is your first position, right? It's going to be reduced. Then you have your second position. Well, that depends on what you've agreed to with the seller or your lender or however you got a second position. If it was the seller and you have some sort of agreement, let's say it's 500 interest only or $1,000 interest only. I'm sorry, not interest only, principal only. Those are gangster deals. You know, you negotiate a deal for 0% interest. That's why everyone wants 0% interest. Seller Finance deals, because every single month, that monthly payment you're making, all thousand dollars is going to go and reduce this balance. So what happens every month when you and this is where the beauty of real estate comes in. When you talk about price or equity, like wealth building, right? You're building wealth, you have a couple things happening. You have the asset side. You know, everyone knows this at a high level, but I'm showing you like the actual math, like loosely, I'm not tying all this out, but I'm showing you pretty much the math over time the asset value is going up, right? Because the property is appreciating. Especially if you're making improvements, the property value is going up. And then at the same time that's going up your liabilities, which is the money that you owe that's going down. So the difference is your generational wealth that you're looking for. So the asset value is going up, the liabilities are going down. You're creating your equity spread, right? You're paying down the month or paying down the debt balance. And even if the property is not appreciating, you are building equity because you're paying down your debt, right? So you're paying down the first position, you're paying down the second position. So if you're paying a thousand dollars a month principal only, next month it's 299. The month after that, 298, 2, 297, 296, 295. And then you know, you look up and one year you got $12,000 of equity. But if it's interest only, oof, that's, that's a tough one. You fast forward one year and guess what this $300,000 balance is in one year from now. 300 freaking thousand dollars. Because you were a knucklehead and didn't negotiate a good deal. So interest only means whatever you're paying. Let's say it's that thousand dollar monthly payment, that thousand dollar monthly payment. Notice how I'm using red still and I'm kind of drawing sideways. That's really bad handwriting. That $1,000 payment you're making every month, it's going to your P L, it's being recorded on your P L, your profit and loss statement, and this is untouched. So a year from now, it's going to be $300,000. But a year from now, in a scenario that you did 0% seller financing, no interest, all principal only payments, it's going to be $12,000 less. So that's the power of structuring good deals, right? So recapping properties, appreciating debts being paid down, regardless of how you're doing it, hopefully something is being Paid down, you're creating equity. And so as that goes down, your equity gets larger. As that goes up, your equity gets even larger.
Right.
Hopefully that makes sense. Okay. And on your as far as other liabilities I want to talk about real quick and this will pretty much wrap up. This will be like the last thing I talk about as far as like basic balance sheet understanding 101. Hopefully this was helpful for some people. Actually do me a favor if this was helpful for you. Like anything I said, please do me a favor, leave a comment down below whether that be Facebook or, or YouTube and just tell me what you learned. Like I'm really curious, tell me where. I also didn't do a good job at breaking this down. Simple enough for you to understand because I want to get better at delivering this value to you. So every time I get feedback, it's just going to make my delivery the next time I speak, next time I do a live or anything like that, just better.
Right.
So last thing I'll talk about. And now there's 20 different scenarios where you could have all these other different like line items on your balance sheet, on your P and L that we're not talking about. We're talking about basic balance sheet 101.
Right.
So then we have security deposits. I'm just going to call that SD that's also a liability. And we're going to say and this only applies if you are buying a property that has existing tenants. If you're buying a property that's unoccupied, then there are no security deposits.
Right.
Because there's no one in there. If you're buying a property that is str, there are no security deposits because no one permanently lives there or lives there like on a, like a reoccurring lease. Like six months, month to month, a year long. Hopefully you're pretty familiar with security deposits. It's usually only long term tenants co living, you know, you'll probably have security deposits there. If you're taking over an existing co living property, you're going to have security deposits. I've seen times where investors forgot about that. And like being on the TC side whenever I used to TC transactions I would see security deposits get missed. Oh wait, what about that? Chasing security deposits after closing does not work. I will tell you a quick story about $7,000 that I lost. It was my first deal that I did when I entered sub 2. We had so many times when this deal was gonna die. I walked away from the table, seller walked away from the table. The agent brought us Back into the deal multiple times. He was over it, I was over it. Like, we were just done. Like, you know, we weren't on good terms. Like, it was getting to the point where it's like, I'm just so over this. Honestly, I probably should have. I'm not going to say I regret it. I. I don't regret anything. Everything, everything that happened, everything that was a mistake is just a learning lesson for your next deal, right? So if I didn't go through that, I wouldn't have recognized in my small brain the importance of certain things. And I'm sharing with you that little piece of wisdom that I got from my mistake. So there were so many back and forth. It got to the point where the seller was putting so much pressure on me that the deal was going to be off the day before closing to get the settlement statement, like, drafted, right? Like, so of course, the settlement statement, you know, comes out like 4:58pm right. Right before title company leaves. And I'm expected to, like, approve this thing in like an hour. And there was just so much pressure put on me that I felt like I didn't have the appropriate time to review things and really think through it. And I actually did a pretty good job reviewing it. One of the things that I caught that was missed was that security deposits were not on there. And it was. I can't remember the. I think I said 6,000 earlier. I think it was actually like $6,800, something like that. This was a couple years ago. And I had reached out to the agent. I'm like, hey, security deposits are not on here. We need to corre that. And I, you know, told the title company that too. They were all copied. And the agent reaches out to me and says, like, let's just worry about this after closing, because if I ask one more thing from the seller, he's walking away and this deal's over. We'll figure it out, I promise. You know, we'll get it done after closing. Guess what didn't happen after closing. We did not figure it out. I got screwed at a $6,800 or whatever that number is because it was not on the hud. Dumb mistake. My fault. My fault only is a learning lesson. So I'm at 6, 800. But the good news is I owe the seller a whole lot more, right? Because it was a seller finance deal. So at the end of the day, am I really overly stressing it? I mean, yeah, I would have really loved to have that $6,800, like, right there at the time of closing, I could have used that. But at the end of the day, I'm just taking it off the note, right? Because I didn't get that. So that's being deducted off the principal balance of the note. At the end of the day, I didn't. At the end of the day, when you look at it, when that note matures, I did not lose money. I did not lose that $6,800, but I did lose the $6,800 in the respective time value of money.
Right?
So I say that being in nice symbolism, I'm gonna put $6,800 for security deposits. So you got to hold those as liabilities, because that's not like actual, like you are going to get the. You're not really going to get the actual cash. What's really going to happen when you're closing is you're going to get a credit. So it's going to reduce the amount of cash you need to bring to close. So you really need to think about that if you have a partner that is helping you fund the deal or whether it's your money, Right? Because you could very easily look at that bottom line and say, okay, this is what I need to fund the deal. Boom, wire sent. Moving on to the next one. Well, you need to keep in mind that this was a $6,800 credit that you got. Like, that's $6,800 at the title company saying, hey, we're giving you a credit, but you need to hold on to that cash because those are. That's real money that needs to be refunded back to your tenants at some point in time.
Right?
So that is an important learning lesson for you to keep in mind. Anyways, so again, if you found value in this, please, please, please drop a comment. Tell me what you learned. Tell me what was confusing about this. I know I kind of am wrapping this up because I am cooking. I don't know if that be's coming back to get me, but hopefully this helps you understand the balance sheet a little more. I guess I would say to wrap things up. Two things have probably happened today from watching this. One, you've gotten more clarity around the balance sheet and how all this stuff works. Or two, I've just confused you 3,000% more. It's one of the two. There's no in between.
Okay.
Well, anyways, guys, I hope you enjoyed this. Again, I'm here in beautiful Pigeon Forge, Tennessee, getting this property ready for some investor workshops. When we have those investor workshops. I'm going to be diving into a lot more detail than just this. Like, everyone will know exactly how things work. I always recommend that if you're going to put money into a deal, you need to know how all the pieces fit together. You don't like that doesn't mean you have to wear all the hats and do all the work. You just need to know what's going on so that you're not blindly robbed or, you know, someone doesn't make a mistake by accident. You know, title companies make mistakes. Like I mentioned that $6800 security deposit. People make mistakes, right? You need to know enough and know the details enough to catch those mistakes before they happen. Because it could cost you real money. So you just want to have a really, really strong understanding. Irrespective, if you decide, oh, my gosh, there's. There it is. There's two more, actually. Okay, two more wasps wrapping up. You need to understand, understand it enough to know what's right, what's wrong, what's missing, what's not missing. If you're doing a good deal. And we're going to break all that down at our workshop that we're going to have later in September here at this property, actually. So you'll get the beautiful view of the mountain behind me. Hope you enjoyed it. See you next time, everyone take care of. Thanks for watching. Subscribe for more.










