Underwriting Gangsters LIVE
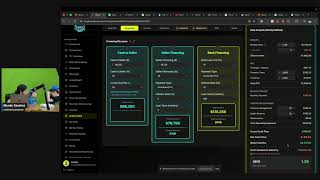
Mundo Sanchez walks through a real $175,000 property deal that scores 69% on the Morby Method, just below his 70% cutoff. The deal is over-leveraged with negative cash flow of $59,000 and only $20-25k buyer surplus when he needs more. He shows how adjusting financing terms could fix it, but each move creates new problems.
Chapters
Yeah, what's going on everybody? What's going on? We are doing a behind the scenes live Underwriting Gangster podcast. All right, so let me hit go live here on Instagram. And so the priority, just FYI, is the actual recording. So you're watching behind the scenes of how I make my podcast, which is Underwriting Gangsters. So we're gonna dive into underwriting a property today. We gotta see your pretty little face. We can't even see your face, buddy. Okay, let's leave that there. Hey, let's, let's leave that. Yeah, let's leave that there. Okay, you want to put that next? How about we wait till we record? Okay, so I am going to hit record here.
Ready?
Hey, we're gonna start the podcast, you guys. Oh, where's your hats? Um, I got your hat. Who wants— who wants the Minion hat?
You want the Minion hat?
No, me.
I do.
Yes. You like the Minion hat?
No, I'm gonna put it on.
Or do you want this hat? You want it backwards?
No, I do want it backwards.
Well, that— that's the cool style. Oh, good job, Beckham. All right, you guys ready? We're recording. Okay, hold on. Ready? All right, let's do it. Welcome back to Underwriting Gangsters. We got another episode with our special guest, Hudsy and Becco, in the house. Say what's up, everybody.
What up, buddy?
Say hello.
Uh, how would the sucker puppy at a cool property?
They want a sucker and a cool property. We're gonna be doing this podcast every day, Monday through Friday, as much as we can. Usually they get a sucker, and they were very disappointed to know that they can't get a sucker every single day that we do this. So that isn't a disappointment already. Yes.
You want both? Yeah. Okay.
All right, well, let's do both. All right, let me share my screen and we're gonna jump right to it. Let's underwrite a deal. You guys want to underwrite a property today? Yeah, yeah, let's do it. Okay, all right, so we're underwriting a property. And this property is $175,000. You want to push what, buddy? You want to push the button? Okay, how about we take turns pushing the button? You push the button first. Yep, Hudson, now you push the button. Good job. Okay, so we have a property that is— okay, okay, okay, that's enough. Thank you very much. We have a property that is $175,000. This is structured as a Morby Method, and I intentionally picked this one out because it did not pass my underwriting standards, and we're going to talk about why it didn't pass my underwriting standards. So this was just on the cusp. My underwriting standard is a match score of 70%. This is at 69%, and we're going to walk through it. So the initial structure is 50% cash to seller. Hey, can we stop playing with that, please? Yeah, I understand, but you're making a lot of noise. So then we have seller financing at 50%, and we are going to structure this as a $100 monthly payment. Apparently I put him to sleep already. We've lost one guest. Hey, you're not gonna get your salary today if you don't— are you gonna participate? Yes. Okay, we gotta make sure you get— you gotta earn your salary, buddy. I don't know what his salary is. I think it's, um, probably bars. I think that's his salary for the day. Uh, well, I take that back. In alliance to the IRS, he will be getting paid for this episode. Hey, don't hit him in the head. No, no, no, no, let's, let's calm down. Okay, that's enough, that's enough. We don't hurt him. Okay, so we have bank financing at 75% is how we're structuring this. So the monthly payment is $918. Hey, we're not gonna hit him in the head. Okay, monthly rent is $1,750. Okay, so we have some vacancy in there at 5%. We have our PITI with our property taxes and insurance. Can you say PITI?
No, I can't.
Say P-I-T-I.
T-I.
There you go. You say it.
What?
What? P-I-T-I.
P-I-T-I-T-I.
P-I-T-I-T-I. That's what we're doing. So P-I-T-I-T-I is $1,289.64. Then we have $100 a month monthly payment. We have 10% for property management and CapEx. So let's look at the bottom line. We have gross cash flow at $106. Net cash flow negative $59,000. So we are essentially breaking even at a slight loss. Now that looks fine on paper, but I will tell you from experience, I have gotten— hey, we're not hitting him on the head or you're going to be off the podcast, okay? So I will tell you from experience that being at a break-even point is a very is a very dangerous position to be in because real estate is expensive.
No, no, real estate.
Real estate is very expensive. And what all it takes is one month of vacancy and your entire annual cash flow is gone for the whole year. We want to make sure that we have some stuff on the bottom line. So now when we look at buyer surplus, this is cash that you would be getting paid at closing. So I like to have it structured to at least around $20,000, around $20,000 to $25,000.
Okay, okay, okay.
Around $20,000 to $25,000. But the major problem that's with this deal is that our cash needed at maturity is $44,000. So what that means is we're actually overleveraged quite a bit. So you will want that as close to zero as possible, or even negative, because if you, if you get to the point where you refinance this loan— so if we go— do you need to sit on my head? So if we get to the point where we refinance this loan which is a period of 8 years, you can see that we are over 11. This episode's going well. Okay, that's enough sticky fingers. Okay, so if we adjusted this years to refinance upwards, we would see that number even at 10-year balloon. That means we're still $30,000 overleveraged. So what that means is when you get to that 10-year period, you're going to have to stroke a check for $30,000. Okay. Okay, guys. We have to pause the broadcast. Okay guys, we gotta have a talk. We can't do this anymore on the podcast because you're gonna get fired and you're gonna get fired. You don't want to get fired. Yeah, you're gonna get fired. You're gonna get fired and you won't be on the podcast anymore. You'll have to go upstairs if you're not going to participate. Okay, we're not going to touch the microphone. Fired means you don't have a job anymore. Okay, okay, so we want to be good. All right, we're gonna sit and listen. You can be silly and have fun, but we can't touch the microphone anymore. Okay, I know we'll play here in a second. Okay, we have to underwrite the property to see if we're gonna buy it or not. Does that sound cool? Okay, okay, all right. Okay, so we move this to 10 years refinance. We're still overleveraged. So the only levers that we have to pull is bank LTV. Well, there's actually a couple levers. So we're going to lower this bank LTV, which lowers our overall leverage, and you can see that dropped it from $30,000 down. The other lever you can pull is giving the seller more. So now we've gotten this down to $13,000 or almost $14,000 over leverage. But the problem is now we have to bring cash to close on this deal. So in this Morby Method type of structure, it's not exactly how I would like to structure this. So right now, as it sits, this is looking like a deal that would be really hard for me to actually make work. Um, So if we look at— okay, okay, no hitting, guys. Yeah, no, we're not going to be hitting. Okay, leave it alone. Leave it alone. So you could continue lowering this leverage down to 65% to make this to where the cash needs at maturity is a workable deal, or you could increase the refinance. So typically what I see on my end, very, very difficult for you to do that. You can also make some adjustments. You see here I have a 75% LTV, so you could make a little bit more aggressive assumption that you can get 80% LTV on your exit refinance loan, and then that'll pretty much bring you to a break-even point, which would be a really good point to be at, and then you can potentially make this deal work. However, you're not really getting much buyer surplus at closing. So I can bring this up slightly to get that number back up, but it's kind of like a, um, hey, calm down.
Don't get my trophy! Don't get my trophy! They're fighting over pretend trophies.
Okay, whoever is gonna get— whoever is gonna underwrite this property the best is gonna get the trophy. Okay, those are the rules. Are you gonna underwrite this the best?
Yes.
Or is Hudson—
me?
You are?
Yeah.
Okay, well, let's— hey, part of underwriting is we have to be good, and we have to let— we have to watch the numbers. You've got to pay attention to the numbers, okay? Because if we don't pay attention to the numbers, we lose cash flow, and then we lose cash flow, then we go broke. Okay, well, yeah, we don't want to be broke. Okay, because then we don't have a house. Yeah, that would be bad. So we have to make sure we make good decisions or we lose a lot of cash flow. Okay.
All right. What? Let's be angry with that.
I don't know what you said. Be angry? What? Okay, moving on. So Let's take a look at this deal structure. So again, this is, this is why the deal's on the borderline, and we're still kind of at this 69% mark here. And ultimately, when you're looking at these numbers, there's the— it's just hard to make this deal work. The revenue is just not high enough. The, the debt structure is not where I would like for it to be in order for me— that in order for this deal to work for me. Now, this may work for other people, but it doesn't work for me. And notice how the DSCR is actually pretty good, but when you start to layer in the other debt structure, uh, hold on, let's see. Is this going to be sent out? I'm watching this on my cell phone and I really can't see, so I'd like to have a link. This is actually live on my Facebook and YouTube, so, um, you can check it out there. And then this will actually be a formal podcast episode on my YouTube channel as well. So if you can navigate through all the children screaming. So again, overall, overall, this deal is not a good deal for me. And that's it from Underwriting Gangsters, and we'll see you guys next time.
Bye! Get trophy!
Bye! He got the trophy. Good job, good job, you got the trophy. You got the trophy. Good job, good job, good job, good job. Okay, okay. All right, good job, guys. Good job. All right, well, that was the longest 9 minutes of my life. Uh, uh, all right, well, that's it for Underwriting Gangsters live edition. I'm gonna be back here at 10 o'clock and there's going to be no screaming kids during that episode, and it's just going to be straight action taking. You're going to see me take as much action as humanly possible. So if you've ever wanted to be a fly on the wall, uh, for an operator moving at lightning speed, that is the time where I'm going to be doing lightning speed operating. I'm going to be underwriting deals, I'm going to be cold calling. What's that? I'm trying to get my bunny. Uh, George, yes, Buy Box Club does do multifamily underwriting. So I can just show you that real quick here. Uh, I don't have a ton of examples. I may have to create a new one. I don't know, we'll see. Uh, so I have one example that I've just been testing off of. Mainly what I'm working on getting dialed in is the single-family multi-uploader. So I'm not going to talk about that really right now this morning, but as far as the multifamily, yes, it does do multifamily. It's definitely very different from single-family underwriting because there's NOI and cap rates and that kind of stuff. But you can see, yes, it does do multifamily. So I will be back here at 10:00 Eastern Standard, so in about 50 minutes, and then we're going to start hammering out. I'm actually going to be doing a countdown. So I'm going to have a clock, 30-minute timer, as quick as I can taking action every day. And you're going to see that literally, you know, even if you just do 30 minutes a day, you can create a lot of momentum as long as you're consistent and you just show up every single day. So that's what we're going to be doing for that show. I will see you guys in a little bit.










