Two real estate investors explain why seller financing changes everything in a deal. When the seller finances part of the purchase, the numbers work even if the cap rate isn't perfect.
And then seller finance. So that was the other part.
It was the seller financing that I liked about it.
And basically this is a go deal if we ask for less or whatever, and definitely seller finance.
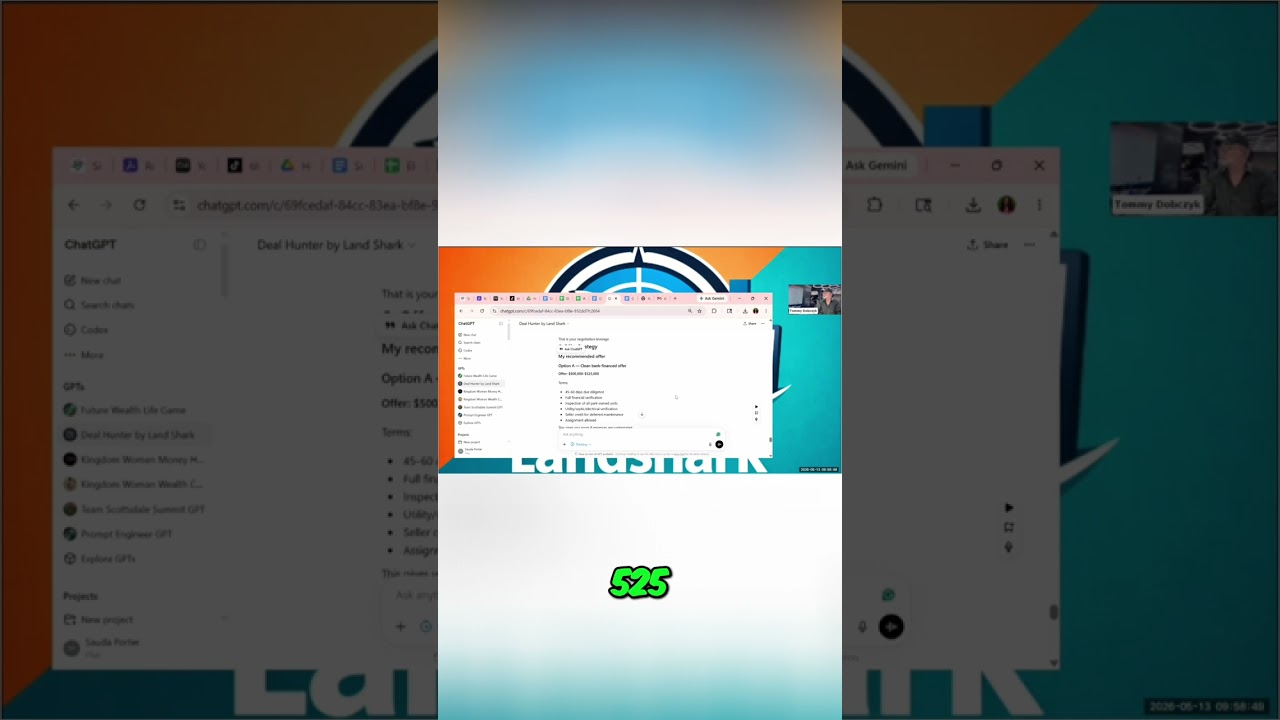
And then the value cap rates show based on the estimated value, that 8 to 12 cap rate range. They were at $600,000. So they're at about a 9 cap. We'd like them to be at a 12, because again, they're not a name brand. Anybody that's not a name brand, you gotta start in the double digits minimum. If you ain't got 20 years of track record, you gotta start in the double digits. So it says to offer between $500,000 and $525,000, and that's with us getting a bank. If the seller wants to close at $600,000, make them carry the down payment of 15 to 20%, make them owner carry. It says here, go is $550,000, but if they do seller financing, then go with a— we'll make it a go at a bank rate. Because again, we gotta get the books right. We gotta get the park stabilized. It's gonna take 2 to 3 years. And with all that done, then we can go back and refi and get $1 million to pay them off. So I like it.