Most Film Crew Miss This Money Strategy
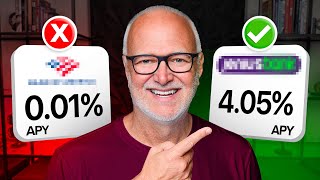
Rob Perkins (host) explains why freelance film crew should use high-yield savings accounts (HYSA) instead of traditional big-bank savings to create a "peace of mind" emergency fund. He compares common banks' tiny rates (~0.01%) to several online HYSAs (examples shown: EverBank, Genius ~4.05% APY; SoFi ~4.3% limited), lists selection criteria (FDIC insurance, consistent APY, no minimums/fees, easy transfers, good app), provides a step-by-step setup guide, and offers behavioral tips (name the account, automate saving). The video emphasizes protecting essentials with liquid, FDIC-protected cash while smoothing irregular freelance income and cites a CBS stat that 42% of Americans can’t handle a $1,000 emergency.
Questions this video answers
42%
EverBank and Genius
Nearly 25 years
4.05%
4.05%
Chapters
Well, this is awkward. Your bank, the same one you've trusted your whole life, has been slowly making you poorer. Not because you messed up, because the system is designed that way. While they pay you pennies for using your money, there's another account, totally safe, totally legit, that pays around 400 times more interest. And almost no freelance film crew use it. Not because it's hard, but because no one teaches this stuff on set or in film school or school or life. Today I'm breaking it down step by step. What the account is and how to choose the right one, how to set it up and the hidden details, even the financially in the know people miss. By the end of this video, you'll know exactly how it works, how to protect your money, and how to use it to create real stability in an industry where income goes up and down like crazy. Hang to the end and I'll reveal the actual accounts I use. Even if you think you already know exactly what I'm talking about. I promise there are details in here you've never heard before. I'm Rob Perkins. I've hired thousands of crew members over nearly 25 years. And I'm on a mission to help 1000 freelance film crew build $1 million in wealth. Let's take action. This headline stopped me. CBS reported that only 42% of Americans can handle a $1,000 emergency without using their credit card. Now think about freelance film crew. Our income isn't steady. Shoots come in waves. And lately those waves have gotten smaller. More like ripples. More waiting, more competition, less double dipping, and less money in your bank account. And everyday life still hits you. A car repair, a vet bill, unexpected travel. And any one of those can send your credit card balance through the roof. If you don't have a savings, or as I call it, a peace of mind fund, here's the part most crew don't think about. Emergencies don't wait. And credit card interest does not hesitate. And where your money sits determines whether you stay stuck or start building stability. Let me show you the difference. A High Yield Savings account, or HYS or hisa, is just like a regular savings account, but it pays way more interest. Instead of earning $1 on $10,000 at Chase or Wells Fargo, an HYSA could earn you around 4%, and that's $400 a year. On $10,000, you still have FDIC production and easy access. Just like the big banks. Your money is in a place that is finally a smarter spot. Just so you know, I'm not a financial advisor. I'm showing you what works for me and what's working for the crew members I coach. Personal finance is. Well, it's personal. So choose what fits your situation and do your own research. Now, here's why this matters. $10,000 in a traditional bank equals a dollar interest. $10,000 in a high yield savings is 4% interest, which is 400 bucks. That's 399 more dollars just for clicking a different button. By year two, it's about $10,816. And by year three, 11,248. That's a vet bill. That's a car repair. That's a buffer between shoots. We're in an unpredictable industry. We have competition for work. And using a high yield savings could give you the edge against the competition you need. Let's go online and compare a few accounts. Here we have bank of America Advantage Savings. And here we are at 0.01%. And then we can move over to Wells Fargo and we see pretty much the same thing, 0.01% chase, another really popular bank. And we see that it is the interest rates. 0.01%. What do you know? All right, then we can go to a bank that I like called EverBank. And EverBank is 4.05%. And they even have a cute little calculator here where you can punch in $10,000 and it shows you that you will make $404 per year. And just like the other ones, they have FDIC insured. And no minimum balance required, which is not at most of the other ones. You'll look at the fine print, you'll find that there are minimum balance requirements and there are also some maintenance fees unless you keep that minimum balance required in. Here's another one, genius with a J, J, E N I u s again, 4.05. They too are FDIC. They have humans available to talk to it 24,7 interest compounded daily. That's really important. I don't think I mentioned that before. And easy withdrawals and no fees or minimum balance requirements. Now here's the last one here, pretty popular one is called Sofi. And SOFI is. Oh my gosh, look at that. 4.3%. However, if you look at the fine print, well, the medium sized fine print, it says 4.346 months. Okay? And then you click on this little one here, it takes you down to the fine fine print where it says 4.3 for a limited time and it will drop to 3.6 APY after that. Now I'm pretty Sure, that's what this says. It's a lot. There's a lot here. So if you like Sofi, you're a fan of the brand, that's not a bad interest rate. But I would encourage you to go to these websites, read the fine print, call them up, be sure that you know what we're saying here and what you think you read makes sense, and even download the app, try the app, make sure you're comfortable with the app. And another thing that I would say, little pro tip having done this, and I'll never do it again, is you don't want to chase rates. Okay, if every bank is 4.05 and then you realize that genius is, you know, 4.1, you know, don't, don't move for that small amount. I mean, move poor a percent or maybe 0.8% or more. But you don't want to change banks every, every few months. It's just too much work to transfer the money. So pick one you're happy with, stick with it for a while and choose it because you see that it has a. Has a history of having a. Having a high rate. All right, here's a personal story. Last year we sold our house faster than expected and had to move into an apartment while the new home was being built. From the sale, I set aside the exact amount we needed for closing down, payment fees, everything. And I put it in a high yield savings account intentionally. I wanted that money to be safe and liquid and growing. A way to make money with my money. And the interest alone covered our apartment rent for every month for nine months while we waited. Meanwhile, I invested the rest. And 2024 was a great year for the stock market. That's what a real financial system does. Protects your essentials, grows your long term wealth, and keeps you calm between shoots. Now, here's where most people choose the wrong high Yield savings account. Let me show you exactly what to look for. One. FDIC insurance, $250,000 per account. And most banks have $500,000 for a joint account. And some even offer 2 million through partner banks. Number two, a consistent APY, not a teaser rate. If you want a high annual percentage yield or apy, but it seems too good to be true, it's not. For example, if it says 7% for 90 days, skip it. Number three, no minimum balance. If they require 300 bucks to avoid a fee, keep moving. No monthly fee is number four. That's non negotiable. Number five, you want easy transfers. Instant Verify is ideal. And some banks require Micro deposits. More about that in a minute. Plus a clean mobile app. If it's clunky, you're not going to use it. Alright, you know what to look for. Now let me show you how to set one up. It's easier than ordering lunch. Step number one, pick your bank. EverBank, Genius, SoFi. All good choices. Step number two, grab your info. Your name, address, Social Security number, photo ID and your checking account to link. Step number three, start the application, go to the website and hit open account. Step number four, agree to terms the current APY and check that they are fdic. Step number five, you verify your identification with a stuffed credit poll. With security questions. It might even have you upload your photo ID or do a selfie check. Step number six, link your checking account, your routing and account number or instant verification or micro deposits. They send a few cents to your bank account and you confirm them. And yes, they take them back. You don't get to keep that. Step number seven, fund your account. $50, 500, $5,000, whatever works. Your account is earning interest immediately. Step number eight, set up access, app notifications, your password, two factor authentication. All really normal stuff. You've done it before. Step number nine, make a savings plan. Start with 5% of every check and then if that gets easy, move on to 8 and then 10%. This is how you smooth out the busy month versus dry month cycle. This is how the financially fearless crew operates. There's a top 10 less secret that the popular banks don't want you to know about when you search online. Best High Yield Savings Account. You'll see the same banks over and over again. Not because they're the best, but because they pay financial sites to promote them. This is insider intel. Once you know it, you stop assuming that the most popular option is the smartest one. Give your account a name. It matters. Mine's called Peace of Mind Fund. You could be downtime buffer or calm between Shoots Fund or Smart Savings Crew or Smart Crew Savings. When your money has a name, you treat it with respect. Every time you move $1 into your peace of mind fund. You're saying I'm the kind of crew member who's prepared. I'm the kind that doesn't panic between shoots. I'm the kind who builds wealth with purpose. That's who the financially fearless crew is. This is where the shift happens. You're not behind. You're not bad with money. You're not even late. You just haven't been shown a system that actually works with inconsistent income. That changes today. Start small, automate one thing. Let the system carry the weight. Your future self, the calm version of you will. Thank you. The banks I use are Everbank and Genius. They've had consistently higher APYs than the name brands, they are easy to use and their customer service has been fantastic. If you want to understand the bigger picture, why I started this channel, and where this entire movement is going, watch this video next. Why I started this channel and where it's going. Thanks for watching. Stay focused. Stress less. Build wealth. That's a wrap.