Latest Economic Headlines for Sales ft. Jim Swift
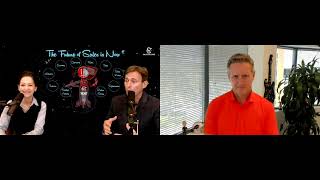
Jim Swift of Corterra discusses what companies actually buy using $1.7 trillion in aggregated supplier payment data. Year-over-year spending jumped across 75-80% of industries, with building materials up 26%, electronics and IT surging, and manufacturing up 11%. Sales leaders can use these signals to redesign territories and prioritize accounts.
Questions this video answers
Over $1.7 trillion in annual spend.
Estimated about $8 trillion total; Corterra captures more than 20%.
About 75–80% of industries were spending more year-over-year.
Chapters
So welcome everybody to Sales Globe's Rethink Sales Roundtable. We're glad to have you. I'm Mark Danolo of Sales Globe. I'm here with Michelle Seeger. Hey Michelle.
Hello, Mark. Hi everyone.
And we got a great session for you today. We're going to be talking about the economic outlook and what's ahead for 2021 and beyond. And let's tell them a little bit about salesglobe.
Sure. So Sales Globe, what we are is a problem solving firm for sales. We solve the big biggest challenges that sales organizations face as they are going to market. I mean that is really the reason that we've got these roundtables. And today we're going to be talking about one of the problems that sales organizations face which is really understanding what their market opportunity looks like and heck, what's the outlook anyway in the United States? So we'll get into some of the data that is being used as we introduce our guest. You'll see that we have written a few books at Sales Globe and we won't be talking about them today, but we are going to talk about the future sales Mark.
That's right, that's right. So this is really cool because we've been talking about big predictions for 2021 and now we're looking at future sales. This is foz here in the middle is helping us. Yeah, but, but there are a number of big considerations as we're looking ahead that range from how we're looking at the market to our strategic accounts to how sales roles are going to work. Are they going to be hybrid or inside or back in person or some combination what sales capacity looks like. And one of the areas that we going to talk about is opportunity. And the point is what's happening with market opportunity and where is market opportunity shifting? Because it's not static probably more than ever, you know, it's actually moving in different places. So we had done these predictions and we can give you a copy of these if you'd like. We have 25 predictions for 2021. We're not going to take you through all of them, but there are a couple here that we wanted to highlight because we're going to talk with Jim about this today. Number 10 New Sales Potential data sources will be required beyond dollars per fte. So what that means is basically, you know, when you used to get that old data that said, well, we got this many FTEs in a company and then we're going to correlate it with $1,000 per FTE per year. And that's going to be our potential that's just not working because we can't look at something so static and we can't look at history any longer. And also industry targeting, targeting of sectors in the healthy sectors is going to surpass general industry deployment, which basically means if you're looking at territories, you're looking at your total addressable market. You need to start to get specific about which, which industries are coming back faster and those are dynamic as well. So I'm really excited, Michelle, to get into this today and talk about like some of the real information behind this and what's really happening.
It's pretty fascinating. So what you're going to be learning today for everyone that's here with us is how different data sources can actually help you understand what your potential is and really get pretty granular about the opportunity which will actually end up informing your territories and deployment of your team. So I'm really excited and actually very privileged that I will be introducing our guest today. And with us here today is Jim Swift. And Jim is CEO of Corterra, which is a data company and a Moody's data analytics company. They were recently purchased by Moody's. Congratulations Jim, on that.
Thanks.
Yeah, it's very exciting. So what I thought we could do, Jim, is you could talk to everyone a little bit about yourself and your background and, and you know, you and I had an interesting conversation with Mark just before this about what it's like this transition now as you are are holding on more than one hat running your business and, and looking at the integration point. So welcome and tell us a little bit about your story today.
Yeah, thanks. I'm a longtime data guy and I started in the consumer world doing different kinds of data and analytics solutions around sales and database marketing as well as risk. And then I started to work in the B2B space and that became a real passion of mine. So I've spent most of the last 20 years building companies around analytics about businesses. And the killer insight to me is really understanding what companies buy. For years I saw businesses rely primarily on firmographic data to understand their customers. And it's fine the concept of what a company does and how big they are. The problem is it's really hard to get information that's accurate about what they really do. Industry codes like NAICS and SIC codes don't work and a lot of times they don't fit neatly on your business. And then understanding how many employees or what the sales volume is for a company is impossible because they're private. Most businesses in the US are private, and they don't want to tell you that or they'll lie. And so we need better ways to drive better analytics about who our best customers are. And so I said, you know, we're going to go and we're going to make that our whole mission. We're going to build data assets that help us understand what companies buy, and then we'll combine it with all the other data we can go get, but that'll be the core of it. And so that's what we've done. And we were recently acquired by Moody's, so now Moody's probably has the most information globally on businesses. We know about nearly 400 million business locations around the world. We're in every country, 11,000 employees in 41 different countries. So to be part of that, now, I can go seize control, grab information from around the world, and I can start to make some really interesting solutions beyond just the North American focus that we had.
I know, it's so exciting for us too, because everyone, Cortera is actually a partner of Sales Globe. And we love the data that you have and we love it for our clients. And we're excited to see how that data can be augmented with other sources too, that you have available. And we're really excited to see what it is that you guys will be doing next.
Me too.
So, Jim, with the data and we can start to take a look at some initial views of this. We're very familiar with this, but I think it'd be great to kind of set the stage for everybody about what this information is. You talked about purchase data and B2B, but what is the information? How much is there? How much of the US economy does it represent? Just kind of give us some framing and, you know, where does it come from?
Yeah, so we have a network of companies that basically contribute information about how their customers pay them. And so there's this traditional credit bureau model, but that's evolved into all these other use cases that they have for information. Because you only make credit decisions when you're acquiring a customer or you're worried about an existing customer. And so it's a support function to really the lifeblood of a business, which is getting new customers, retaining them, developing them, so that they buy more from us. That's what makes the world go around. So that's the database view that we have. And right now we capture over $1.7 trillion in annual spend between companies. We think, as we can tell, there's about $8 trillion in spend that's invoiced between businesses every year. And we're capturing more than 20% of that now, and it's been expanding rapidly. So we put it in 45 different buckets, different categories, but we roll it in different ways in order to deliver insights into what's happening. Our view is if I can't understand. If I can't see a business literally, and see all their financial statements and everything, but I want to understand what they're all about. I want to be able to see what they spend on materials that go into the business if they do, and spend on shipping that goes out if they do, and then what they spend on things that tend to happen inside that black box. So an accounting firm doesn't buy materials and doesn't really ship anything. So the absence of that data is interesting. A manufacturing company buys materials. How much they buy gives me indication into what they really are building inside there and whether they're building more or less than they did last year. And then shipping goes out. So that gives me an idea of what their sales start to look like. And so it just gives me much more power to understand who my best customers are and then be able to track a business and know if they're really growing or not. Not based on some guess at their financials. You know, I'm looking at what they're actually buying.
So you. So you can see the business down to the company level. You know it, of course, by industry, you can see how much they're purchasing. What are the different categories of purchase that you look at? So you say accounting firms obviously purchase different things in manufacturing firms.
Yeah. So first of all, you are what you buy like people. Right. I think we've talked about this before. If you buy a motorcycle or you buy a minivan, I just need to know that one data point, and I can exclude or include a lot of things about you, and then I start to know two or three things. And, you know, if I do six things you bought that were important to you, I'd be able to paint a nice profile. Businesses are the same way. So we like to. A lot of our analytics are based on what we find are the top four or five categories of things that a company buys. So if they spend the most money on something like metals and truckload shipping, that tells me that they're a manufacturer and they probably don't have their own fleet of trucks. So two awesome things to start with right there. So the categories are materials that go into a business to manufacture things. So metals and Chemicals and plastics and electronics and other things. And then we also have categories around materials that are more toward construction. So roofing materials, lumber, general building supplies, things like that. So that helps us start to understand are they making something or are they providing a service? Going out of the business. We have things that are related to fleets. So if you own a fleet of trucks, then you spend on fuel, you spend on tractor and trailer leasing, you spend on supplies like tires. If you don't have a fleet of trucks, you're spending with third party carriers. So you're shipping everything by FedEx or UPS or whoever, but you're spending on truckload and less than truckload and air freight, things like that. So by understanding this, you know, now, now I can really paint a picture of who my best customers are. If I'm a bank, I'm looking at a business a certain way. If you have a fleet of trucks, and I'm a banker and I'm insurance carrier and I'm selling to you, I'm looking at you very differently, knowing that versus if you don't have a fleet of trucks. That concept is totally lost if we just look at SIC codes or NAICS codes. Because you're a manufacturer. Two manufacturers could have the exact same firmographics but has a fleet and one doesn't. And their risk profile is totally different and the opportunity is different. And then if I start to sell, if I'm selling fuel or I'm selling other things to them. Technology for managing your fleet. Well, I want to know that you have a fleet. I don't want to send salespeople out and get there. And your big company, it turns out you don't even have a fleet of trucks. You're using third party transportation providers. So you start to think about the things you can do. And it really opens a lot of new doors in how we can profile our customers.
Right. So I take transportation as an example and we've looked at your information specifically, but you break it out into truckload, ltl parcel. So you've got these different cuts. So you can basically tell how they're, how they are shipping. Right. It's not just a general shipping number.
Yeah, yeah. And so if they're using a less than truckload provider, that means it's pallets, it's probably not full truckload. So their volume is smaller or what they make is smaller. And it means that they're not putting it in their own truck, they're using someone else. Now they might have a combination, they might use their own trucks for Certain routes and then they use, for the last mile, they're using someone else. But all those things, you would never be able, you'd never be able to understand that on your own. You can't Google it. You could go knock on every door and hope they tell you the truth and spend all the time doing that. But here's some insights into the behavior of the business and the cost structure of the business and the growth of the business. If you're selling more, if my customer's growing and they spend and one of their top categories is truckload shipping and they're spending more on truckload shipping than last year, they're probably growing. And the accuracy of that is far better than some approximation of what their number of employees was last year and is this year, because that's likely to be wrong. It has a lot more error in it.
Yeah, now that's, that's kind of good. Data geek. Fun. Fun.
I'm not a data geek and I think it's really cool. So this is good because I wanted to start to get into this. Jim, why don't you talk to us a little bit about what we're seeing right here and the bounce curve, something that, for those of you that join us on our roundtables, we do get this information from Corterra and we show it each month. Why don't you kind of set the stage here for what we're seeing year over year and what's going on?
Yeah, so that's our view of what happened to the economy over the past 13 months or so. So if people can't read the numbers, I'll point out a few things. It starts in March of last year as the first data point and it was stable. That was right at the beginning of the pandemic. And what this shows you is the year over year change in spending by businesses in the U.S. so if you look at April there, It's the numbers minus 10.4. So businesses spent 10% less last April than they did the year before. And that's when the pandemic was starting to really bear down on us as businesses. And then it hit a low point in May right there. And you can see since then we have been on a steady climb back. Now this is the overall number. We have this sliced every which way. We have this down to every individual company in the US but it shows you that the comeback. And then in March, we're just into April now. But if you look at what businesses spent in March, so the freshest data, it's more than 14% higher than it was last year. So this gives you an idea of what we're seeing and it's businesses are spending, they are spending more than they were last year and about 75% of businesses, 75 to 80% if you look at the industries that they're in, at the NAICS 3 level, they are spending more than they were last year. So it's a broad based recovery is what we're seeing.
That's actually very good news. So if we get into a little bit about, we took a look at some of the buyers. So let's go ahead and go on to the next graph that we have here. And this, this talks about what it is, some of the major areas, buying areas and where they are. So you want to talk a little bit about those. You, you, a few here that are the big ones. And I think it would be great.
The numbers come right out of Mark's ear like that.
I know, isn't that funny? I know it's kind of funny.
So yeah, yeah.
So point them out as I can.
So we showed the overall number and now you start to break down the dotted line. There is the same overall number to give you a reference point. But the first slice when I start to get into more detail is to break down the major components of the supply chain. These are manufacturing companies in the green line, transportation companies that are moving goods and in the pink line and then retailers in the blue line. And the retailers you can see weren't as affected overall, as affected as these other types of companies. And you think, well, wait a minute, how does that work? Consumers have been shut down. But what we saw is this. It's like, go to your corners. We had a whole bunch of businesses like Internet shopping and grocery stores that went way up because we worked from home. And then we had other businesses that went way down, like restaurants because we were working from home and we weren't going out. But as a net, consumers continued to buy a lot and they just bought it differently. We all bought Amazon, the magic Amazon accounts. So that's what retail has done. But we see that retail spending, spending by retailers with other businesses was up 9% last month. You look at those other curves and this shows us that it's not just one part of the economy that's strong. They're all going up, they're all positive. So the green line there, manufacturing shows you that we were hit hard. A lot of manufacturing was shut down, the plants were closed. We were not making things. And the manufacturers part of it was because consumers weren't buying their goods. And part of it was just fear of the unknown. If I'm a manufacturer, it costs me to make things and to store them in my warehouse. And so sales forecasts become crucial to me. And if I'm getting conservative about what might happen and I can't move product, I don't want to just have my profits go away. So manufacturers are all very conservative about their production forecast. And so that's why you see them get impacted the most. And the fact that they're now 11% higher than last year with their spending, fantastic sign. And then the transportation line is interesting. That really ties to the flexibility of our supply chains. So as our behavior changed, picture what was going on last April, May. We weren't going to restaurants and we were going to grocery stores and we were cooking, in my case, poorly at home. And so the manufacturers had to respond to that. They had to, instead of bulk packaging things, they had to get it in little containers that could go on a grocery shelf. And the transportation companies had to totally change the way they got the materials to a different place now. And the fact that. And they needed more it in order to figure out new route planning and capacity management, all these things. Right. There's a trickle through all of their suppliers, but they adapted remarkably well. We didn't have empty grocery stores and I mean, okay, we didn't have any toilet paper, we didn't have any, any Lysol, but that was about it. Right. And so for that pink line to continue to go up just tells us that we have really strong supply chain components in transportation. And the fact that it's higher now is another sign that we are moving more product and we're moving it differently. We're moving it because people are buying from Amazon or wherever and we're moving it straight into consumers homes instead of a store perhaps sometimes, but we're moving a lot of product. So this cut where you can see those major components of the supply chain all doing well tells us that the number's real. We're not building this on sand.
So do you see, Jim, anything in terms of potential bottlenecks coming up? Because we looked at this a few months ago and one thing we saw was that wholesale was up, but manufacturing was still down. And we thought, okay, well there's going to be kind of a shortage there. But is this, these curves all moving in a healthy way or do you foresee anything in terms of bottlenecks on supply chain?
I would say overall it's pretty healthy. And the businesses across the supply chain are better than we understand typically. This is highlighting how good we are at managing inventory through these pieces. If you think of how effective we are in having goods available to us, whether we're going to Amazon or we're going to a store, isn't it? This is just a reminder of how remarkable we are as a series of industries in this country at planning the production so we have enough stuff and getting it to where it needs to be. And I think people, even now, I don't think they understand, but boy. And I always use that food example because it's so dramatic. And the fact that we totally switched gears and bought differently and we were able to do that successfully and now we're totally switching gears again and we're going the other way really fast where we're back to restaurants because everybody's sick of cooking at home. And it's there, it's working.
And that's crazy.
And so when you look at different supply chains, you can break these down. You find different factors like the clothing industry has a lot of seasonality to it and so you have to account for that. So pricing changes and inventory changes because you need to get the new season's merchandise in there. And so you're doing different things. And so you have to be able to read the data the right way sometimes because there can be a time shift in this. And part of it's consumer demand. Part of it's just the nature of those industries. You have perishables within food. So overall when we look at all these, it's been remarkably consistent and some have been even more dramatic than the average like transportation equipment. The auto industry and the airline aerospace industry was crushed. They were down 60 plus percent in their spending. But last April and May, and they're actually in positive territory now. So they've. They figured it out. Consumers are buying cars and we're starting to return to travel. And I mean it's just. That's remarkable. What's, what's going on.
Yeah, it's pretty incredible. We were talking about how crisis like this, this pandemic, it really spurred a lot of innovation and creativity and what you said is different use cases even. You know, we had a, an interesting conversation about the transportation. What airline industry was doing and, and how they were servicing different industries than maybe they were even before. Right. Things were being repurposed. You brought up the example of people weren't traveling, but technology sure was right. So there were just different uses that, that companies were putting their services at, at work. So I find that really fascinating. The other thing that I didn't realize when you talk about the food is how many different touches happen throughout that supply chain. So I do think it's very remarkable that we've been able to adapt as a people, as an industry, the way that we have been able to adapt. Although I still have no idea why there was no toilet paper. That's the one I could never bite, never figure out.
It ended up in everybody else's house.
It was kind of weird, I guess.
The irrationality of consumer behavior.
It was kind of crazy.
Yeah, some people were hoarding toilet paper, some people were hoarding real estate.
So someone in your neighborhood with a garage full of toilet paper right now.
So Jim, when you look at this, this is supply chain and you talked a little bit about sectors, what do you see as some of the hot sectors coming back? And we've seen some of your data of the ones that are really up and the ones that are still down. And that shifted because you know, we saw obviously restaurants, bars were down, food purchasing was up through, through food stores, you know, some medical was up. I think purchase of alcohol was up. I mean so, but, but, but this has shifted over the past several months. But, but what, what's hot right now and what's not hot right now? Terms of industries.
Interesting trends and it keeps changing a bit. So just to tick through some of the high points, electronics and anything IT related went off the charts last year. We saw tripled spending by businesses on it. Electronics and so you saw that through the supply chain. So the companies were buying it. You had distributors pumping everything they could out and then you had the manufacturers trying to really keep up and continue. And we're seeing a lot of backlog still to this day in the ordering of that. But that went way up, like I said, tripled. Now it's still up around 30% year over year. So it didn't settle back down, didn't just come back down to earth, it came down to a higher level. And I think that's partly because businesses are still working remotely. I think they're relying more on technology and so are people. And so just the sheer amount of IT related stuff that we're purchasing is higher and it probably will be. I think we may have reset normal. Right. So that's been an interesting one. Medical supplies obviously, just because of the pandemic, because of everything. Personal spending on that as well as businesses doing more around safety, that's up. Some of the other ones though that aren't as obvious One is industrial equipment. So I like to look at some of these plumbing related things, which is up too, by the way. But industrial equipment is interesting because if I'm a manufacturer and I'm not sold on my long term growth, I'm probably reluctant to invest in my industrial equipment. I'm not going to go create a new plant, new assembly lines and all. I'm just going to kind of wait. I'm going to keep my capacity where it is and just be conservative. When I'm confident about my future growth, I'm going to invest in the things that are going to take 20 years to pay back or five years to pay back, but live for 20 years, whatever. And so the fact that we're seeing spending on industrial equipment up 10 plus percent over last year is an interesting one. So if you're selling industrial equipment, that's great, right, because you excel. But if you're selling to a company that's buying more industrial equipment, that's an early indicator that they're gonna, they potentially can buy more of the what you sell to. So this is how this data can be used in sales. And a lot of companies don't have the muscles yet to think about how to do this. But that's an easy example of if you know what your customers spend money on and you know that certain spends will correspond to how much of your goods and services they'll buy. Track that. So that's an interesting one that's popping around. We're seeing restaurants just in the last month are taken off. Part of it's the weather maybe, but it's year over year. So it's adjusted for seasonality. But a lot of it is just people want to get out. So that's up. Hotel industry starting to come back. It still remains one of the most impacted, but it's ticking up. The airline industry is ticking up. All the hospitality curves are still under where they were last year, but they're all moving in the right direction. So almost every curve we see is on its way up.
And so this kind of correlates a bit with what we're seeing in the stock market too. Right, because we had the lockdown stocks and then we have the reopening stocks and the lockdown stocks have tapered off and the reopening stocks are coming back. So that's tracking very much with what you're saying there too.
Yeah, the work from homes, not stocks necessarily, but it definitely corresponds. But the work from home industries that we tend to look at in our basket are things like Internet Shopping, electronics, because that's tied to that. So that group is definitely. It's still higher than last year, but it's come down a little bit. And then all of those reopened stocks, as we call them, those are picking back up. And they're actually, as a group, they're above last year. And that's largely driven by restaurants. One of the things that's been interesting that I'm a little surprised has persisted is around building materials. So we saw. So tied to stock. This all corresponds to the Home Depot stock as well. But the equipment dealers, the building materials and equipment dealers, their spending since the beginning of the pandemic has been up. And at first the speculation was that that was all around home improvement, people taking the time and building out their home offices and doing all that. It's remained high. And we've seen the commercial side, the construction side all through that supply chain. So wood products, all the way back to lumber. So you got lumber through wood products distributors, through home improvement stores, and through all those distributors that go straight into the construction industry. They're all still on a tear. So it's interesting how you can follow through these supply chains and. And you see that ripple effect. And then it's all. You look at all the companies that supply goods and services to those members of the supply chain. So, you know, the fact that Home Depot is doing so great because we're all in there and construction is hot, start to think about who you might sell to that has that ripple effect back through.
Yeah. So it takes a little investigation here. You really got to learn how to. How to read the information and how to interpret it. So I think that's some of the magic in it that you're talking about. So you can look at these curves, you can look at the data. But then like they taught us back in business school and statistics class, you got to kind of figure out what's the story it's telling you.
Right.
So that, that, that's fascinating. So geographically, Jim, what do you see happening? Are some geographies in the US Coming back faster than other geographies, or do you see any. Any differences there?
We're seeing most states, 42, 43 states, increase their spending, their businesses increase their spending.
Wow.
Year over year. So it's almost everywhere. And the biggest driver is the concentration of the industries in that state. So the only states that aren't higher year over year are the ones that rely on things like hospitality that are still hit pretty hard. They're coming back, but they're the only ones Underneath, but because so many industries are doing well that some states have a lot of manufacturing or they have a lot of transportation or a lot of retail or a lot of gaming or whatever. So I think because it's more. More a function of the industries and the location of those industries dictate how the state's doing, we're seeing that much more as the driver than anything around the state's attitude toward reopening or the policies toward reopening. This is businesses and people quest on a quest to get back to normal.
You made a great point earlier about that, Jim, which I just want to bring up because we were having a chat before we gone on and you were saying something like the power of consumers and the power of businesses outweighs policy. Basically that people are ready to go and businesses by their nature, people that run businesses are bold, so they're not holding back. So it's almost like everybody's charging ahead regardless of what the policy is politically or from a government standpoint.
Yeah, I think everybody wants to be safe. But if you start a business, you want to be successful, you have this crazy internal engine that is pushing you to be successful and it drives innovation. We're seeing new industries. The online shopping is retailers who are thriving. They are getting better at. They're adjusting their business models. You know, you've got Chick Fil A has closed most of their dine in where you are, but they've become phenomenal at takeout and pickup and ordering online. And it has a ripple effect through the technology companies. So it drives innovation. So the quest of business people to succeed is they say that innovation is driven by these hard times, these hardships. So we saw a big spike in business closures last April, May. So I think that the weaker businesses got flushed out quick and we saw that return to normal levels or relatively normal levels pretty fast. And that's because business owners are, I mean, they're determined and they're going to evolve and adapt to the conditions and they want to succeed and that's a big driver. And I think as you mentioned, people too, consumers, they want their stuff and so they might order certain things online. They want social connectivity. So airplanes are becoming more and more full. You're not going to be able to stop them. They want to be out there. And so those two forces are driving this. And then we can do other things to try to heat it up or direct it, but that's a life of its own. That's not something that you're just going to dictate what it's going to do, that force between the business innovation and the business motivation and determination and the consumer, same thing. Drive to get out there, be out there, buy more, get stuff done. It's funny. I think part of it's uniquely American, but it's kind of.
Yeah, I think it probably might be. We're on international calls all the time and actually they're a little jealous at what we're doing. They don't think we're crazy. They're like, jealous. Right. You know, and you make a good point, because I'm starting to see in the headlines again very recently, just this week and even this morning, that there's spikes in small cities and towns. And they were particularly talking about some places in the Midwest and Michigan was called out a little bit. And we were having that conversation. Right. Because the vaccine distribution policy is what the vaccine distribution policy is. And the response is you gotta shut down. But what I'm hearing you say and what I believe based on the things that we're hearing as well, is that people are adapting, companies are adapting. We're all very resilient and we want to get out. So people, I don't think that, you know, it's art. Some may argue there's some irresponsibility going on, but I think for the most part, companies, businesses, they're figuring it out. Because to your point, these are business owners and they're there to make a profit. Right. To survive, to thrive. It's in their blood. They want to succeed. So, anyway, that's all good news. Now let's talk a little bit about what companies are actually buying out there. We talked about the supply chain. Let's look at purchasing trends of companies right now, year over year.
Yeah, so I mentioned things that go into businesses are interesting materials. They can be building materials or manufacturing materials. And then things that go out. Transportation, that's interesting. Food and beverage is interesting. So these are just some of the curves you see. And the same general trend holds. Almost every area is up the blue line. There is building materials. So I mentioned how those have taken off. And you can see that companies spending on this isn't who's buying, this is what's being sold. So the purchasing of building materials is up 26% over last year. And so part of this is home building is up certain parts of the country, especially here, everybody wants to get out of New York City and move to my neighborhood, it seems like. And part of its businesses who are changing the way they operate, you know, the type of facilities that they need is different. Also the fitting of their facilities. You know, they're all trying to. Everyone's trying to figure out how far away do we need to be, what do we need to do to change from a. From a safety standpoint. So that's that blue line. And you see lots of these other ones. Transportation and manufacturing materials is the gold line. They're all up. The green line is food and beverage. And you see it's relatively constant because it's not like we're going to eat five times as much as we used to. It's who's buying it is different. So this curve shows that it's down a couple percent, food and beverage, total purchasing from last year, but it's shifted from grocery stores back to restaurants.
Oh, interesting.
It's who's buying it. So you have to look at this combination, the whole insight. This comes back to our view on if we really want to understand companies. It's all about commerce and selling. And that means I have a buyer and a seller. And knowing information about them is interesting, but knowing information about their interaction is what's really interesting. Who's buying what and start to understand that world. And that's where all the intelligence is for our insights. So I can see, okay, food is constant, but the buyer of food is different. So if I'm selling to restaurants, whatever I sell to restaurants right now, they're spending more. And so as I start to figure out how I want to do my planning or sell to them or whatever, I need to factor that in. So the companies, this is just a new insight that you can use to understand more about your customers and which way they're going.
It's interesting. At the beginning of that green line there, I'm wondering if that's. That's the beginning of the pandemic. Fifteen pounds there when people started.
Oh, right.
Talking about.
Yeah, but, but I, you know, I saw the, the food, the grocery stores actually in the down column recently. Jim, that's that I was curious about that. Cause I'm like, that's a little weird because that's been up. But that's because. Exactly as you said, the restaurants are starting to come back. So it's where they're buying. So then food, the groceries are down.
Yeah. So you see that that green line is relative. If you were to average it, it's relatively flat. But last April in May, that the curves were opposite. So spending by grocery stores last April was up 25%. Spending by restaurants was down 49%. We bought about net of Food. If you look at April, May, net net, the food was purchased, the cost might have been different, the amount spent was different because of packaging and other things. But you are 25% up in grocery stores, 49% down in restaurants this past month. Finally it flipped the other way for the first time. So spending in restaurants was up 15%, 14% and spending in grocery stores was down about 14% year over year. So it's interesting to, to see we're choosing to get our food in different places. So if you think of that analogy, it exists across supply chains all the time. The pandemic, it heightens this. So we see more separation in the curves. But there's always, this is always going on, right? So knowing how much is being purchased is really interesting because it tells you about growth. Knowing who's buying it now, that starts to give you the next level. Cause sometimes the buyers just shift. If you think of the trends in online over the last 20 years, the amount of clothing and other things that we buy has probably remained. It's been on its own curve. But the way we buy it and who's spending the money to move it has moved from in store retailers to online. So as that share moves now, those companies change. So if I'm selling IT equipment, I can sell more in the retail space now than I used to because more is online. And instead of it just being point of sale equipment at the local retailer, now it's cloud based computing for the Internet retail. And those companies now you start to see, okay, what are the patterns in this traditional in store retailer? Are they moving online? And if they are, what they have to buy changes. So all this stuff is interrelated. We are one big web of companies interacting with each other. And the more we know about how that web moves around and what's changing in it, the better we can operate. We can sell more and we can do it profitably and faster.
So if you're a sales leader, Jim, and I'm thinking about a lot of people that are listening to this right now. You're a sales leader or you're a salesperson and you've got all this valuable information here, what should they do at this point? Where should they be placing their bets? How should they be thinking about this kind of information?
What folks are doing with our data is we learn from them all the time. Because when you have good data, interesting data, people get really creative. I always use Google as the example. Somehow we functioned before Google, but now Google's out there, we all use it differently and no one teaches us what to do with it. And some people are very good with it. All kinds of innovation has come about just because we can go and we have this new source for data. And so we try to set our data free, release it into the wild and see what it does. But it starts with simple stuff. Sales departments usually don't have deep analytics capabilities because the data has always been kind of crappy. It's been firmographic data. I didn't need someone who knew how to build deep analytics because I'm dealing with SIC code naics code number of employees, estimated sales volume. And that's how I'm doing all my segmentation and my sales territory alignment and all that stuff. Knowing that, yeah, it's wrong half the time and you know, whatever. So there's a certain amount of wasted energy and overhead that goes into it. And I wish, well, now we have this other information, but I don't have the database, the analytics people necessarily to deal with it. So it's gotta be simple. So first thing they're doing is they're looking at these categories they're taking. Just take a handful of your best customers and append information about what it is that they're spending money on and how it's changed over time. And take a look at that and just kind of basic analytics blur your eyes a little. And that's how humans work. You look at it and you see the trends and you go, huh, look at that. So simple examples will jump right out at you. You know, if I'm, if I'm, if I sell truckload shipping, well, all of a sudden I noticed that a lot of my best customers spend a lot of money on rail shipping as well. That's right. Because if they're spending on, if they're moving things by rail gets the end of the train tracks. It's got to go somewhere that's not usually, don't usually have train tracks going into all my customers. So now I have to move it over to truckload shipping and move. So yeah, you don't have to. I mean you don't need computers to do a lot of this. You just look at it and you go, okay, that makes sense. And so now let me get that out of my prospects and let me see, let me score my prospects and prioritize them and you're going to find people, companies that you, that the firmographic data was wrong and you're going to look at it and you're going to go, oh wow, I've been missing that one all Along. You know, Google's SIC code is business services, not elsewhere classified. There's not a lot of, there's not a lot of insight that tells me that they buy billions of dollars worth of IC stuff every year. So it can help you just by looking at that and saying, oh, okay, now I'm starting to get a feel for this. And it can also help you identify areas. I mentioned the fleet versus carrier examples before. None of that is in an SSE because so you're gonna look at it and you're gonna go, wow, check that out. Okay, this is interesting. For some reason, you know, I can sell more to companies that have their own fleets. Why is that? But at least you identify these patterns. So it's new data and so it can help your segmentation, it can help your prioritization and it can help your territory alignment because you have a better idea of who's qualified, who best fits the look alike with your best customer or your worst customer.
I just love it. It's just, it's really good. I loved when I first started seeing this data because to the point that you've made. So we do segmentation work with our clients and the firmographic data, it's sketchy, it's hard to put together, it can take weeks. We've brought teams of people and we get through it. But prior to the data we have now, we've brought teams in into our design center here at Sales Globe to just work through the segmentation, get the firmographic data properly appended to their clients or their customers. It's tough. I have a couple of questions that have come in. We actually have a lot, but we'll take a couple. The first one is when you look for other data sources for a read on the economy, what questions do you ask to help you identify indicators other than what companies are buying? That's interesting.
While the health of the economy, what we do is we combine the data with other things that comes out there mostly from the government. And the two most useful pieces are the employment data and the retail sales data. So the employment data is available by industry, comes out every month and, and so it's the by industry. It is the change in jobs year over year is the, is the number that we like to look at and that gives us a sense. So what we're looking at in Our data is B2B spending on non payroll. You're spending it on metal, you're spending on office supplies and whatever else. The employment is what you're spending on people. And so when you look at your overall expenses as a business. You're spending on people and non people. So it completes the picture and we look for differences and gaps. And it's interesting to help you understand the psychology of businesses. What we see after every recession or any dip like we've just seen is that hiring comes back slower because a lot of companies use it as an opportunity to kind of adjust their headcount and they don't rehire. And then also industries change. So after 08, when we had the big issues there, a lot of companies didn't rehire a lot of the people. When the employment came back, it came back in new sectors like retail got hot. And so when we just had this issue and our unemployment spiked, it's because all those retail jobs that we created after the recession were easy to get rid of and the consumer spending went away. And so all the valets and all the restaurant workers and all those people, those jobs were gone. So by looking at that data, it gives you a nice sense of where are things coming back. And you know, if I'm at, if I. And it varies by industry. So if I'm a manufacturing company, I'm going before I rehire people. So if I go through this last April, May, I said I need to cut people because we're cutting capacity. So my spend on materials went down because I wasn't making it as much. My spend on payroll went down and unemployment went up in that area because I would, I was closing plans, I was furloughing workers, I was doing whatever. As I come back, first thing I start to do is I buy more materials. But I don't hire people yet because I, I want to make sure that someone's going to buy my inventory that I'm creating. And then when that, when I'm confident of that and that's why that manufacturing curve is so important. The employment curve is going to lag behind that but should come up with it in a real lasting recovery. Each of these industries, retail is different, right? I can hire people quicker. Manufacturing takes me a while to hire someone. And you know my. So retail as that comes back, you can, you, you can spring back workers pretty quickly into your stores. So that's the first one is the hiring and the second one is the retail sales. So that report comes out every month as well, just came out yesterday, usually around the 15th of the month. And you can see for the retail industry what their sales are. So that tells you the consumer activity to the retailer. And then we know about the retailers spend with the businesses behind them. So we kind of have the front door and the back door. And so we watch and we see what's going on with those. And then you have a fuller picture. So I get my non payroll spend, my payroll spend and my consumer spend. And so that's a pretty sizable picture of what's going on in the overall economy.
That's pretty fascinating. Another question, this is a good one. Moving forward. It talks about learnings. If and when there's another pandemic, what learnings from today will be instructive for tomorrow?
Good question.
Pretty broad question. Yeah, it's a good point.
Yeah, I guess it depends on what you're trying to do. I think resilience of the supply chains and the confidence that brings, I think that's a big, big one. Even the people in these supply chains were probably really concerned about if they would be able to get their products to consumers. And so I think a lot of the manufacturing slowdown was probably out of fear that they wouldn't even be able to get things in time or what would happen. So I think from a confidence level of the adaptability of supply chains, that's probably something that I don't know that people even realize it. When you look back, it's still fascinating how we were able to weather through this with product availability. It's so hard. Anyone who's worked in the supply chain realizes just how many moving parts are there and how much effort goes into all the experience and all the number crunching around how much should I build and how do I get it there and where should I put it and all this because it's just hard. And for that to be as seamless as it was, I think is one of the biggest learnings. I think another learning though is just the importance of transparency throughout the supply chain. You have to know who you're working with because a lot of companies failed because their suppliers failed. And so knowing that looking at you can judge the health of your supplier by understanding what they're buying and how they're dealing with it. And so you need to understand what's going on with the companies that you interact with the customers and the suppliers. Because if you get surprised, it can ruin your business, certainly ruin a quarter, but it can drive you right out of business. So I think the need to have this, this insight, whatever it is, you need to really understand what's going on. And then there's only so much you can do by, by your usual gut feel and having your salespeople talk to your customers all the time, you know, that's invaluable. Gives you a lot of the qualitative stuff. But there are more things that whatever we can be doing as businesses to understand our customers and our suppliers is good. And this, I think a lot of people now appreciate that a lot more. They're paying more attention.
I think you're right.
Bleeding on in the background.
That's actually great advice. Thank you for that. So I think we. Oh, Mark, we're. We're done, aren't we?
I think we're close.
We're like, close because I feel like we're taking up so much of his time. Boss is back. Do you like boss, by the way? I got to ask you if you.
Like, kind of scared me at first, but he's all right.
So I'm just going to tell quick, quick story and then we'll wrap, you know, because I know we were taking a lot of your time today, Jim. And so future of sales, Foss, our guy there, our individual, that is the future, the salesperson of the future, as Mark noted earlier. And as we were building out and thinking through the future of sales, I asked him if he could personify it. Right? So this is what happened, and we whiteboarded and made some changes, and this is what resulted. And I think it's really cool. I'm actually very proud of it. But anyway, so thank you for joining us. As we talked about opportunity today and. And in two weeks, we're going to be coming back and we're going to have Greg Johnson with us, who is also from Corterra, a Moody's data analytic company, and he is going to be talking. We're going to be getting into segmentation and territory and understanding your total addressable market. So please make sure you register for that roundtable. Check out our podcast. Mark and I got a podcast, and guess what, Jim, you're going to be on it because this is being recorded for the podcast, so I had no idea. Oh, yeah, we're being recorded. We got everything. So please be sure to check us out, Spotify, iTunes, anywhere you listen to podcasts. And be sure to talk to us about your tough sales challenge. We enjoy and appreciate that you come and spend time with us every week. We hope you enjoy it as much as we do. And thank you, Jim, again for your time and we will catch you all soon. So check out our podcast, check out our other roundtables, and we'll see you soon back at this channel.
Thanks, Jim. Thanks for joining us.
Thank you.
Thanks, everybody.
More from SalesGlobe
Sales Compensation for Results - Course 1: A Strategic View on Sales Compensation - Trailer
Freative Friday - Episode 98 - Insight in Your Hunt for The Revenue Roadmap Pt 4
Freative Friday - Episode 97 - Insight in Your Hunt for The Revenue Roadmap Pt 3