Scott Duffy: Guide To Overcoming Coronavirus, Recession, & Uncertainty, Episode 19
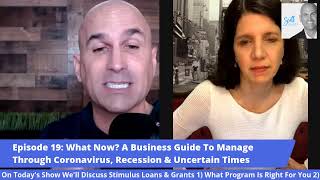
Scott Duffy and Kedma O discuss how small businesses can access government stimulus during the COVID-19 crisis, focusing on the PPP and EIDL loan programs. They cover application strategies and financial assistance available to entrepreneurs facing the pandemic shutdown.
Chapters
Good morning everybody and welcome Good morning everybody. I want to welcome you to what's now a business guide to managing through coronavirus, recession and uncertain times. And I want to thank all of you for joining this morning. And we're going to give this stream just a minute to start to propagate. We are coming to you live across Facebook, YouTube, Instagram, LinkedIn and Periscope. And so we're going to give this just a couple minutes to start to propagate across the Internet.
And I want to welcome all of you guys for joining. We have so much to talk about today. We have so much to talk about today. I am bringing back a special guest today, Kedma O. Because tomorrow is a big day. Tomorrow is the day that small businesses can apply for for protection for stimulus under that $350 billion economic stimulus plan that was passed and signed by the President last week. And overnight I was totally overwhelmed. From the time the show ended Yesterday until about 10 minutes ago, I'd received almost 700 questions from people just like you asking me for more information. They had questions about eidl, the Economic Disaster Injury Loan program as well as the ppp. And so I thought who better to answer these questions than my good friend Kedma Okedma, a former director with the sbdc, the Small Business Development Council that works side by side with the sba. Kedma's job was to go in to help businesses find funding through not only the SBA and government programs, but also grants, government grants and non government grants. Never met anyone that has been a better source of information for how small business can go and find capital. And so Kedma is going to join us today and if you're just joining us for the first time, what I'd love you to do, what I ask you to do is please drop in your name as you join the stream from wherever you're listening. If you'll drop in your name the industry you're in and the biggest challenge that you're facing today so that we can go in, I can go in and customize the this show for you. And again, so much to talk about today. If you are planning to apply for a government loan or government stimulus. I have got probably the the best resource that that we can get answers from today. KMA O and she's going to be joining us in just a minute. I want to say good morning before we start to Patrick Carney. Always good to see you my man. Jim, great to see you Todd, love to see you and thank you for joining today from from Colorado. And again, I want to thank all of you for joining across Facebook and YouTube and Instagram and Periscope and LinkedIn and and for all of you that are listening on Dash Radio. So we're going to give this just a few more seconds, and then we're going to jump right in because we have so much to talk about today.
Excuse me.
You guys ready?
So, good morning. My name is Scott Duffy, and this is what Now A business guide to managing through Coronavirus, Recession, and uncertain Times. I want to welcome you from wherever you're listening. You can tune in each day at 10am Pacific Time to watch the live broadcast on YouTube and Facebook, listen nationwide on Dash Radio, or download the podcast. Now, this show is for entrepreneurs, small businesses, and those thinking about starting their own company. It's for people who've been affected by this economy. Maybe they lost their business, their job, they were furloughed, or they saw their consulting contracts disappear like this overnight. And so they're asking, what do I do now? And how do I come out of this crisis even stronger? Our focus on today's program is going to be government stimulus. Tomorrow is the day that all of you can apply for the government's PPP program, the stimulus relief that is a part of that $350 billion stimulus package that was signed by the president last week. And so today we want to share with you everything that you need to do. In fact, I'm just going to give you a preview of what we're going to talk about today. We are going to talk about how you can apply for these programs, where to apply. We're going to talk about who can apply, what do you need to apply, what other documents you'll need to include in your application? We'll talk about. Do you need to first look at other funding before you get government funding? How long will this program last? How many loans can you take out of this program? We're going to talk about what you can use these loan funds for, what counts as payroll costs, how large can your loan be? How much of this loan can be forgiven? That's an important topic. How you can request forgiveness, and what do you need to certify in order to get these loans and these grants from the government. So we have a packed show for you today. I'm going to share with you everything I know, everything that I've learned. I've been working the phones all morning, talking to people that are tied to the sba, local lenders that are affiliates of the sba, and our friends with the sbdc. And in just a minute, I'm going to bring in Kedma O. Kedma is a former director of the sbdc, the Small Business Development Council, who works side by side with the sba. Kedma has a book called Target Funding. If you don't have it, I highly recommend you purchase it. It is from McGraw Hill. It is a guide to finding loans and finding grants, things that you didn't even know existed. Kedma, this book is a bible for me. It's kind of like a required reading that I take all of my clients through that are looking for funding. And because of her work tied to SBA and sbdc, she probably knows more about this program, these programs we're going to apply for, than anybody else today. A few things before we get started. First of all, if you are not a member of our group, I highly recommend you join. Our group is a public group and here's why you need to join it today. Throughout the day, me and my team are, we are curating, we are scouring the Internet and our resources and we are providing links and useful information that you can click on and you can apply immediately to help you and to help your business. There is so much noise out there right now. There is so much junk, there is so much distraction. What I'm trying to do is help you by taking my time to go and to find the best stuff, the real stuff, the true stuff, so that you can go right to what it is that you need. So again, I highly encourage you to join the group. And if you scroll down the group, you're going to find not only links, the links that you can click on to apply to the eidl, the Economic Injury Disaster loan offered by the government. That's that $10,000 loan package that many of you have heard about. Or the ppp, the paycheck protection program, which you can apply for today. The links are right there. I also have links to useful tools that should answer all the questions that you have about applying for these programs. You will also find in the group there are links to free programs, a ton of tech, free technology resources. If you need help using apps and technology tools right now to manage your business, there's a ton of stuff being offered by for free by tech companies. I have it all in here. Don't have to look anywhere, just go into the group. Also, jobs. If you are a person that needs to find work now, you need to find work now. You need to make that money. You need to create that kind of a sense of stability underneath you financially while going through these times. I have a list of over. I believe it's like 2 million jobs that are now open. That is in the group. And so you just scroll down, you'll find the names of the employers, how many people they're employing. And I'm adding to that list every day. So use us as a resource. Couple pieces of important news before we get started. First, last night, LA Mayor Eric Garcetti asked residents in Los Angeles, all residents, to start using face masks when they leave the house. Now, the data. The reason that he's doing that is the data suggests that so many people out there that have Coronavirus and are infected are asymptomatic. So they're not showing any symptoms, but they're infecting other people. So he's asked all of us in Los Angeles to start using a mask. Now, he does not want you to use an N95 mask. He doesn't want you to use a doctor's surgical mask. Instead, he's asking you for you to put cloth over your nose and your mouth. So that could be in the form of a bandana, a short. A torn piece of cloth. So for all of us that are here in la, anyone in Southern California, I wanted to share the news also. All we have heard this for the last month is about Zoom. Zoom, Zoom, Zoom. Here's the thing. I love Zoom. I've been using Zoom since there was a Zoom, right? I've been using Zoom. In fact, I've said on this show that I think. I've joked around that I think it was in China that that's where Coronavirus came from. I think it was Zoom, because they probably benefited more than anybody else from what's going on. But here's the thing. Zoom shares took a total nosedive today. And let me tell you what happened. Zoom has gone. Think about this. Think about this. For you, as a business owner, how would you manage this? Zoom has gone from 10 million daily users in December to 200 million in March. 10 million to 200 million. Think about that. Think about what you need to do inside of a company growing at that speed, growing that fast, in order to get yourself up to be able to support that kind of growth. Well, as a result, Zoom has been chasing. You know, they. They've been trying to catch up. And you've heard a lot in the past two weeks about security lapses related to Zoom. You've heard about Zoom bombs as an example, where people are actually. They're getting into Zoom broadcasts. They're taking them over and they're either running pornography or, or they're doing other kinds of crazy things. So I thought that all of that was just a news story and I really thought that that was all just hype until I started to hear from people in my industry, in the training industry, that they were experiencing this stuff firsthand. And so what I want to do is I want to share with you just really quick and then we're going to drop to Kedma really quickly what you should be doing if you're running Zoom calls in order to protect yourself from a zoom bomb or having a security breach. And this is really important, super important. Here we go. Number one, don't make your classes public. Do not make your classes public. Instead, always provide a link directly to people that are going to be in the conference versus sharing, for example, that link on social media. Here's the thing, if you share that link on social media, it's really easy for you, for someone, well, because you've invited everybody to not only get in and disrupt your event, but it's also easy for hackers to see this string of numbers at the end of the URL and then just like change one or two. And now they're in one or two other public meetings. So do me a favor, do not share the link to your event in public. Also, manage your screen sharing options to host only. If your screen sharing options are not in host only, anyone else can take over and sometimes they can lock you out. So it's really important. Host only. And then finally make sure that you have the latest Zoom software. And if you have other people that are helping you to manage these events, make sure you have the latest zoom software. Because In January of 2020, Zoom deleted the ability for people to scan for meetings. They deleted the ability for scanned meetings, which is so important for privacy. I want to give a quick shout out, I want to give a quick shout out to all my buddies from USD from University of San Diego. I know a bunch of you guys have been watching and you're joining today and I really want to shout out to this group and share something that we've been doing before we drop into kedma. What I want to share is that this group, three weeks ago, this group of fraternity brothers of mine and good friends, what we did is we started a text thread and all it is is just fun and positivity and things like that. We don't talk about what's going on out there, we don't talk about the negativity. But what we do is we Lift each other up. And I highly recommend you drop into something similar. We're also doing Zoom virtual happy hours. And it's such a great opportunity to connect with each other and again, just hold each other up. I love you guys and I want to thank you all so much. And then, as promised, every day I give one idea, at least one idea of how businesses are adapting to this new economy. I live in Newport beach and Los Angeles. Right next door to me in Newport beach, in Corona del Mar, a gym owner who doesn't know how long this crisis is going to last has started to disassemble his gym. And he takes the equipment and he puts it in people's homes and sets up their own home gym. He's done this now because he has so much equipment with nearly 100 people. And then what he does is he charges for private training on, on the equipment that he's brought home and he does it through Zoom. So again, just another cool example of how people are iterating through this process. So with that, what I want to do is bring in my very special guest. And there she is right there, my good friend, Kedma O. A good virtual clap for Kedma O. So, Kedma, you have been on the front lines with the SBA and the SBDC for years now. And you are the person that I trust the most when it comes to understanding what these loans mean and what we're supposed to do in order to get the most money that we can as, as businesses. Now, this isn't just a large company, a medium sized company, a small business. This is micro businesses. This is solopreneurs, datapreneurs. This is sole proprietors. This is everyone that you're talking to eligible for these programs. So what I want to do, Kadma, is I'm trying to just scream through this stuff today, jam through it, because there's so much I'm going to go through the, the ppp, the payment, the paycheck protection program. And what I want to do is I want to highlight each part of the program. I want to then have you provide commentary on that and then answer people's questions as they come through. And I'm going to take questions from my emails and my texts and my DMS as well, and ask you for each section. Is that cool?
That's great.
Okay, awesome. Love you, Kedma. All of you who are on this thread, wherever you're watching from Facebook, YouTube, Instagram, LinkedIn, Periscope, I've got a bunch of streams open right now. I'm Going to do the best I can to ask your questions to Kedma in real time. So here we go. First, there are two different programs that we hear people applying for today. The first is the eidl, the Economic Injury Disaster Loan. And the second is the government stimulus that was passed last week and signed by President Trump. That is the PPP Paycheck Protection Program. What is the difference between the EIDL and the ppp?
Primarily, the PPP is designed for making sure we keep employees. This is the opportunity which we're going to go over on how you can go back, look at your payroll, if you were operating last year, and really see how you can gain money from the government.
To keep employees, retain employees. So it's really designed with the goal of 75% or more of that funds is set for that. The EIDL is for essentially the economic injury that was done. And a lot of confusion is, can I go for both?
One of the things we want to make sure is you absolutely can go for both. And I know Scott and I will talk about this today. Different purposes.
Yes, that's the key.
Different purposes. Right. So here's, here's my, here's my sneak thing for you, Scott, and for everyone else. Get out your profit and loss that you've done, Right. If you haven't done one, talk to Scott. Get out your profit and loss. Look at all the items that your company has been paying, figure out which one could be associated with the ppp, which we're going to cover.
And which could possibly be associated with the Eidl. Because I want to read something to you. You. Does that make sense? Yeah.
Let me just say, say one more thing to make it clear. So the eil, the Economic Injury Disaster Loan, is an existing loan. I want you to think of this like two funds. So I play out there with a lot of investors and I think of venture funds and investor funds and, and capital funds and things like that. There's two funds. The eidl, the Economic Injury Disaster Loan, was a fund that was already created before this crisis hit. It's been in effect for years, this EIDL program. And, and so the money was already there. And it was the fastest way because it was a program in place to get cash to all of us business owners. Now you can, and again, the link to the ideal program is in our group, though, you can apply for either a loan or a grant. It's the same application. It's point and click. Seriously, it's as simple as point and click. It's two pages. It takes you 10 to 15 minutes to apply for it. Do not wait. By the way, somebody just asked how do you get to the group? Go to what now? And Business Guide to Managing through.
Coronavirus Recession in Uncertain Times. Click on that link. You can search for it anywhere and it's a public group and so you can join easily. Okay, Eidl. So program exists, you can apply. It's a two page thing. It's point and click. The link is in the group. Now, when you apply, at the end of the application, it's going to ask you to put your banking information, your account number and your routing number in there. Okay, Important to know. And Ken, I'm going to ask you to give some color on this in just a second.
So what's important to know is that when you apply, you are applying. And correct me if I'm wrong, Kedma, you are applying for something. It's either with one application, a loan or a grant. The money that you get would be an advance of $10,000 on whether or not you are approved for a loan. If you're approved for the loan, that $10,000 gets converted to a loan. If not, then that money is given to you or can be given to you in the form of a grant that is forgivable because it's a grant and you don't have to pay back.
One. What am I missing?
Stipulation that's really clear. Yeah, we've got to make it clear that the language states these grants provide an emergency advance of up to 10,000. You need to be clear because you.
May not know that.
Yes, I didn't know that. Yes, Scott, up to 10,000. So if you fill out that two page document, you indicate your P. L, you indicate your COGS, they will decide.
Whether you get up to 10,000. It's right in the language.
So on this. Kenma, tell me if I'm wrong about this. So what? So I filled this out.
Yes.
And when I filled it out at the end of the document, there was. There was a. Gosh. Actually. So what happened was Kenny shared the program with me on a Saturday, this past Saturday, filled it out, we talked, we went through it together. The next morning after that program was. Was got out there that it was available, the site had crashed. And then on Wednesday, no, on Monday I got an email from the government and it said, we know that you applied for that thing, but here's a different form and we need you to apply in this form. Now the first time I filled it out, I was asked in terms of P and L and stuff like that. I actually didn't have to provide taxes. I didn't have to provide a profit and loss. You don't have to provide any of that stuff. There was a page, it was supporting documents. It was one page and it had two boxes in it. Your, I think it was like your, your sales and your cost of goods sold. That was it. That, that was it. Now when I got the second thing, the link and the link is in our group. Click on the link and apply. When I got that link, it didn't ask me for that information either. So it like Kedma, who should apply for this?
Everyone should apply for this. This is a no brainer. Scott, to your point, but I don't want people getting super excited to say, oh my God, the checks in the mail, I'm getting my 10,000 and then they get 3,500. Because everywhere the language is. I'm reading it right now. I have it in the CARES Act. It is clear. This is why I love lawyers. You just add in that one sentence, one letter up and two and it changes everything.
You know, all I do is talk to people about this stuff these days. That's it. You know, I'm, I'm on, you know, six to eight of these kinds of programs a day. I start really early. I, I read everything that I can. No one has said that to me. I, I mean, I'm so happy that you brought that out because there would be a lot of people out there that are disappointed. And, and I, yeah, I didn't know that. So thank you.
Yeah, so I'll read it to you. Eidl is a direct loan from sba. As part of the application for.
It will ask if you want to request an advance of up to 10,000.
Now, a lot of people are asking, I'm seeing this all over the place. A lot of people are asking, when would I expect to get a call? When would I expect to. Actually, the two questions. One, I was told, Kedma, correct me if I'm wrong. I was told that when you get after you apply, someone is going to be reaching out to you by phone if you. And they're going to ask you to verify your business. They're going to ask you to verify your bank account information for a deposit. They're going to ask you if you do want the money or you don't want the money. So first, is that what happens as far as you know? Second, how long would it take for them to call? And third, how long would it take to get the money?
Well, whoever came, I don't know. I haven't heard that. But let's be realistic here, okay? Let's just think about this. We have 30 million businesses registered as a small business in the US today. 99% of all businesses are businesses. Let's just be generous and say 20 million of you.
Are going to get a phone call. So are you telling me that the federal government is now going to hire, like, thousands and thousands of people who should be loan officers making this phone call? It doesn't seem realistic to me.
It sounds great, but let's just do the math. So who's going to be calling? What are they going to be saying? Because I can't even get my loan officer on the call.
So what's really important? Okay, two things. One, you held an incredibly important job in this whole ecosystem and you can't get your loan officer on the phone. So what does that tell you? So what that tells you is if you are an entrepreneur, your business, you're a business of any size and you're applying for works. Right now we're on Eidl and then we're going to switch in. The majority of our program today is going to be on the PPP. But if you apply for this up to $10,000 relief, then the challenge is.
Timing because there are. So as businesses, this is what you need to know. You need to know that this money is being made available. You need to know that you may qualify. You need to know that you may get the money. You also need to know that it's not coming today. You also need to plan ahead. You know, plan the next 30 days and anticipate that it may take you some time before you would actually get that money into your account. It's the same thing, by the way.
If you're waiting for the government stimulus check. So for anyone that's making less than $75,000 a year and the government is writing checks, and apparently they're going to have Donald Trump's signature on them, and you're going to receive those in the mail or however you receive them in the mail, a card, I don't know, you receive those checks and that's stimulus money. It starts at $1,200 and it goes up from there. Once you make $75,001, it starts to de escalate how much money you can get from that check. Once you get to $99,000 of earnings, you're not qualified for any of it, but you are qualified. If you get Qualified. Okay. For, for, for that. It doesn't mean that the money's coming today. So again, we need to be conservative and we need to plan. By the way, one more thing. Kedma, I'm sorry, there's just so much here. I have a list. I have a list. You guys shall have a list too if you don't make it today. There's no excuse of all right here I've got all of my personal. Everyone that bills me on the personal side and everyone on the business side of all of my auto pays, all my auto deducts, all of that stuff. This is a time to get your stuff together. Go through these lists. I printed out my last three months of bank statements. Anyone that was hitting, if it wasn't absolutely essential, canceled. Anyone that was important and I didn't want to get rid of, I called and renegotiated. Right. This is what you need to do. The money is not coming overnight. So protect yourself today. Kedma.
Go. So, so, so. Scott, to your point, let's be strategic. Two things every single person can do right now. Number one, you can call your lender and ask for a line of credit. That line of credit is your reserve if you need it. A lot of times business line of credit have a low percentage. Number two, to your point, you can call your credit card company right now. If you have a credit card outstanding right now for 10,000 or 20,000 that you've paid off, you can call them or even if it's not there and say, can you reduce my interest from 18% to 3% for the next few months? Use that. I'm not suggesting we ride on credit cards, but if you're that person who says, kedma, I can't wait anymore, I've got bills to pay, I've got family to feed. Step outside of this situation and go back to what you do have power over. You can ask for a line of increase. You can ask for a reduction in your interest rate for your credit cards. You are not stuck.
Waiting for this situation. We don't want you thinking that you're stuck just waiting. You can find other solutions.
So true, so true. And I apologize. I'm taking a look and reading all the questions and comments right now.
If you have a line of credit or you have money that you can pull from. I just want to share something. Yesterday, one of my credit card issuers, out of nowhere, I have paid perfectly canceled my credit card. I was really surprised. And call the money, Call the money that was owed.
What?
Yes. And I, I, for I don't want to mention their name today. I'm gonna talk to my attorney first. But I wanna, but I, I, I would. And I wouldn't do it in a malicious way. I just want people to know. So here's the thing. Here's what I want you to know about credit lines. When the market crashed in 2008, 2009, what happened was a lot of credit lines that were out there, people had available, were, were closed, and the banks called the money right away. And if you didn't have the money or said you didn't, they could go into your accounts and they could pull the money out of your accounts because of something that you had signed some paperwork somewhere that you didn't read. So if you have a credit line that you can draw off of and you think you may need to drop off it, I'm not telling you to do this, but you may want to consider pulling that cash while it's still available. Because again, what happened to me in 8, 9 is I had a, I had a credit line, a big, I had a lot of money. I went to pull it one day and it was gone. And then they wanted all the money that day. So that was number one. Number two, I had a credit card. It just surprised me. I honest to goodness, I don't know why.
I know you can't say who it is, but was it a major credit card that we would know, like a major company?
It is, it is. And there are companies out there calling cash. I mean, for. I got a call from somebody yesterday who has a loan right now. It's a small business. I know a lot of people. They have loans from Cabbage and Cabbage, which supports small businesses. Yeah, it's a, you know, it's really amazing what they do. Cabbage has furloughed its employees and now you can't, if you try and call to either change your payment terms to have them start, hit, stop hitting your account to what, whatever it is, whyever you need to change where the money is going.
It's been reported to me by other small business owners that they can't even get in to do any, any of that, any of that stuff. So it's not just, you know, the person on the street, it's these banks and these institutions. And by the way, Kedma, we gotta give.
Scott.
Did I lose you?
All right, so.
We'Ve got to give people a break today. We've got to give people a break. People are stressed out, people are tired, people are exhausted. People have a short fuse. Give people A break. By the way, I got to say this because right now we're going to go into ppp. If you are trying to get your bookkeeper or your accountant to straighten up your books because you want to apply for a loan and your books aren't good, they aren't clean right now, that's your fault. Stop yelling at your account in your bookkeeper. That's your fault. Serious.
All right.
You were giving them a break and you yelled at them.
I don't understand. All right, let's talk about the PPP right now. Okay, first of all, I'm going to read this and then Kedma, please provide color on each section.
Okay, sure.
This is straight from the Treasury.
Can I say one thing, Scott, before you kick it off, want to just reiterate for the. Because PPP is going to play into it with the Eidl, you can use it to pay business applications. Right. So if you have business obligations and you have debt, you can use it for that as well as supply chain disruption. So I wanted to just put that in the back of our mind as we get into ppp.
Awesome. If you're watching from anywhere right now and you're finding any value in this program, would you please share it? Share, share, share, share, share, share. This problem, that program. That's. That's all I ask. All right. The Paycheck Protection Program. This is the program that was created as part of the $350 billion stimulus to business. The Paycheck Protection Program. PPP authorizes up to $349 billion in forgivable loans to small businesses. Listen. To pay their employees. During the COVID 19 crisis, all terms will be the same for everyone. The loan amounts will be forgiven as long as the loan proceeds are used to cover. Here we go. Kedma. Payroll costs. Most mortgage interest, rent and utility costs. Here's the thing. Over the eight week period after the loan is made, does that mean you have to spend all this money in eight weeks?
That's how I read it. That it has to be within the eight weeks and anything you don't spend gets transferred as a loan.
So anything you spend gets transferred to you as a loan employee and compensation levels need to be maintained. So this.
Absolutely.
So you can't let people go or have to bring people back. Is that how this works?
And specifically the way I read it is maintained full time employees. If there's a reduction in that because they're going to look at that, that's going to affect as well. So their goal is to really retain as much as possible employees that are considered FTEs.
Gotcha. Now, payroll casts for people. Costs for the people under this program are capped at $100,000 on an annualized basis for each employee. And it's anticipated that not more than 25% of the forgiven amount of your loan may be used for non payroll costs. So, Kedma, the way you. Does this mean that 75% of what I get from the government through this program has to be used for payroll?
Right. What it's saying is if you apply, you should apply it at a minimum, the 75% up to 100%, which is why you want to use this. If you can offer payroll and use the IDL for something that's non payroll.
So this money isn't a slush fund for people just to go. And it's not intended to do whatever it is that they want to do. The reason that this is called the PayCheck protection program, PPP is this is the government's. This is their effort to get people back to work. Now, loan payments will be deferred. So if this is converted to a loan for you, payments for the loan are deferred. You don't have to make them for six months.
That is correct. Now remember, payroll, the definition or the cost eligible are pretty broad. It's not just compensation. It's actually payment for vacation or if you have someone on medical or family leave, that also counts. Parental leave. I'm reading it right here. So it's also group health care benefits. If you're an employer who says, I want to keep the group health care benefits for my employees during this time.
That also would count as payroll, you know, Great point. So it's all the payroll costs. Sarah, this is a great point. Sarah just, just made a point. I want to throw this in there. A lot of us are getting calls right now. Everyone's getting calls right now from people that are offering to help. They have loan programs. They have. They can give you a loan. They can, whatever. Here's the thing. So much of that is fraudulent. Don't give people that you don't know personal information, especially your Social Security number over, over the phone. Doesn't matter how much you need the money. Don't do it. Don't risk it. It'll probably come back to bite you. When can you apply for these programs? Okay, listen. Starting April 3, 2020. That's tomorrow. Small businesses and sole proprietorships. Small businesses and sole proprietorships can apply for and receive these loans existing through SBA lenders. Now, we're going to talk about SBA lenders in a second. Starting next Friday, April 10, independent contractors and self employed individuals can apply for and receive these loans to cover their payroll and other certain expense through the SBA lenders. So if you are a small business or sole proprietorship, you can apply tomorrow. If you're an independent contractor and self employed individual, you can apply next Friday. Kedma, what is an SBA lender? Where do we find SBA lenders? How do we get them to answer our phone calls today?
Oh, that's a tough one. So you can find your SBA lender. There's a match lender thing. So you're going to key in right on your on on Google SBA lender in your community and at least get the paperwork. I would look at your two page paperwork, try to figure out what you can fill in. We can certainly go over that as part of this and realize that some of them just don't have the infrastructure right now to go in person. So I know they're working through what can they do online, what can they do in person. And they're probably bringing in third party support teams to help with things. I do also want to make sure, Scott, because you brought up the loan thing, if people are calling you, I agree with Scott, do not do that. There are city and state funds that you can get.0% interest or grants. Those you should go after. But if you're getting any. Yeah.
So before I go to where I apply for this, actually what I'm going to do is we're going to talk about now we talked about when to apply, we've talked about where to apply. By the way, if you look in our group, join our group. If you look in our private Facebook group what Now? A Business Guide to Manage through Coronavirus Recession in Uncertain Times on on Facebook. If you join the group, it's a public group, you can go down and there is a link to SBA.com.gov so you can see a list of the certified SBA lenders. So important you need a certified SBA lender to process this program. For those of you who don't know, the government doesn't issue the loan. The certified SBA lender, there's 3,000 of them in the United States. The certified SBA lender is the one that issues the loan. My understanding is US bank actually issues more SBA loans than any other bank in the United States. The government, the SBA will back up the loan in case somebody defaults on that loan. That's really? How, how all of that works, by the way, for everyone listening again, I keep getting this question. What now? A Business Guide to Manage through Coronavirus, Recession and Uncertain Times. That's the name of the group on Facebook. If you type me, Scott Duffy, you type my name. It comes up. It comes up. Also if you want to access.
Yes, quick clarify Fine. Question on who is eligible. Some of you listening right now have multiple locations. Maybe your massage therapists, maybe your spa services. Here's the language. Businesses with more than one physical location can qualify as long as the combined employees are below 500 employees. So again, if you have multiple, they're going to look at your entire company, they're going to add all that and as long as you're under 500 employees, you're going to qualify for the.
For as long as you're under 500 employees for all locations combined.
Correct.
Okay, got it. Who could apply? Who could apply for this? All businesses, including nonprofits, veterans organizations, tribal businesses, sole proprietorships, self employed individuals and independent contractors with 500 or fewer employers can, can apply.
Businesses in certain industries can have more than 500 employees if they meet applicable SBA employee size standards. For these industries, you can look in our group. There's a link to find out if you meet those particular, those particular standards. Kenma, right here.
Wait, Scott, one more, one more add in to that. It's so important. I used to as part of the sbdc, I was the national chair for our franchise initiative.
Wow.
SBA will allow. This is incredible. If you are part of a franchise, if you're working with a parent company, if you're a franchisee, this is unheard of. They will approve franchises that are registered through the SBA franchise director, which is almost every franchise.
Wow.
Because every franchise has to go through an fdd. They have to get approved. If they want to get a French franchisee in place, they have to work with SBA lending. So if you're part of any kind of franchise, this is insane that you're also added to this opportunity.
That's amazing. Now what do you need to apply? You will need to complete the Paycheck Protection program loan application. By the way, the link is in our group. It's in our group. And submit the application with the required documentation to an approved lender like we just talked about, that's available to process your loan app. Now these loan apps have to be processed by June 30. Two things on top of that, Kedma, then I'm going to kick it back to you.
Yeah.
Oops just lost your voice.
There it's. There it is. So here's if you're trying to call the SBA line a government line and you can't get through, what you may want to do is hit two for Spanish. My understanding is the wait times are a fraction of what the other wait times are. If you speak Spanish, that's kind of a hack.
Yes. Jason, I will share a link to the group here. Kedma, is there a concern about the 377B running out and not being available to our businesses? There are people out there that are really nervous that their SBA lenders are going to be so overwhelmed that it's going to be so low to slow to submit their apps that they won't be able to get access to this pool of money.
I will tell you this. What I have read is that they did indicate in language there's a cap. What that tells me is that we don't want to be sitting on something three months from now listening to you, listening to the information. And look, there's, there's a cap on what.
It actually says that the money. There is a cap. Like there's only so much that they're giving away. If they exceed the 350 billion.
And you're like, number, you know, 70 million for getting the application, you're not going to probably get the funds. Right. They just, that's the cap. Right. They're giving that money away up to a certain amount. What if, Scott, they exceed that amount?
Sure. Okay. So I listened, I listened to the Treasury Secretary Mnuchin on.
He was on CNBC with Jim Cramer yesterday morning when they, I believe was yesterday morning. It's all blending together when they released this final draft of the program. And what he said, what, what, what the Treasury Secretary said was if we hit that $350 billion, they will go right back to it. So I don't.
Perfect.
Yeah. I do not expect if it. When they reach 50 for them to stop lending a small business at all. He was, he was very, very adamant and convincing on that. By the way, if you're on Facebook, I just shared a link to the group. The domain for it, by the way, is facebook.com group Scott Duffy, what to do now. Al Manfrey, great to see you. By the way, Al does my trust and my wills and my, my powers of attorney and stuff.
Hello.
You are. This is a great time. If you are doing, you're doing all of your financial stuff right now. All of your financial stuff, this is a great time to have A to have all that stuff updated. Just wanted to give a shout out to Al. Also, there were a couple other questions here.
Kedma, we have a user who's, who's started a solar company in Orange county in San Diego, and they've been bootstrapping and withholding paychecks from themselves in order to take on any debt liability. Do they need to have a history of paying themselves and actually taking the money in order to qualify for the ppp?
That's I, that's a tough question because the question I have is that on their, in their records, is it a loan that they've lend, you know, did they sort of loan out the money to their business.
Where the business is owes them all this payroll? You know what I mean? So I think that that is a really. That's a complicated one. I don't have the answer right now, but I would be curious to know, you know, they're not taking the money, but did they set it up where the company owes them that payroll?
So Kedma lets you and me commit to finding the answer to this question.
Yeah.
Okay. Kevin and I are going to track that down for you. That is a great question. I really appreciate asking that question, Bob. Great to see. Bob Strobel, I see here that Kabbage pulled a $49,000 loan. Yep. That's what's happening again, in case. Where you may have the money available to you and then the banker, the one at the lender needs that cash and they're cutting off the lines.
Let me see here.
So are we recommending then that we have them pull their line of credit before it gets pulled? What, what was, what's your thoughts on that?
So what, what I, all I can do is speak from my own personal experience. My own personal experience is whether it is a credit card issuer or it is a, or it's a, it's a line of credit or it's a loan where you haven't drawn down all of the money that could be lent to you.
Whether it could be a working capital loan, if there's money available, I would not be surprised because it's happened to me personally. If that money gets cut off, if the, if the bank or the issuer, the lender decides that that money is no longer available and may even call, say, hey, everything that you owed, even though you were on a payment plan and you were doing it perfectly and it's not due. Right. Wasn't due yesterday, it's due today. So they shut down the line and they say everything that's outstanding is payable. So if you have access to those types of things and you're thinking about taking it out, it may just be something that you. That you want to take a look at.
Yeah.
And again, Bob, to be clear, Bob Strobel does not owe $49,000. It's just the capability, the capacity is what got pulled. So I just wanted to make that clear.
A quick comment to the question on the payroll thing. I just want to read the language that's coming out for lenders and how they should do their underwriting. It is stating that the, that the lenders must verify that not only was a bar in operation on February 15, but they would have to verify that the bar had employees, which could include them for whom the bar paid salaries and payroll taxes. In other words, the loan officer has to verify the dollar amount of average monthly payroll cost in order for this to be executed. And if the boss, if the loan officer can't verify that.
That may be very hard for the person who hasn't paid themselves.
Gotcha. Gotcha. Yeah, that's very helpful. And we'll dig into that more. We'll definitely dig into that more. But that's really helpful right there. Kedma, do I need to first look for other funds before applying to this program? I know with certain programs you have to go and you have to look for funds elsewhere. And then in a government program could be the last resort. The answer is no. They're waiving the usual SBA requirements to do that. How long will this program last? It's open until June 30th and there is a funding cap and lenders need time to process your loan. But like I said, the Secretary of the treasury was on the phone or on with Jim the other day and he said if they ran out, they would, they would go.
That's what I was referring to. The funding cap.
Gotcha. What can you use these funds, loans, funds for again? Super important. Four things. There's four things they want you to use these funds for. Number one, payroll costs, including benefits. Number two, interest on mortgage obligations incurred before February 15th. Three, rent under lease agreements enforced before February 15th, and four, utilities for which service began before February 15th. What you're going to need to be prepared to do is show your payroll costs, your interest on mortgage costs, your rent costs, and your utility costs before February 15th. This is what the government is going to need. Now, what counts as payroll costs? What counts? Salary, wages, commissions or tips. Employee benefits, including cost for vacation, parental, family, medical or sick leave. State and local Taxes assessed on compensation. And for a sole proprietor. Listen to this. If you're a sole proprietor or you're an independent contractor, this is what counts as a payroll cost. Wages, commissions, income. Hear that? Income or net earnings from self employment capped at $100,000 on an annualized basis for.
Kedma. What does that mean? What does that really mean to somebody that's self employed?
Okay, repeat that part on me because.
I was, I saw you were reading another part of it and I was.
Reading the paycheck thing. Yeah.
Yep. Okay. For a sole proprietor or an independent contractor, what counts as a payroll cost is wages, commissions, income or net earnings from self employment.
Yep. Right, your net income.
So basically, if you're an independent contractor, you say you're your own employee as part of this. Is that what you do?
Yeah, I think it's going to be interesting because as we know, sole proprietors or Single Member LLCs, depending on how your state looks at it, they get, they do an owner's draw.
Really?
Not putting themselves on payroll. No, they do an owner's draw. So I would presume, again, we have to just clarify this because I work with a lot of companies that don't have themselves on payroll. They just, you know, they're going from that net earnings. Maybe that's where they're looking and saying, you know what? My net earnings for this month was $5,000 and I'm withdrawing 3,000 and putting that into my personal account for, for my wages. Right, but it's not in wages, it's an owner's draw. So we will have to clarify that.
Okay, so that's something that we're going to commit to. We're going to go back in and we're going to clarify that. You know, I have, I have asked this question. I've reached out to several lenders. I actually even went, I mean, I'm trying so hard to get the information for you guys. I went because I was told that US bank was the biggest SBA lender in the country. I went to an SB US bank branch yesterday to ask somebody for help on this and they were still sorting through all of this information. So again, if the answers aren't clear, I can promise over the next few days they will, they'll become more clear. Okay. How large can your loan be? Loans can be for up to two months of your average monthly payroll costs from the last year. Two months of your average monthly payroll cost for the last year, plus add to that an additional 25% of that amount. That amount is subject to a $10 million cap. Now, if you're a seasonal or new business, you will use different applicable time periods for your calculation. And if you're wondering what those are, just go into our group, take a look in the group and you'll see it there. So I have a link to all this stuff in the notes. Everything that we're working off of is in the group. Kedma, I keep getting so many questions all over here on my screens about people wanting to know if an owner's draw is going to count as payroll.
I better hope it does because if you look at the majority of businesses who are sold prop, they take an owner's draw.
That's right. So what we'll do is, is we will work on that today and that's going to be the first thing that I want to address tomorrow.
I think that's so important to just get clarity.
Yeah, I'll go back to the bank today too and I'll. I'll see if anyone there has any more information. How much of your loan can be forgiven. You will owe money when your loan is due if you use the amount for anything other than than payroll costs, mortgage interest, rent and utility payments over the eight weeks after getting the loan. So they want you to use that money on those four way? Yes, four things for eight weeks. If you don't, anything less gets converted to a loan.
It's anticipated that no more than 25% of the forgiven amount may be for non payroll costs.
Correct.
So with this money, the government wants you to spend 75%, at least 75% of the loan that you get on hiring or rehiring people. If you don't spend 75% or more on hiring or rehiring people, then what they're going to ask you is, is they're going to convert this to a loan, whatever is remaining and it's not going to be there. A portion of it's not going to be forgivable.
I have a question on that and I need clarification. I know that they reduced it to.05%, which is amazing.
Yep.
However, my understanding is I need to confirm whether that's.05% of that loan remaining outside of the forgivable is for the duration of it or after one year. Does that convert to 4%? Because I'm getting two different information. So what, what do you. Have you heard anything on that?
Yeah, 0.5. So I. The 4%.05. Yeah. So that is 0.5. Yeah, I'm looking at it now. So my interest Rate would be.
Yeah, 0.5.
Sorry, 0.5 fixed rate. All payments are deferred for six months. However.
Yep.
Interest will continue to accrue over this. Accrue over this period. And it's not a four year loan like we'd originally heard. Your loan Is due in two years. So it is a 0.5% fixed interest rate loan deferred for six months, but interest will accrue during that period and the loan is due in two years. If you pay early, there's no prepayment penalty. Really important to note there is no collateral required for these loans and there's no personal guarantee required for these loans. No collateral and no personal guarantee required for this loan. And Kedma, I want to ask you a question. So when it comes to loan forgiveness, I see three things that are going to impact loan forgiveness and I want to tell you if I'm missing anything. Okay. So the first is the number of staff. So the loan. Your loan forgiveness will be reduced if you decrease your full time employee headcount. So if you correct.
This is really tough for many businesses because they're being asked to bring people back to work. But sales may not be increasing. So what are you going to? What? You know, kind of what are you going to. There's other things that you need in order to run your business. So it may be really difficult for businesses to, to, you know, maintain their full headcount with this loan. They may have to use it for non payroll expenses in order to keep the lights on the level of payroll. Your loan forgiveness will be reduced if you decrease salaries and wages by more than 25% for an employee that made less than 75% annualized in 2019. So they don't even want you to reduce what people make even if you don't have any sales coming in. Is that correct?
Because. Because they're giving you the money to cover it.
Because they're giving you the money, right?
They're giving you the money to cover it. And let's just be really honest. I mean really, the goal is, is once we can lift from this experience, I really believe it's going to change business. But people want to do business. People want, look, I'm dying to go to my hair salon. I'm trying to go back for my nails.
Sure.
You know, I think that what you have to do is you have to create a projected budget of what it looks like for the next 90 days with the PPP money coming in and then look at those the next six months after that. How you're going to scale your company, right?
Exactly.
That's what they want.
Exactly, exactly.
What do you need to certify? So I want to hit this really quick. We only have a couple of minutes left.
What do you need to certify? So here's what I have and if you could add some color to this. You need to show in certifying good faith that you have current economic uncertainty that makes the loan necessary to support your ongoing operations. That.
The funds. Kedma, I lost your camera. That the funds will be used to retain workers and maintain payroll or to make mortgage, lease and utility and payments that you have not and will not receive another loan under this program. I want to talk to you about that. You will provide to the lender the documentation that verifies. You have to verify the number of full time equivalent employees on payroll and the dollar amounts of payroll costs, covered mortgage interest payments, covered rent payments and covered utilities for the eight weeks after getting the loan. And then loan forgiveness will be provided for the sum of the documented payroll costs, covered mortgage and all that stuff. So here's the thing. What they want to do, I'm going to bring you back. What they want to do is they want to give you a loan. For those four things. They want you to spend at least 75% of the loan on payroll. They want you to spend the other 25% on your mortgage interest, your rent and on your utilities. And maybe there's a little bit left over. What you're going to have to do is you're going to have to go back and you're going to have one month, or I'm sorry, one year to go back to your lender again. You have to, you're supposed to spend all of that stimulus money over an eight week period and then they are requesting that you go back to your lender. You go back to your lender and you certify the things that I just shared, you show them, you say I said these were my payroll costs. And then you show them these were in fact my payroll cost. This is what I paid in payroll. You said this is what your utility costs were. And you go back and you show this is what I paid for utilities. So for those four things you just have to show that what you certified up front was true and accurate. Am I missing anything on that, Kedma?
Absolutely not. That's exactly it.
Last thing I want to talk about real quick here is even though we spent all this time on PPP, because this is what's available starting tomorrow, there are so many other places right now to find loans and grants. This you are like the Yoda of finding loan and grant money that people never knew existed. I never met anybody that was so amazing at finding grant money than you. And for business and small business, how do we do it? Can you spend a couple minutes and share with people how you do it? Maybe give them some specific searches they can do right now online.
To find right now, first thing you need to do is realize that the keywords you key in are so important. So go on right now. First we would start with COVID 19 small business grants Los Angeles.
You can then Change it to COVID 19 small business grants and indicate or small business loans Los Angeles that one keyword can make a difference. I was working with a client today. We had to go through six or seven keywords to get what we wanted. The first keyword didn't work. The second.
Actually worked for us. And what we identified is we identified two grants. One of them was up to $25,000 grants that they were eligible for. But here's the catch.
The grant closed four and a half hours after releasing because they had over 160 applicants. The second grant closed four days ago. And so I want you to go on key in your city, then key in your state and then key in a variable so you can.
Oh, we lost Kedma. So what she was, she'll hop back in. But what, what Kedma was saying is that there are so many grants that are available. Loans and grants that have been recently started, formed, approved, whatever it is. And the best way to find access to find these things, the best way to find these things is, is to. And here she comes. Is to get on Google every morning because these things become available every day and they end up getting taken. All of the money gets taken out really quickly. So like Kedma was saying, a new grant came open or a new loan.
In four hours they had already distributed all the money. We're back Kedma. And so what you need to do is do a Google search like kedma shared. The keywords that you use are incredibly important and be really specific. Do it by location and do it by niche. As an example, I live in Los Angeles. So Kedma told me to go, you know, how do we start?
COVID19 COVID19 Small Business Grants Small Business Los Angeles.
COVID19 Small Business Grants Your city. COVID19 Small Business Grants, your county. COVID19 Small Business Grants,. Your industry.
COVID19 Small Business Grants, your whatever makes you unique, your ethnicity, your gender.
I'm going to give you a tip Scott, right now for everyone who doesn't know Verizon has funding right now, get on to Verizon. They're giving grants of up to $10,000. But here's the catch. Number one, they're going to go after entrepreneurs of color. They're going to go after women owned businesses and go after businesses in historically under underserved communities. If you're a woman, if you associate in any kind of entrepreneurs of color, get there today. $10,000 grant, Verizon funding. Okay. That's the kind of niche we're talking about.
Amazing. So Kidma, how can people reach you? I'm going to put this in, in the, in the comments on all the different stuff I'm going to put in the comments. How can Kedma or how can people reach you if they need one on one support, getting themselves ready and helping to do all this stuff Right. And, and, and, and, and before you give that information because that's where we're going to wrap Ginger and so many people in the stream are asking the same question and the question is regarding owner draw and how that affects ppp. Someone just applied for the Verizon thing. That's what we're talking about. So here's the thing. On owner draw it is not entirely clear. I went to the biggest lender, what I'm told is the biggest lender in the country for the SBA US bank and tried to find somebody that could answer the question for me yesterday. And I'm going to go. It's still some of these things are a little unclear. I'm going to go back today and Kedma is going to reach out to her resources so that we can get an answer for you. Everyone wants to know this so we are, I promise you that we're working on this. Kedma, how can people find you?
How can people find you? Kedma?
I lost her. Kedma, can you hear me? Okay, if you are looking for Kedma here's what I'm going to have you do. I'm going to have you, I'm going to put Kedma's information in our screen. You did? Kedma, how can people find you?
All right, so again we lost Kedma there. So what I'm going to do is I'm just going to give you her information. You can obviously go find Kedma. O K E D M A O U G H Kedma O On.
Social media you can also email kedma at kedmakedmadma o k e d m a ough.com kdmaedma o.com I want to thank all of you guys for joining from wherever you're watching or listening today. YouTube, Facebook, Instagram, LinkedIn, Periscope. I want to thank all of you for joining. And for those of you listening on Dash Radio, if you'd like to listen again, make sure to download the podcast every single day. You can find it on Apple and itunes and all those different places. Again, I want to thank you so much. If you have any more questions today, please drop them in the stream. We'll use them to help customize the show for tomorrow. Make sure that you get out there and you fill out these applications and you get yourself in line to be eligible to receive money from the government as part of these loan and grant relief programs. Go out there and be scrappy and find grant programs like Kedma shared with you by doing some really creative Google searches out there. And also if you're looking for help, if you need help redesigning your business, you need to reorganize, you need to replan your business, you need help really thinking about how to adapt and iterate in this market, reach out to me. You can hit me up on social media, shoot me a DM or you can email me@connectcott Duffy.com I look forward to seeing you guys tomorrow. Have an amazing day. We're on every day from 10 to 11am Pacific Time and thank you so much for joining. Take care. Bye bye.
More from Scott
Business & Burgers-Sequence Collection bracelet for National Entrepreneurship Week