Millionaire Money Saving Habits (#FIREHOUR S3, E3)
In this 2023 Fire Hour coaching session, the host (Speaker A) and co‑host Crystal walk participants through a three‑part personal‑finance and entrepreneurship framework called the “3 Hats”: Operator (trading time for money), Owner (holding an income‑producing asset) and Investor (earning without trading time). They stress the importance of building mental models and frameworks to make concepts instinctual. The bulk of the session is devoted to concrete, actionable savings habits – creating a budget, tracking inflows/outflows, cutting unnecessary expenses, automating transfers, shopping smart (price‑comparing, using coupons, buying generic or in bulk), reducing utilities, meal‑planning, using public transport or car‑pooling, paying off high‑interest debt, negotiating bills, avoiding impulse buys, buying second‑hand, and saving windfalls. Tools such as pen‑and‑paper, spreadsheets, Mint, and net‑worth calculators are recommended. The discussion then pivots to Income‑Producing Activities (IPAs), framed as “money‑making moves” and introduced via the “5 Ms” (more meetings make more money). They emphasize keeping the business “open for business,” reducing friction, leveraging marketing, social media reach, and scaling through duplication of effort. Throughout, the speakers use a conversational, motivational tone, encouraging participants to take immediate action, track their numbers, and adopt a growth mindset. The session ends with a call to dominate one’s path, set 90‑day and 18‑month goals, and share the community’s free resources.
Chapters
If you have any questions about income-producing activities, any questions about saving, any specific questions, now is the time to ask.
And if you guys have notebooks and pens so that you guys can take notes, that would help because we're going to go over— we're going to go over more details today when it comes to everything. Actionable items. But if you're driving, then you can catch the recording later if you need to take notes.
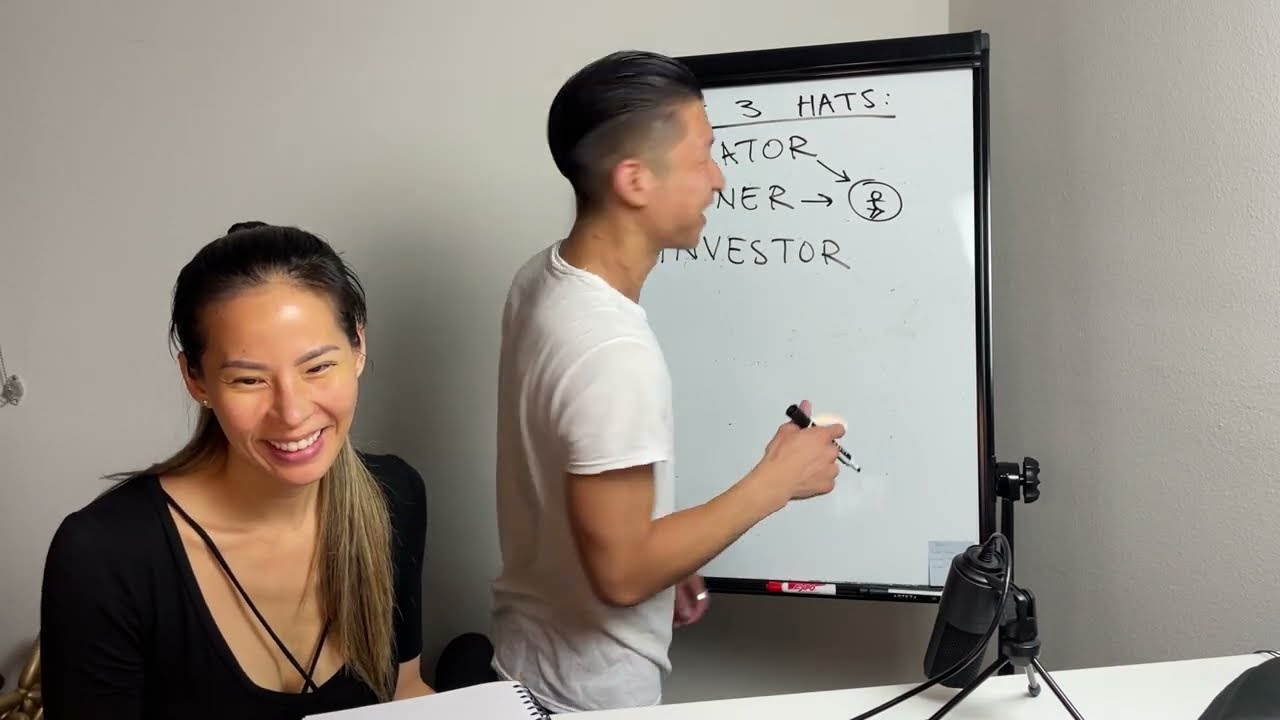
Happy Fire Hour! Let's get it. Okay, good morning, happy Fire Hour! I like that saying, it's really cool. Welcome back to Fire Hour. The goal of today's Fire Hour session, week number 3— 3 is a very powerful number— week number 3. Okay, this is Fire Hour season 3, week number 3. So there's a lot of energy today. The goal for today's call is to go over the 3 Hats. I call it the 3 Hats. It's a framework. It applies to every single person here on this call. It applies to every single person that will watch this recording. It's gonna apply to every single person who is born into this life. Okay? The 3 Hats. All right? That's edification. That's called edification. I had to edify that framework. So the 3 Hats, we're gonna talk about that. First, we're going to go into savings, okay? Savings. Because if you want to achieve a million dollars net worth, if you want to achieve $10 million, if you want to achieve however much income you want, the goal is to understand that it's a lifestyle change. We're going to go over this, okay? It's going to be instinctual. That's a— that's the whole entire thing. We need to make it instinctual so that way it's easy to do. And then the last thing is going to be income-producing activities. What And we're gonna go into detail with that. So let's start with 3 hats, okay? If you guys have any questions at any time in regards to the 3 items, okay? In regards to anything, just pop it in the chat. If it's something that we can go over on another call, then we'll do that. Okay? We're gonna go over on another call how to raise your confidence when speaking, how to network, how to build your confidence, okay? How to build yourself. We're gonna talk about that in a future fire hour. Because that was a question that was asked. So we need to do this. We're going to cover everything. Fire Hour is for you. It's to help you dominate your path. So let's get it. The 3 hats. I'm gonna move this over here, actually. The 3 hats, okay? This is what it is. Every single person, no matter where you are, you are always operating in one of these roles. In one of these positions. Okay? The first position is operator. So let's, I'm gonna just write this out, the 3 hats for your notes. And the reason, let me just share with you one thing. Always, I encourage everyone to always create frameworks. A framework is like a mental model. It's something that will help you tie a big idea into one quick sentence that will help you Boom. Understand what the idea and framework is all about. And then that way it allows you to transfer that knowledge, that, that idea into action. Okay? So creating frameworks such as the 3 Hats for this, these, this thing that we're gonna talk about right now is important. Anything that you do in your life, you always wanna create frameworks because it's gonna help you just achieve faster action, which entails and gets you to faster results. Okay, so the 3 hats: operator, owner is next, and investor. Now when it comes to these roles, okay, I'm going to share with you like a few different ideas when it comes to an operator. And this is, this is in relation to money, okay? This is in relation to money. So if you are, uh, an operator, right, a business operator, or an employee, you're trading your time for, for the money, right? As a business owner, you're also trading your time for money. So if I were to ask you a question, which one of these 3 roles, these 3 positions right here, which one does not trade their time for money? Which one, which role does not trade their time for money? Investor. Investor. Yes, in a sense, in a sense, right? Because you're not trading your time, your actual time. So the goal is to Like I said before on last Fire Hours call, the goal is to make sure that everyone ideally gets to this role right here, to investor. But can you— yeah, what, uh, need to move a little bit this way?
This way?
Yeah, to the right. Yeah, thank you. Okay, yeah, investor. Some could argue that an investor still trades their time for money. But let's just keep it simple, okay? Let's just keep the ideas very simple because we just want to get it instinctual as fast as possible. We want to get to the goal of being an investor. That's one. Now let's say, for example, you're an operator. Think of this way: an operator is someone who trades their time for money because they have to physically trade their time and work. They have to physically, like, work. That's basically what it is. So who is an operator?
Right?
An operator is a full-time employee, a part-time employee, someone who has a side hustle, someone who is working. They're, they're literally trading their time, their hours for a dollar, right? That's what an operator is. Now, when it comes to, when it comes to an owner, a business owner, they own an asset. They own something that can produce income, that can produce money. Are they trading? Is a business owner trading their time for money? It's a yes or no question. The answer is yes and no, depending on what type of business, right? So for example, if you are, if you are a business owner and you only have— it's only you, right? It's only— I don't know why I drew legs like that, but it's only you, right?
Oh, that's a person.
Yeah, it's a person. If it's only you right here, you are not a business owner. You are still a business operator. Okay, I need to break it down. Is this making sense so far? Does it make sense to you?
Yeah.
Okay. All right. Let's make you sure. I wanna keep on moving.
Okay.
Yes, yes, yes. All right. Perfect. So a business operator is still a business owner and a business owner is still a business operator. Now let's say for example, as a business owner, you're able to multiply yourself. You're able to duplicate yourself. You found, you acquired another asset. You, you found a way to find another person, right? Another employee, right? Or another operator. Guess what? Now you're solely transitioning yourself outside of the business. Okay? I need to, I feel like it's not gonna make too much sense. I really want to give just a real life example. So with the auto shop, Star Motor Works, I'm gonna, I'm gonna give you guys the, the details. In these roles of Star Motorworks, all three of us— Crystal, our partner Jeff, and, and myself— all three of us have different roles in the business. In order to make the business happen, we needed to understand three things, okay? First, if the, the deal makes sense, okay? Does it make sense? The answer is yes. Do we have an operator that can run the business for us whether we're there or not? The answer is yes. And then from there, is this asset— is this like— is this—
this is messing me up.
Is this asset, right, this business— okay, I'm just gonna put biz right here. Is this business something that we think is gonna be better in the future and not die off, basically? Because that's why you go into business. You go into business to make money, okay? You go into business to make money. A byproduct of having a business is creating impact. It's giving back to your community, is being of service, is all these benefits, the things that will help society, the help the ecosystem, the economy, right? So you basically go into business for that. Is— do we think that the business is going to do all that? The answer is yes. So we check off those. This for us, in a nutshell, for business acquisition, as long as— this is my most important thing. Is the operator good? The answer is yes. Is the business going to be better in the future, uh, than it is now? The answer is yes. And then, does the money— does it make sense for the money? The answer was yes. So that's why we decided to say yes to the acquisition. And then from there, now we talk about the 3 hats. Okay, does that make sense? This was just like a little— this is just a quick like deal flow type of thing that we do in our mind. This is like a framework for me. You know, whenever I look at a business, no matter if I'm partnering with them, if I'm consulting with them, if I'm looking to do a deal with them, if I'm looking to buy the business, whatever it may be, I always— me, me personally, I always first look at the operator. I look at the person. The reason why— I'm pretty sure you've all heard me say this before— everything rises and falls in leadership. I truly believe that everything rises and falls in leadership simply because the way that the world works Money is involved for sure, but what moves money? People. Okay, people move money. So I always look at the people first. Okay, there's another framework: the people who control the money control the people, and the people who control the people are just the managers, and then the people who control the things are the employees. Okay, so there's a framework, there's a hierarchy to everything. If you ask yourself, what position are you in? I'm going to ask you that question. Always keep thinking about that. Like, which position are you in? Operator, owner, investor? Which one are you in? Which one are you more full-time in? Which one are you more part-time in? Which one are you not even in at all and maybe you need to get in, right? So again, I always look at the people first. If the people is bad, it's no-go for me, then I don't do anything with them. I don't do any business with them. I don't network with them. I don't talk to them. I just don't do anything because it's just not in the best— it's not in the highest favor for everyone. Okay? It's not in the best favor for the money, for the business, for the economy, for everything.
Everything.
Everything.
I learned the hard way, you guys. Like, he's so good with people. There are so many times where when I was at one point I was running 5 businesses, right? Like, like Thrive was my 5th one and I was like, I need to hire help because I can't. I can't do this by myself. And I would find assistants and I'd be like, I would say all the great things about them because I always see the good in people. I always see the good in people. And I never think that certain personalities or certain things would actually lead to like something not so good. And so I would be like, oh, this person and this is what's so great about them. And he's like, immediately he's like, no. And I'm like, oh, I don't know if it's like the ego that still wants to go against that person. But for me, I think it's just I see the good in them and I feel like, you know, I'm going to just try it out. And I swear, like, how many times has it happened? At least 3. I lost time.
I am 100. I am whatever the number is and zero. Yes, I am correct 100% of the time.
Yeah, his accuracy rate is high. So looking at people is so, so, so important. Like, do you want to work with this person? Is this person going to run with you? Are they going to give you a hard time and be like that bad apple, right? Like, is, is this gonna make it easy for you? You want someone to run with, not someone to drag across the finish line. Yeah.
You actually need to, like, when it comes to being a business owner and employer, it's really in your best interest and in the employee's best interest, everyone that works in that company to, you know, all work in, in unity. Okay. There has to be synergy between all people. Otherwise it dies, okay? It goes downhill. Your business goes like this instead of like this. Imagine in your business, in your— where if you're an employee, in your office, your co-workers, all these things, wherever you work at, right? Wherever that may be. Imagine every single person in that business who is like a CEO or who is like you. Let's just say if you are the best operator, if you are the best employee, the best business owner, the best leader, the best whatever, if you just had another person like you in your business, uh, as a coworker, whatever that, that case is, whatever your position is.
Yeah.
How much better would your, your work environment be? How much better would your work environment be? How much, how much more results would you guys get? How much more fulfillment would happen? Like how would social life be at work? Right? Ask yourself these questions. If you think about it, it's about the people around you. That's all it is. When you go traveling, who are you looking like? Who do you like usually hang out with when you're traveling? If you're traveling solo, when you go meet up with someone, random strangers, and you have a good time, who are you around? It's people. Okay? Whenever you go to places, the one thing that I personally remember from all these places and experiences and travel is the people. Why? It's because the people can sometimes dictate if I have a good or bad experience. Right? It's always people, okay? Everything, wherever you go in the world, there's going to be people unless you're going into a cave where there's no people. Then guess what? All right, that's what I'm saying. So anyways, it's always about people. And one thing that I learned, um, I just, I actually just heard this like this year, which is good confirmation for me personally, but with all humility, um, there is billionaires, okay? Billionaires. Someone said this, a very like wealthy person said that a billionaire skill is people acquisition, talent acquisition. It's about spotting the right talent, right? And then from there acquiring them and, and bringing them in, like recruiting them into your business. That's what a billionaire— that's what someone said, okay? And so with that being said, if you can get good, because these are clues, okay? Success leaves clues. If these are clues and these are things that billionaires do Why not you? Even if you're an employee, you don't have aspirations to be a billionaire. It doesn't matter. Like you still have to make money no matter what. Why not get good at it now? Why not get good at it sooner than later? Right? It's better to have it and not need it than to need it and not have it. Okay? So it's important that if you're serious, especially if you're on Fire Hour transformation, it's about getting uncomfortable. It's about leveling up your skills. It's about leveling up your mindset, leveling up your life. It's all aspects of wealth, right? Guess what? We want to get good at these skills. It's skill acquisition. That's what we're going to go over in income-producing activities. And I really want to dive deep in IPAs because I'm going to share with you like things that I'm pretty sure you've never heard when it comes to income-producing activities, or at least a different frame. Okay, there's, there's a lot of things with it. But going back to the 3 hats, if you ask yourself if you're an operator, right, whether you have a business or an Okay, let's just break it down. Employees first. If you are an employee, you're an operator. Why? You're trading your time for money. Okay? If you are a business owner and you have to step into your business, you have to step into your business as a business owner, you are still an operator. Okay? You are not a full business owner, right? When it comes to investors, you are no longer stepping in to clock in. You are no longer stepping into your business to clock in to make money. What you're doing now with— as a bit— as an investor is you're assessing these things right here because you're using your money as leverage to create more time and more money. Does that make sense? So when it comes to being an investor, you have to get good at these things, ideally, right? Ideally, if you mess up with this one right here, this right here, this number one thing I'm telling you right now, chances are your success is gonna go like this. Okay? It's just from one decision. I'm giving you guys a hack right now. It's this right here. All right? There's, there's businesses out there that don't, don't need this, right? That's real. That's, that's cool, you know? But again, what moves everything? It is people. And then from there, it's also money. So get really good at this. But if you are, let's not talk about this right now. Because we want to be able to take action now, right now, in this very moment. Like, as you get this information, how can you apply it right away? We're going to talk about the next part, which is savings, okay? It's going to tie into all these things. But as an operator, right, if you have a business, if you are— if you're full-time as an employee, if you have the desire to step out from trading your time for money If you have the desire to stop trading your time for money, you need to transition into business owner. There's systems involved with that, there's people involved with that, there's talent acquisition involved, there's skill set, there's all these things that we can go over. But it's important that you understand the distinction, because even if you're a business owner, again, if you do not have— if you're not— if you're stepping into the business, then you are still an operator, okay? There's many different ways for this. So does that make sense? Okay, is there any questions about this so far? Because this is just the framework. I really want you guys to pay attention to just the framework alone because it's going to help you identify your position first, and then from there it's going to allow you to say, do I want this, right? Do I not want this? What do I want? Who do I want to be? Remember going back to session 1, week 1 of Fire Hour, it's who do you want to be to achieve your goal? You have to understand who you are. One of the, like, one of these quotes that I learned from a really wise mentor of mine, he said, most people, right? Most people in life, the least thing that they know is themselves. So there was another philosophy, uh, philosophical quote that said, know thyself. You must know thyself. Okay, if you know yourself, if you are self-aware, it's going to help you get to your goals faster. Yeah, be, do, have. It will help you get to your goals faster. Okay, so again, there's a lot more I want to cover with this, but we need to move on to, to the next part. But I just want to give you the framework again. Operator, business owner. So business operator, business owner, an investor. Okay, the goal is to be all three because we are all three at all times. But depending on which one you want to put your time into, because you're trading your time no matter what, is going to dictate, you know, how you— your lifestyle is, right? Does that make sense? Okay, um, I think that's it for that. Yeah, like there's, there's a lot more I want to go over, but, uh, I feel like, uh, this needs to be on another call for this one specifically. Okay, savings. Yeah, we're gonna go into savings. The goal with savings is to literally change your habits. If you know yourself and you know that you need to change your savings habit, your budgeting, the way that you buy things, all these different things, right? What do you— what are you like, you know, what do you need to change? How do you need to change it? Are you up— if you want to be a millionaire, are you operating as a millionaire?
Right?
There are so many different things. They talked about be, do, have. Wow, that's crazy. Let's get it.
All right, so now we're gonna go into savings, and it's going to be a little bit more detailed with actually, um, with actionable steps, right? So I'm gonna draw on there, and I'm gonna number them and kind of go down and you guys can take notes if you want to share it with someone that wasn't able to or was in the car driving. So saving savings is so important. I don't know your guys's background or money habits or any anyone that you grew up with that taught you these things. But this was basically the foundation of my life just because of the financial distress that my parents went through. Really early on I learned about savings and budgeting and cutting and keeping expenses low. And so this alone is not going to get you— you can't— I mean, you can, but you can't— like, you can save your way to a million, but it's going to take you a very, very long time on an extremely frugal budget. There's levels to it, right? But in the beginning, your foundation to be set should be revolved around savings, budgeting, and expenses, right? Cutting expenses and really getting to know yourself. Like, are you a big spender? Do you always need the newest, hottest, nicest things so you can show people what you have, right? And there's nothing wrong with having nice things. Absolutely not. If you like work for it or someone bought it for you, like, that's great. But if you have a financial goal that you are trying to reach to, then it starts with savings, right? So step 1— do you want to write for me?
All right, fine.
Do you know what I mean? Like, you can be my— what is it, you know, those games? Jeopardy? The Jeopardy?
No. Oh, teamwork. It's called teamwork.
You can be my model.
It's called teamwork.
You can be my model.
You can write for me.
Play Bean. So create a budget.
Okay, step 1 is create a budget.
Yes, create a budget. Shun White. Okay, and so when you are creating a budget, you want to track your income and expenses to understand where your money's going, and you want to allocate a specific amount for different categories and stick to it. So for example, last, last week we went over Getting to know your numbers. And one of the parts of getting to know your numbers is what is coming in every single month or every 2 weeks and what is going out. So you have your inflows and then you have your outflows and then you have your net. What are you left with? So creating a budget, it basically adds on to it. There's different categories in life, different expenses, right? You have your housing, you have your transportation, you have your food, whether that's groceries or dining out. And then you also have maybe clothes and educational expenses, or if you have kids, whole nother category, right? And so you want to know like, what is, what is your budget for each category, right? Like housing expense. This is extreme and this is how I lived. But, but before, my housing expense was probably 25%, 25% of what I was actually bringing in. If you can make it even lower on items that are the highest category expenses in the household, for example, rent, mortgage, car, transportation, right, even better. So get to know your categories of what you spend and start to apply a certain percentage to them in order to stay on track every month, right? And watch your net go grow higher. So the next thing is to cut unnecessary expenses, and I know this one can hurt when you are so used to spending a certain amount on a certain category every single day, week, or month. But when you actually start to cut expenses, this is probably the quickest way you can start to save money, right? Cutting expenses. Are there subscriptions that you have that you hardly use, and do you really need it? So when it comes to expenses, I always say need or want. If, if you just go off of the framework, do I need it or do I want it, you will be able to cut things so quickly, right? Do you need this item that you're buying? Can you live without it? Okay, so if you absolutely need it, can you get a better deal for it? Can you not do a last-minute buy? Can you purchase it in bulk? Can you— and if you're just like, well, I'm the only, only one person, so I don't purchase in bulk— can you partner up with someone that maybe has the same goal as you in savings? So cut the expenses first, reduce them, eliminate them. And it could be eating out less. Eating out is so expensive these days. And if you have an entire family, you know how quickly that can add up. Instead, buy groceries, right? And you can still buy fresh, organic, non-organic fresh groceries for a lot less than dining out. And yes, you will have to trade some of your time because you have to actually prep it and cook it, but that will actually cut a huge expense out. Dining out is really expensive these days. And so Subscriptions, eating out less, finding cheaper alternatives— those 3 things we covered, right? Do you guys have anything else to add? If you guys have comments or feedback, or you know there's something that you do that you feel like would add to it, please feel free to just comment just so everyone can see. And, um, yep, nice. So the next thing after cutting unnecessary expenses is Save automatically. So what does save automatically mean? Saving automatically means setting up a transfer from your checking into your savings account every single month before you spend it. So I'm not sure if you guys ever heard this quote before, but you always want to pay yourself first, right? So you always want to pay yourself first. So if you are saving, and sometimes you're not at a place where you could really pay yourself first, meaning take money immediately out of your paycheck, throw it into savings and not touch it. And that's okay. But what we're doing is we are working towards that. If you can't do that right now, but if you can and you see how much you save every month, once you start to measure, right, because you cannot manage what you cannot measure. So start to measure your numbers so you can actually understand how far you are actually getting and how much you are starting to accumulate and make it a game. Make it a game for yourself. People usually like to play games, right? Make it a game for yourself. Can you do better next month, and can you do better the month after that, right? And on some months when you slip, it's okay. So for example, sometimes I would spend more on dining in a certain month than my budget— than I put in for my budget. Well, the next month, whatever I went over the last month, I cut it the next month.. And because I saw my numbers and I knew I went over budget, I was like, hey, I went over $200, for example, last month. So this, this new month starting out, I get $200 less. And because I measured it, because it's fresh in my mind, I'm more mindful, right? And so saving, if you can save $100, $200, etc. Have an automatic transfer from your checking to your savings every single month. So every single month it naturally happens, and so you get so used to that habit. Um, the next thing is shopping smart. Shopping smart. Okay, and let me reiterate, when it comes to savings You want to have honestly 6 months to 12 months of expenses saved. 6 to 12 months of expenses saved. Because if anything was to happen to your employment or to your business, you want to make sure you had enough money in your savings to cover you for however many months that you needed to find another job or to figure out what problem was in your business that you need to fix. So I cannot stress savings enough. 6 to 12 is honestly how much most people need. But if you don't have that, it's okay. You start somewhere. You can start with a month. You can start with a month and then work your way up to 3, and then be in the 3 to 6 category. But once you start to establish these habits, it's going to get easier and easier. So the next thing is shop smart, right? So you always want to compare prices, use coupons if you have, buy things when they're on sale. If you know this is a household staple that you need every single month, why not stock up on it when it's actually at the lowest? Or why not shop in bulk and just, you know, purchase it in bulk and just have it stored somewhere? If this is something that you constantly need, like, you don't want to keep running to the store to buy that one thing you didn't prepare for, because you guys know how it goes. You walk into a store for one thing and you come out with a whole cart or two armfuls. And one of the hacks that I use sometimes is I don't get a basket or a cart if I know that I messed up and I forgot something and I need to go to the store. I am like, I only need this one thing, so I'm not using a cart, I'm not using a basket. But still I end up kind of like juggling things out, but at least I make it harder for myself, right? Yes. Downloading budget apps. There are budget apps out there these days to like notify you if you set a certain budget and you're starting to go over, right? Like if we have apps pinging us all the time, why not have a budget app pinging us, letting us know that there's a certain budget we set and we're now over it? Yeah. Don't go to Target.
One thing I want to add to is that If you notice, you know, you, you said that, yeah, you are trying to make it harder for you.
Yeah.
To buy more.
Yeah.
Right. In your life, if you think about it, how easy is it for you to buy something? Literally pull up your phone, right? Pull up your phone and order. So if you do your best to start to create fric— if especially if your goal is to save, right? Because it's about saving, budgeting habits, right? It's changing your habits to change your lifestyle. If you decide to get better at saving, get better at budgeting, cutting expenses, all these things, make it as hard as you possibly can for yourself. Yeah, to buy something automatically, you'll start to see like, okay, I'm not spending more. It's that simple.
Yep. Needs and wants. Do you need it or do you want it? And if you absolutely need it, can you get it for less? Can you wait for the next sale? Can you buy it in bulk? Can you buy generic? So there is a thing called name brand and generic. Why do people pay more for name brand when the ingredients and the percentage of whatever is in there, it's the same exact thing? And some of these generic products from stores, they actually outsource the items from those name brands. So those name brands basically sell it to the stores. The stores package and relabel in their own name, in their own brand. Most of the time the generic stuff will be next to the name brand thing. The only thing you're paying paying for most of the time with name brands, even though it's the same product repackaged, is the marketing. You're basically like, here you go, here's your marketing expense, here's my contribution to your marketing expense so you can market it to me to tell me why your product is better and why I should spend more. So for certain things, generic is just as good as name brand, right? So that's shopping smart. Uh, the next item is reducing utility usage. Oh my goodness, I can tell you guys stories for days about this one, just because back in the days when my parents had to watch our budget and our savings, it was like this. So when it gets hot, what do you guys do when it gets hot in your home? What do you guys do? Tell me what you guys do. You turn on the air conditioning, you turn on the air conditioning, right? You turn on the air conditioning, you turn on the fan, you have it like it's winter, like it's winter inside your house even though it's summer. Okay, so no, that was not allowed. I always thought that— I always thought that our air conditioning or our heating unit was broken growing up because we were not allowed to use it. Like, you were— you were not allowed to use it. If you used it, you got in such big trouble. I didn't even know how to turn it But reducing your utility expenses is one really good way and good habit, again, to get yourself uncomfortable. So if my brother and I was hot, it was like, go wear your bathing suit, go outside to the backyard and hose yourself down and then just walk back in. Like we were not allowed to use the air conditioning or a fan because what does that use? Electricity. It uses electricity and electricity costs money. So the next thing was also heat. In the winter, you would think, you would, you would think in the winter, hey, it's cold, we are cold, you know, can we turn on the heater? Can we turn on, maybe, maybe we can't use the whole house heater, but can we turn on like those little small plug-in ones? No, go put on a sweater. But I have a sweater. Go put on a jacket over that sweater. But I already have a jacket over that sweater. Well, what are you wearing underneath? Are you wearing a tank top? Are you wearing two shirts, a long sleeve, a short sleeve, a sweater, a jacket, a scarf, like mittens, a hat, double socks? Like, no. Like, my parents were like, absolutely not. Like, you cannot turn on the air conditioning, you cannot turn on the heat because that takes money. And there are other ways that you can do things to save money but still be just as effective. So Reducing your utility expenses will help you save, and it's those little things that really add up, because when you are at a place that you're really trying to save and get towards somewhere, you're just going to do all these things that are going to make you extremely uncomfortable. But as soon as you start doing all these things that make you extremely uncomfortable, you raise your tolerance, right? Because you're constantly going out of your comfort zone, and then you do hit your goal. You do hit your goal. So the next thing is, I just, I just had to talk about that because it's just been, it's just been so long since I've been trying to get that out since childhood. But that, those are the types of things that like my parents would, would have us do. Okay, um, planning meals, planning meals. I don't know if you guys plan meals, if you eat out, your, you know, your, your deliveries, what have you. But if you are planning meals, planning meals can save money and drastically reduce waste and costs, right? So if you meal plan, you will know that you don't have to go out last minute for this item or this item or this item, because you already planned your week ahead, got your groceries, and you know what you're eating on what day, approximately how much it is, and how many people you are feeding. So this is another thing, like my first experiences on budgeting and saving was at the grocery stores. So at the grocery stores, when my brother and I were younger, my mom would be like, hey, here's the newspaper for the grocery store. Here's what's on sale. We can pretty much only buy what's on sale, right? And this is how much we have allocated towards food. And we have to make it last because there is no more money. This is all that we have. So she would go over the newspaper with my brother and I, and we would meal plan using the groceries newspaper on items that were on sale. And then it would be like, no more than that. She would know how many pounds of veggies or fruits that we were allowed to get and make sure it wouldn't go over. Because I don't know if you've ever experienced this, but when you go over a budget or you just don't have the money, guess what you're doing in the middle of the grocery line? You're putting things back. Or you're telling, you know, the person, hey, can you take out a pound? Can you take this out? Like, we really can't afford it, right? So meal planning ahead of time, preparation will also help you save towards your goals. So using public transportation. So this is pretty extreme. I don't know how extreme you guys want to get, and how uncomfortable you guys want to get, but using public transportation or carpooling with someone, if you know someone's going the same route as you and you have to save money because gas is so expensive these days, right? Um, you could carpool, use public transportation to save on fuel and maintenance costs, or you can also lease or buy a car that's less expensive. And when you do do that, you can get electric, or you can also look at the gas usage on the car. You know, when it tells you when you're on the highway, how many miles, like how many gas, like how many miles per gallon you get, or when you're on the local streets, I don't know if you guys knew this, but when you guys are on the streets going and stopping, that actually takes more money than if you were to use the freeway. So if you can use the freeway, it actually saves gas. And these are the things that I learned from my parents too. And when you're getting close to empty, you turn off the air conditioning and put your car in neutral when you're going down the hill, that, that I used to do that too. And I would save gas like that. So there are just so many things, so many little things that, that my parents taught me that we did just to be able to save money. And when you get into those situations, not that I would ever wish for someone or anyone to ever be in those type of situations, you really learn grit like you have. All these habits that you build moving forward. So although you work to get out of those situations, if you ever were in those situations, you would immediately know what to do. So it never hurts to just practice this to get to your next goal, because most of the time we have goals. And honestly, a lot of the times those goals are tied into our finances and people don't want to talk about it. People want to just be like, this is my goal. But guess what? If you look at those goals— I want to take a vacation, you know, I want to buy something, I want to take my kids out— like everything that you have that are goals, most of the time it's tied in financially, right? So learning these little habits will save you time, money, and energy, and you will start to really build a resilience in you getting uncomfortable and doing things you've never done before. And you can teach this to someone. You can teach this to someone who needs help. You can teach this to your kids, right? Um, so number 7, Shen.
Yeah, I heard.
Yeah, use public transportation.
Yeah, it just depends on like your role though, okay? Yeah, like with the— with public transportation, like whether you're driving, whether you're taking the BART, whether you're taking the bus, whether you're taking like one— if your friend's helping you drive, whatever, right? Think about your role, okay? If you're an operator, then maybe it makes sense, and maybe it makes sense for you to, to drive yourself or to take the BART or whatever, right? Um, but again, I'm gonna tell you something. When it comes to your time, can you get your time back, right? Can you get your time back in that moment? If I'm— if person— if I'm driving and Crystal's not driving, she's on her phone, she's working, who's making money? Boom, she's making money. I'm not because I'm driving. I'm trading my time to actually drive. If you are taking transportation, Uber, Lyft, whatever, whatever transportation's out there, train, train, train, plane, there's many things. So if you're doing that, what opportunities are you missing, right? If you're, if you're able to work off your phone and you're, or on your laptop and someone else is driving for you, whether that's the train, the plane, the Uber, the BART, the Lyft, whatever. If you are able to take advantage of that time and work, if you want to, guess what? You can produce income. Does that make sense? That's where income-producing activities come into play. That's where if you are a business operator, business owner, investor, how are you allocating your time? Because you can't get time back. So how are you allocating it? Everyone has 24 hours in a day. How come the person that is making a million dollars a day and we're not— how come they're making a million dollars a day? Right? It's because of allocation of the three, the three roles. And then from there, like, how they are allocating their, their money, their investments, their time, everything— the energy, the money, the resources, etc. You have to think about that, because if you aspire to get better, if you aspire to take action, if you aspire to achieve something different, you have to become different. You have to be and step into that person that you truly need to be in order to have what you want, right? So it really depends on your goals. For me, I don't like driving unless it's like a freaking Lamborghini or sports car or i8 or whatever, just because I don't like driving the van. That's just me. But instead though, what really pains me is that I don't want to drive because I want to work, okay? I want to work. I'm literally always like working. I'm always in meetings, I'm always on the phone like messaging people, I'm always doing— I have to always be working constantly. Constantly. That's what I like to do. I enjoy working, so I don't mind doing it. When I have to drive something, like, I don't have to drive, I'm thinking about work. I'm like, damn, like, I could be working right now. How can I afford— how can I make more money to afford a driver? Because having a driver drive me is gonna make me money. Does that make sense, right? You have to think— if you're— if you aspire to make more income, you got to think differently. Be creative, have fun with it. If you enjoy driving, then drive. Like, if you enjoy something, if it's fulfilling for you, then do it, right? Don't sacrifice what you want to do because there's no point in doing that. Do what you want to do right now, okay?
But it also depends where you're at and where you can best use your time. So if you haven't found something that you can do and work off of and make money, then in the beginning, setting your foundation, you have no choice. You trade your time and you do what you have to do, right? So I used to have a personal assistant drive me around, drive my car around just so I could work off of my phone because I knew that if I was working off my phone, I was making money. But if I was just sitting there, then I wouldn't have a personal assistant, right? Because I wouldn't be able to afford one. So the next thing is paying off high-interest debts. So I don't know if you want to write down use public transportation. Pretty extreme, but I don't think it's a bad thing, right? In certain areas, you— most people typically would use public transportation. Like, for example, in New York, you would use the subway to get fast, to get somewhere faster, right? So 7 was use public transportation. 8 is pay off high-interest debt. So I don't know how many of you have credit card debt, but most of the time in America, a lot of people, they live off of their credit cards and they have credit card debt., and it's just much cheaper to pay a minimum per month than actually pay the full balance. So growing up, my parents always taught me, if you cannot pay something in full, like if you cannot pay your credit card off in full every single month, the chances are you're probably spending too much. So I know that some people, in order for them to reduce their credit card debt, what they usually do is they pay off the high-interest credit cards first. So get to know your credit cards. How many credit cards you have, look at the balances, but most importantly, look at the interest on those cards. Some cards have much higher interest than others. So you may be, you may be spending 20% just to carry that balance month over month. So you're paying 20% on your money, right? And then on top of that, you have inflation, which is now in like the double digits. So you may be paying 30% just to leverage credit card debt. Is there things that you can eliminate? Needs versus wants. And if you can't, now you're starting to save, pay off those higher interest credit cards first. Get to know your cards and get to know the rates on those cards and pay down and pay off the highest rate credit cards first. This will also help you save money because then you have access to pay off the other ones or to save. So number 9, negotiate bills. I don't know if you guys ever negotiated before, but I also learned this from my parents, and I think that if your parents did not grow up here and they were immigrants, like, negotiation is a skill that they naturally had because in other countries it's so normal to negotiate or to barter with goods instead of exchanging for money. And so I learned the value of negotiating bills. You can negotiate better rates or discounts on your bills, and you can, like, the cable, internet, or insurance, or shopping around, right? You can even negotiate with vendors that you work with. Because okay, so right now we're going— I'm going through like a roof project, right? So I got 10 different quotes in order to be able to get the best deal. So that was negotiating. And I let people know, like I let those 10 roofers know, hey, I'm getting bids right now for my association. So whoever can give me the best bid and do like, you know, quality workmanship, like that's who we're going with. And just by me doing that, I probably saved our entire community easily 6 figures. A roof is not cheap to replace. And on 10 units, it is even like, it's insane. But that was one of the ways that I negotiated a huge bill on behalf of my HOA, right? I was like getting 10 bids and letting them know, hey, like, I'm not here to like, don't think that we're not getting other quotes, we are getting other quotes. So anytime you work with a vendor, or you're working on something, get a lot of quotes, get a lot, like do the work because that little bit of work upfront will pay off in the backend. So now my association always goes to me and they're like, hey, this is what we're trying to get done. Can you, can you figure it out? Right? Can you go get a bunch of quotes and see what's the best pricing? I saved 6 figures. I saved our community freaking 6 figures just by doing that little bit of extra work. But it started with growing up as a kid and learning these habits. That actually helped me to scale my skill set in negotiating and looking for the best price and saving money, right? So that is the next thing. Avoiding impulse buys. You know, when you guys are scrolling on Instagram and those ads are hitting you, buy this, buy that, this is so cool. Avoid those impulse buys, especially late at night, or when you're in the store, you go in for one thing and then you impulse buy like 10 things, right? So avoiding impulse buys will help you drastically reduce your bill and help you in your savings more than you can— you— more than you even know, more than you even know. And the next thing is consider secondhand purchases. My very favorite, uh, growing up, again, Goodwill, Salvation Army, one piece a year, one piece a year. Because if you still had things that still fit you, it didn't matter if you're wearing it every day or every other day or cycling between them like a capsule wardrobe. And back then there no such thing as a capsule wardrobe. So it was not cool to wear the same thing every single week, right? But if you purchase something secondhand, like an electronic, something that's refurbished, or clothes, there's nothing wrong with that. You can save money that way too. So these are a couple ideas of how you can start saving immediately. These are actionable items. You don't have to do all of them. Pick one, pick two, measure the results on a monthly basis. What's coming in? What's going out? How can I reduce what what's going out, and then setting a budget, right? If you set a budget and stick to it, you are now learning discipline, right?
Yeah. Even just to add on to that too though, because there's, there's many things that like we could talk about because there's duality, right? This is saving, but in every single one of these there is money to be made as well. Okay, so, and then only that, like when it comes to, um, when it comes to what you were saying, like check monthly, My millionaire mentor, okay, he's a multimillionaire. He told me this, he said, check your money every day, check it daily. That's what he told me. And so then ever since then I'm like, okay, I gotta check it every day. Know your numbers, know your numbers, know your numbers. He always, he told me and he, he showed me, he set up a Google alert that would send an email to him every single second that his name popped up for whatever reason. Because he's checking, he's checking, he's a public figure, so he needs to know what's happening at all times. And he's always consistently checking the numbers. And that's, you know, if you have multiple businesses or multiple income streams coming in, you want to know your numbers, you want to check it, right? So just what she's saying, yeah, track.
And then saving windfalls. You know, sometimes you get a bonus at work, you get a tax refund, don't use that, don't use that, put it away and save it. It's bonus money, it's something that you would not have received. So as much as you want to spend it, Don't use it unless you're using it to pay off high-interest debt. Okay, so saving money that came that wasn't supposed to come, save it or use it to pay off high-interest debt, right? So that's pretty much it. There are so many other ways to save. People can get really creative, but I think that we covered a good amount. So 12 is save windfalls. Save windfalls, right? Things that you didn't expect, tax refunds, bonuses, You know, just save bonuses, basically. Tax refunds too. Yeah, that's a bonus. That was money you spent already that just came back, right? Um, so saving money, it takes time. It takes time. It takes discipline. And you have to go over your numbers every single month if you really have a goal. And that goal is most likely financially tied— savings, expenses— and measuring so you can actually manage A couple of tools that I use real quick. So in the beginning, when I was younger, in my teenage years, I used the paper and pen. I used the paper and pen. It's so easy, right? And if you want to upgrade, which later on I started upgrading, I used an Excel sheet, right? I started getting digital, use an Excel sheet. It was much easier to send that Excel sheet to my accountant to be able to write things off. And if you really want to use Mint, I don't know if you guys heard of it. If you guys use it, type it in the chat if you use it. But Mint is an excellent tool. Because you can attach all your bank accounts and your credit cards to it. So every single month it basically kind of sorts things and you set certain rules and it creates budgets that you can have. Well, you create your own budget and it could ping you, it can ping you and notify you if you're going over. So yes, Mint is an amazing tool. It's like the upgraded tech and it's free. It's free to use. Yeah. And again, if you guys have not did it yet, we talked about this maybe last episode, but using a net worth calculator because you want to know what your net worth now is. Now, are you in the negative? Are you in the 6 figures? Are you in the 7 figures? Are you in the multiple 7 figures? You remember I was an accidental millionaire. I had no idea of my net worth until I wanted to invest in a private equity firm to be able to leverage my money as an investor and have my money work for me. I did not know until they were like, Fill this out, send this, this to us. Understand what your net worth is. Are you in the negative and you're trying to work towards your positive? Check it every month if you want to. Check it year over year. Remember, you cannot measure what you do not manage, so get comfortable looking at your numbers. So, but what I want to say too, before we get into the IPAs, right, we're going to get a little bit and touch into the IPAs a little bit. We only have a few more minutes left, but I know I told you guys the importance of saving. Here's the next level: saving money doesn't make you money, making money makes you money. When I learned that framework, which I created myself, it completely shifted my way of seeing money and understanding it. And that is like the greatest jump that I have when I understood it, right? Like, that is actually the framework that I used to get to the next level, to get to $1 million. And then when I got to $2 million, $2 million, $2+ million net worth, the jump was like 3, 4 years because I understood that saving money doesn't make you money. Making money makes you money, right? So how can you make more money and how can you save at the same time? But how can you make more money? Are there side hustles? Are there, I don't know, things that you can work off of, off of your phone? What do you have going for you? Do you have a savings account? Is your savings account making you 5% plus? Because that's right now what the going rate is, right? Some of my funds are in a savings account that's earning over 5% on my money every single month. And so that's like lunch, right? Like every month I get a drop and I'm like, great, that's like dining out or lunch money. I don't use it. I don't spend it. I'm like, it's great to have. It's great to know it's there. It's great to know my money's working for me. But that is the next level when you want to make those leaps in your net worth.
Yes.
Yeah.
And that's a framework right there, right? Saving money doesn't make money. Making money makes money. And that's true. It's super simple. Through— they're saying through what bank?
There's a lot. You can look online. There's a lot. So Google online high yield money market savings accounts, and there's at least 3 or 4 of them out there right now. Just Google that and you'll see a bunch of them pop up. Look for wherever is offering you the highest interest rate and then start to save your money and move it over there.
Yeah, and then again, like, it's very— it's common sense, right? You can only save what you've earned. You can only save what's come— what it already came in. So doesn't it make sense if you achieve— if you want to achieve a different level of net worth, doesn't it make sense to make money, right? Make more money.
Yeah.
Figure out ways to make more money, increase your income, right? Income-producing activities. So, um, with, with savings, just to make it very intentional, out of all— there was like 12 bullet points, right?
Yeah.
Every single one of these bullet points is actionable. Let your learning lead to action. What bullet points can you implement into your, your day, into your life right now? Right now, ask yourself, what can you do? Can you do all 12 right now? Are you doing all of them already? Which ones do you need to improve? Which one can you get better at? Which ones do you need to really like decide on and talk to your, your family about? Like, what, what is it? Get serious about this stuff. This is— life is serious. That's what Jim Rohn says. Life is serious. Get serious about it, right? Guess what? It's possible. Net worth calculator. Know your numbers. Know how much you are worth to the ecosystem, to the market, to the economy, whatever, to yourself. Know that, right? Look it up. Like, just figure out a way to just know that number. Put it down. Write it down on paper right now. Date, right? August 2nd. Number— that's, that's the number one. That's the beginning. Guess what? August 2nd. Write it down, take note, take a picture, post on your story if you want. I don't, I don't know if you want to do that because that's, that's you. But like, just make sure that you're able to track it. And then a year from now, a year from now, look at it again. If nothing has improved, look at yourself. Ask yourself what needs to change. What do I need to change about myself? What do I need to do about my lifestyle? What do I need to do about making more money? What do I need to do to get things different, right? To get different things. So income-producing activities. If the baby's not awake, I'm gonna keep on going, all right? Guess what?
Sorry, that was her alarm. All right, sorry.
Income-producing activities. And like we said, we're probably gonna have to do this on another call. Yeah, because I really want to touch up on income-producing activities, because guess what income-producing activities means? Right?
Leads to money.
IPA, income-producing activities, right? Income, money, produce, making, all right? Activities, moves, money-making moves. IPAs is money-making moves.
Okay, make that up right now.
Boom! What's up? Income-producing activities, the 3 Ms. Money-making moves. Guess what? Do you guys know what the 5 Ms is? The 5 Ms, do you know what it is?
No. Did you just make that up right now?
I learned the 5 Ms from a multi-millionaire in 2013. You guys know what it is?
No, no, no idea. Teach us. Enlighten us. If you guys know, type it in the chat as fast as you can because we're about to hop off soon. But no, We're not—
yeah, anyways, income-producing activities, money-making moves. That's what it is, right? If you think about it, because income-producing activities is kind of confusing, so let's just make it simple. Money-making moves. What moves are you making to make some money, right? Money-making moves makes money. That was very creative.
That's a good one.
That was creative. So I'm going to ask you guys a question before I get to this, okay? The 5 Ms. In your business. If you have a job, in your job, okay, I'm going to talk about business, okay? If you are an employee but you're on fire hour, I know you want more. I know you desire more. I know you want to achieve more. I know you want to live a different lifestyle. I know you want to dominate your path. If you are on fire hour and you are a full-time employee, you have a side hustle, a business on the side, you're working it part-time You have multiple things, side hustles. I'm sharing with you right now, okay? I'm going to share with you right now the one question you need to ask yourself at all times, every single day. If you are a business owner, every single day you ask yourself this question. If you are an investor, you will still ask yourself this question. Are you open for business? Are you open for business? Ask yourself that question when you clock in if you are an employee. You clock in, you're trading your time for money. You are literally trading your time per hour for that dollar. Or if you're on salary, you're still trading that time for money, right? And you're actually trading a lot more time if you're on salary. Maybe. Depends, depends. It really depends on your position.
I know I was.
Yeah. So it— ask yourself the question, are you open for business? What does that mean? Okay, are you open for business? I'm gonna write down because this is a really important question to ask yourself. All right, or do you want to be my writer? Are you open for business? If the answer is yes, then that's good.
Why?
That means— okay, let's look up here— that yes equals money in. Yes equals money in. Okay, if you say no Are you open for business? No. Money not in. Okay, money is not in, right? It's just— let's keep everything simple and let's keep it fun. Ask yourself the question, okay, in your business, are you open for business? There's businesses that are open 24/7. There are business— businesses are open only 5 days a week. There are— there are— just think of your business as a door, okay? This right here is the door. Oh, the baby's up. The door. Okay, just real quick, this is the door. Is this door open for business? If your door is open, money can come in. If it's not open, then you're basically blocking everything. Okay, you have to think about this for yourself. 24— if you have a business that's open 24/7, right, such as Thrive guess what? That doesn't necessarily mean that you're making money at all times. Why? Why? How easy is it for a customer to buy? How easy is it if you have a service-based business like me, consulting? How easy is it for someone to— a client to get started with me, right? How easy is it for a customer, a client, to purchase, to do deals with you, to do business, to send you money? How easy is it? You have to ask yourself these questions because you gotta set that up. It's important to set these things up to make it easier. We're gonna, like, this is what I want to go over. I want to go over all the way, or not all the ways, but majority of the ways that will help you alleviate friction when it comes to keeping your business open for business and making money in at a faster rate. Again, why do billionaires, why do, why do people make so much money per day, the same 24 hours as us? Yet they make so much more? It's because of several different factors, right? If you ask yourself this question, are you open for business? And the answer is yes, that's money in. Guess what? Here's the 5 Ms, okay? This is direct proportion related to the businesses that we're talking about right now, uh, that for the audience that's on right now, right? Thrive, it's 24/7. Guess what though? How do you get money in? It's with the 5 Ms. Okay, the 5 Ms stand for more meetings make more money. More meetings make more money. Why is that? It's because when you have a conversation, you're having a meeting. When you are DMing people, this is an income-producing activity, money-making moves in the DMs. That's a meeting. Okay, that's a meeting right there. Why? It's because it's an opportunity for someone to walk through the door. It's an opportunity for money to come through the door. That's because your business is open. If you're going to sleep though, if you're sleeping right now and you're not talking to anybody and there's no, no system in place, are you making money, right? These are the types of things that I want to talk about when it comes to IPAs. For us, when we're not at the auto shop, are we making money? The answer is yes. Why? It's because we have assets, we have a team. We have a system in place that allows us to make money, right? The, you know, working from our phones, consulting my website, it makes— it can make money with whether I work or not. Why? It's because I can multiply myself. I already know how to duplicate myself as a leader, especially as a leader of a sales force, a sales team. How are you duplicating yourself if you just had another version of you that worked when you went to sleep, how much more money would you make, right? Guess what? When it comes to like really scaling a business— and I'm not talking for solopreneurs because there are solopreneurs that make a million dollars just by themselves, they are operators because they want to be operators, business operators— they still making a million dollars. Guess what? They enjoy their work. That's fine, that's cool. But for you, if you have a different desire to not trade your time and to start to become a business owner and then start to get into that investor category. How are you leveraging your income? How are you leveraging your time, your resources, your energy, your money, right? There's so many different ways to do it. Income-producing activities, we're going to talk about it, um, but I think we gotta get the baby, so this is gonna be— yeah, we have to talk about on next week's call. Um, week number 4 will be really diving deeper into this because I'm going to talk about branding I'm going to talk about income-producing activity. Okay, so income-producing activity, just to give you guys a teaser real quick, and then we'll go. Income-producing activities, what she was talking about in savings— why does someone spend more money on a brand versus a generic one? It's because of brand. It's because of marketing. Marketing is one of the income-producing activities. Marketing is one of the money-making moves. Marketing helps you get the more 5 Ms. Marketing helps you stay open for business. Whether when you're sleeping, right? There's so many ways to do it. And not only that, because we have such tools such as social media, we can significantly increase the amount of money that comes into the door. I posted a reel the other day, like 3 days ago, over 500,000 views. That's 500,000 opportunities for us to get money into the door. Guess what? It's possible, okay? It's so simple now. It's a lot easier to make money now than, than it was before. Literally, like, uh, 7 years ago, it was not this easy to make money online. Now, more than ever before, it's so much easier because there's so much less friction for people to buy, because psychologically, people are used to buying online now. It's so easy. You just pull up your phone, take— boom, money in, money in, money in, money in, money, money. Come on, like, what's up? It's like that simple. But are you delivering value? Okay, I want to talk about the 3 things I always look for when I buy something. I— oh my God, there's so much to talk about.
So much, so much. And I'm so excited for next week because if you guys don't know our story, we actually did not meet to date. We met for business. You know, I was always about business and I was like, I need to get to the next level. What's going to help me get to the next level is marketing and social media, which I knew nothing about, right? Like I came from a financial background. I owned financial businesses and it was brick and mortar in person. Right? So marketing was the next level and social media was the next level. So, um, our partner, our, our auto shop partner Jeff, um, who's my elementary school friend, was actually the one that introduced us for business and things just unfolded that way, right? So, um, when you have the funds to, you start to think on a different level and you start to invest in yourself, in your mind, and you start to invest invest in assets. You start to invest in the greatest assets that's going to take you to the next level. Like, I am not here just to cruise at over 2M, right? Like, I'm shooting for the next 3 to 5— 3 to 5 million net worth in the next few years, right? Who's gonna take me there?
Next few years? Next year? We can make leaps and bounds in a year.
So we'll see you guys in the next days.
No, we're not ending it yet. 90 days. All right, 90 90 days and 18 months. 90 days. I said this on the week 1, 90 days and 18 months. Those are the time frames. If you want to get to $10 million, it's possible in 90 days depending on your business model. It's possible. If you want to get to your first million, 90 days, it's possible. Okay, it's already been done, right? People are making millions of dollars a day. Guess what? Why not us? We can do it. Why not? Let's go on for the ride. If you're new to Fire Hour, Let's get this. Let's go. Okay, this is all about transformation, dominating your path, living life on your own terms. You can do it. It's possible. The community here is the strongest community. It's about helping each other out, collaboration, not competition. It's about communication and unity and everything in between. We're always doing all these things just for, for free. This is for free, okay? It's for free. Allow yourself to take advantage of the opportunity to change your life if you want to. Allow yourself to learn this knowledge, this information, and transition it into action and apply it today, right now, in this very moment. Help someone else out. If someone is fired up and inspired and they wanna have dreams and goals that they're looking to accomplish in this year, guess what? Share FireEye with them. It's, it's important. This is for everyone who wants to change their life. Okay? Let's get it. Dominate your path. You got what it takes. Now you just gotta give it all that you've got. Okay? Make it happen. Crush it, dominate your path. You got this, 100%. Don't let anyone tell you otherwise, okay? Make it happen. Let's get it. Love you all. Peace out.
I love you guys.
IPA's on the next one. Let's go.
More from Michael


Social Media Strategies for Entrepreneurs and Business Owners (#FIREHOUR S4, E41)