Securing Easy Financing for Life with Jay Conner
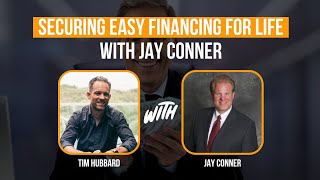
Jay Conner explains how to raise private money from individual investors for real estate deals instead of banks. He's built a network of 47 private lenders using self-directed IRAs, structures deals with secured promissory notes, and pays around 8% for short-term flip financing with no points.
Questions this video answers
February 23, 2024
47 private lenders
Over half of them
Approximately 8% with no points
Around 6–7%
Chapters
Welcome back, everyone, to the Short Term Rental Riches podcast. Happy you're here again. As always. I'm also happy because we have a fabulous guest today, Jay Connor. And as we know, before we buy a short term rental, we've got to have money from somewhere, right? But one of the beautiful things about investing in real estate is that it doesn't always have to be our money. We talk about opm, right? Other people's money. And we have some very traditional ways that we do that, of course, going to the bank. But Jay has been specializing in an alternative option for quite a long time. He's got a ton of experience. So I'm excited to jump into the topic of private lending today with Jay Connor. Welcome to the show, Jay.
Tim, thank you so much for having me. I'm so excited to be here because we're going to be talking about my most passionate topic, that being private money. And the reason I'm so passionate about it is because private money, using private money lenders to fund our deals. We got 47 of them today funding our deals. And of course, nobody's got to have 47. Start up with one or two. But it has had the biggest impact on my business of any strategy. I mean, when I was cut off from the banks all the way back in 2009 and the banks weren't lending money and all those foreclosures were coming along, our business actually tripled the first 12 months we started using private money. And I ended up with a good problem very, very quickly. I couldn't use all the private money that was chasing me. And so that's one thing that I talk about all the time, is how we get all this private money without ever asking for a mortgage, ever applying for a mortgage. No chasing, no begging, no selling, no persuading. Yeah, I'm excited to be here.
Yeah, I'm glad to have you, Jay. And private money is, in fact, something that I've used a couple times in my personal real estate portfolio. So why don't we, before maybe we get into a little bit of your background, why don't we just define for the audience what exactly is private money and how it differs from some traditional methods.
Yeah. So with private money, first of all, what it is, what it is not. So private money is. I'm not talking about any kind of institutional money. I'm not. Or institutional funding. I'm not talking about going to the bank, I'm not talking about hard lenders. A lot of people use that word synonymously with private money, hard money, private Money, they're not the same thing. Most of the time a hard money lender is a broker or is a brokerage that has gone out and raised private money from individuals, private investors, to invest in their fund. And then the hard money lender turns around and loans that money out to real estate investors and from their fund. What this world of private money is all about is going straight to the source, going straight to the individual. So a private lender is a human being, an individual, just like you and me, that's interested in real estate. But they want to be totally passive. They don't want to go find deals, negotiate deals, oversee deals, manage properties and all that stuff. They just want to sit back and get nice rates of return safely and securely. So simply put, a private lender is a person that loans money from either their investment capital and, or their retirement funds to us, the real estate entrepreneur. And the reason I say retirement funds, that's really important because of our 47 private lenders, over half of them are using retirement funds, either a 401k they already had or, or a pension, any kind of dedicated retirement funds. And they move those at my direction. They move those retirement funds to a self directed IRA company, also known as a third party custodian. And now they can lend those retirement funds out on our deals and they earn tax deferred or tax free income, depending on the type of retirement fund they've got. So that's the first actionable item if you are a real estate investor wanting to get more funding very quickly for your deals, is you want to establish a relationship with a self directed IRA company that you can then refer people to when you talk to them and you learn they have retirement funds and they can move them over. But don't be confused, it's not only just retirement funds, it can be just liquid investment capital as well that the private lender uses.
Yeah, I'm excited today because this is really timely advice. Right. Obviously interest rates have pretty much doubled, which means if we go the traditional routes with banks, which a lot of us are used to working with, our cost to borrow money is much, much higher. And that doesn't leave us with a whole lot of options. And so private money can be a great, great option. Jay, how did you, I guess you mentioned in 2008, 2009, it was kind of difficult to get in. Can you give us a little bit more of the backstory?
Sure, absolutely. And you know, you just said something important. I mean, as of today with us being here, Tim, the federal government has raised interest rates 22 times in the last 11 months. Can you believe? And in this world of private money, I haven't raised, I have. I'm not spending any more on interest than I was even before COVID And the reason is. And there's the big difference right there between hard money and private money, is that with private money, we make the rules. You know, the traditional way to borrow money is you go to the bank, you go to the hard money lender, you go to an institutional lender. You. You get on your hands and knees, you put your hands underneath your chin, you say, please fund my deal, right? And verification of income, credit score, and all that. In this world of private money that I'm talking about, there is no asking, begging, chasing. There's no, you're already approved. Your credit score has got nothing to do with it. And so here's the big difference. Instead of asking for a mortgage, you are offering a mortgage. Right? And so how did I get started in this world? Well, I can tell you, Tim, I just didn't wake up one morning and say, hey, I think I'll go raise me some private money. You know, growth, personal growth, financial growth, entrepreneurial growth. The growth takes place in the Valley. Typically, there's a problem that has come along, and you got to fix your problem, and therefore, you grow in your business or personally or all the above. Well, I remember it like it was yesterday, Tim, is how I got into this. You know, you may find it hard to believe, Tim, but we actually still have handsets here in North Carolina with cords attached to them. You know, a lot of people I know don't even know what that is.
But anyway, for those catching the video, Jay just showed a real phone, not a cell phone. A real phone has. Thanks for that, Jay.
You got it. And so I was sitting here at my desk, and I had two houses under contract that I wanted to buy. And I had been using the same banker, the Same bank from 2003 until 2009, my first six years. And that's all I knew to do, was go to the bank, borrow money for my real estate deals. That's all I knew to do. And so I picked up the phone, I called my banker. I learned very quickly on that. And that was January 2009. I called up my banker, and I learned very, very quickly that my line of credit had been shut down with no notice to me, and that they're not loaning money out. And my banker's name was Steve. I said, steve, why are you shutting me down by the way these two houses I had under contract represented over $100,000 in potential profit. And I said, steve, I got a great credit score. I've never been late on my payments in six years. Why have you closed my line of credit? He said, jay, to don't you know there's a global financial crisis going on right now? I said, no, but now I got a financial crisis because I don't have any way to fund these deals and you've cut me off. And so I hung up the phone and I sat here for a moment. And by the way, Tim, these people that are running around saying, oh, every opportunity is. I mean, every problem's an opportunity. I want to throw up. I didn't have an opportunity. I had a problem, right? I didn't have, how am I going to fund these deals? So I sat here and here's another actionable item. Whenever you have a problem, here's what I do. I asked myself the question, who can help me with my problem? Who can help me with my problem? Well, immediately I thought of Jeff Blankenship, a good friend of ours that lives in Greensboro, or did live in Greensboro, North Carolina at the time. I called up Jeff and told him what happened. He said, well, welcome to the club. I said, what club? He said, the club of getting cut off from the banks. He said, they cut me off last week. I said, well, how are you funding your deals? He said, you ever heard of private money? I said, no. He said, you ever heard of self directed IRAs? I said, no. Well, I put on my research cap and I learned all about private money very, very quickly. So one of the first things I had to do was to put my program together, my private lending program. And after putting my program together, I had to put on my teacher hat right here. I had to put on my private money teacher hat. And then I just started teaching people. Not selling, not begging, not talk, trying to talk, anybody, anything. I started teaching people that I go to church with, that I know in my cell phone at the Rotary Club, at Business Networking International. I just started teaching people what private money is and how they can earn high rates of return safe and securely. And so I started teaching my program. So, you know, what interest rate am I paying, what's the length of the note, frequency of payments, how you can get your money back in less than 90 days if you got an emergency, et cetera. So I just started teaching people. Now here's another writer downer. Desperation has got a smell to it. And the worst time you can be looking to Raise private money is when you need it for a deal. So I did not tell any of my people that I was teaching about private money, about those two deals that I had under contract. Because if I taught them my program and told them about the two deals, now I'm pitching a deal, now I'm asking and I'm coming across desperate. And I'm not even trying to sound desperate. So I separated the conversations of teaching the program and then having a deal for them to fund. So I remember like it was yesterday, Tim, I went to Bible study on Wednesday night at 7:30, and there was a gentleman there that I wanted to talk to. And so I walked up to him and I said, hey, could we visit for a few minutes after Bible study? He said, sure. So we got together and here's exactly what I said to him. His name was Wayne. I said, wayne, I need your help. So here's a little bit of scripting. This is called the indirect method to attracting private money. I said, wayne, I need your help. I said, I've now opened up my real estate investing business to people I know and trust. And when you run across somebody that is complaining about the low interest rates and CDs and the volatility in the stock market and losing money in the stock market, would you refer them to me and I'll tell them about my program? Well, what do you think? Wayne said to me. He said, well, now, brother Jay, what you got going on there? Well, by the end of that conversation, he had become my first private lender because I asked him for his help to spread the word. Now he's asking me, how's it work? I went to his house the next day, sat down with him and his wife and $250,000. And you know, an hour later I got $250,000 burning a hole in my pocket from him saying, well, look, we'll start with 250. And so I didn't tell him about the deal. So I let two or three days go by and I called him up and I gave what's called the good news phone call. I called up Wayne. I said, wayne, I got good news. I can now put your money to work. I got a deal under contract over in Newport with an after repaired value of 200,000. The funding requires 150. I know he's got 150 because he told me he got 250. I said, the funding requires 150, and the closing is next Thursday. So you'll need to have your funds wired to our real estate attorney. By next Wednesday and I'll have my attorney email you the wiring instructions. You notice how I didn't ask him if he wanted to fund the deal? That's the most stupid question in the world I got asked. Of course he wants to fund the deal because he's been waiting on the phone call for me to put his money to work. And I'll tell you another thing real quick. I'll turn it back to you, Tim, and I'll tell you another thing if you like. If Wayne had had retirement funds and I had introduced him to the company that I recommend to all my private lenders to move their retirement funds to, if I had had him move funds over now, I am ethically bound to put that money to work. Cause they've moved the retirement funds over waiting for me to put it to work and they're not earning any money until I give them the good news phone call once they've moved those retirement funds over. So again, it's all I had to get my mind wrapped around this. This whole thing of there's no asking, begging, chasing, persuading, or selling. It's all about teaching, edifying, serving these people and making a difference in their financial future.
Gosh, Jay, so many nuggets there. I mean, it's clear that you've been doing this for a while and you're a fabulous educator and I love that idea teaching people about this now when we don't actually need the money. And again, I think this is super timely advice because there's a lot of people out there that are thinking interest rates are really high, but when they come down, boom, I'm going to pull the trigger. But that doesn't necessarily mean that the banks are going to be lending easily, you know, even because interest rates come down. So I love that advice about teaching and educating people. Right now I've got quite a few things I want to jump into. One is about the actual structures. And like you said, this is up to us, right? So it's very flexible. A lot of our listeners on the show were buy and hold, the long term rental investors, you know, with a focus on short term rentals, hence our, our show name. But before we get into that, I know there's also a lot of our audience out there that are thinking, gosh, this all sounds fantastic, Jay, but I haven't got started. I haven't gotten started with real estate yet and I don't have any experience. What would you say for some of those people starting down this road of educating people and, and hoping to have some private lenders line.
Well, first of all, don't start by yourself like I did.
Big mistake. I was in the mobile home manufactured housing business for a long time and the consumer finance for that product virtually went away. That's why I started in this in 2003. So I just used my experience and my knowledge from that industry. But I can tell you it is not directly transferable. So my advice, if you're brand new looking to do your first deal, you need to get someone like Tim to work with you on, on, you know, that's already knows where the minefields are. And I mean when I started out. Oh Tim, I hate to even think about all the stupid mistakes I did or ignorant mistakes I did because I didn't know any better. All right, so the, so the first thing is get a coach, get a mentor like Tim. But in addition to that one, one common fear that I hear from new real estate investors are, are two things they say. They say, first of all.
I'm not comfortable asking anybody for money. Well, we already fixed that. You're not asking anybody for money. You're not asking anybody for money. You're teaching. You're teaching, you know what you know, you're teaching them about how they can earn high rates of return safely and securely. So you teach the program. And by the way, I've got a book that I'm going to offer everyone here on the show when we get here to the end that will teach you the program right in the book. What's the interest rate, what's the, you know, the length of the note, etc. And you know, just, just duplicate my program. Another, another fear that I hear new real estate investors say, Tim, is who's going to loan me money on a deal? And I've never done a deal. Who's, why would they do that? And here's the answer. So here's another writer downer. The answer is if you, the borrower, the real estate investor, if you don't pay your private lender, the property does. If you don't pay them, the property does. So what does that mean? What that means is, is we don't ever borrow unsecured funds. You can legally, you just get a promissory note draw drawn up and. But look, you're not protecting your private lender. So we borrow secured funds and then what do we do? We're going to give the lender the private lender or private lenders. You can have more than one private lender funding the same deal. We're Going to give them their own promissory note and their own mortgage or deed of trust Here in North Carolina, in about 10 of the states, it's a deed of trust. All the same thing. What that mortgage or deed of trust does is it collateralizes that note. So those, these promissory notes, this money we're borrowing is backed by the real estate that we're buying. So we typically don't borrow more than 75% of the after repaired value. I didn't say of the purchase price, I did not say of the purchase price of the after repaired value. So typically you're going to be able to bring home a check when you buy. That's one beautiful thing I love about this private money. Every private money deal is a no down payment deal. And some people say, well, Jay, how in the world can you get private money? Don't have any skin in the game. I can tell you what the skin in the game is. The skin in the game is the equity cushion that's protecting your private lender. That's the difference between the after repaired value and, and what the borrowed amount is. So it's a very, it's a conservative loan to value. Everybody is protected. And, and again, I mean you're changing these people, these people's lives. It's win, win, win all around.
I love that, I love that. And I love real estate. I mean, and one of the reasons I love it is because it is so flexible. It's one of, you know, the unique investments where we can work with other people, as you mentioned. So we can't do that with stocks. Right. If we go to buy a stock, we sharing that with someone. We're not creating a partnership with lots of traditional investment opportunities. It's kind of like you and you alone. But with real estate we can find someone that has the experience already. Maybe we have some family or friends or acquaintances that want investor money or maybe we're at least open to asking them. And then we also have another friend that has all the real estate experience and we can kind of put that all together, can't we?
Absolutely, absolutely. Nothing wrong with leveraging your relationships.
Awesome. So. Well, Jay.
Yeah.
A lot of us on in the audience are buy and hold long term investors. So whereas we might not be going down the flip approach, we certainly can be adding value to a property, maybe taking a property that was a traditional long term rental, furnishing it and turning it into a short term rental. That's been a really good approach for a lot of us. Assuming the regulations allow for it. So let's talk a little bit about some potential structures. And I know like you said, I mean private Monday, there are no rules. Right. It's, it's kind of what you create with the person lending the money. So what, what advice might you have for some potential structures for someone maybe wanting to look for a little longer term private lender?
Sure. So there's a couple of different ways to approach it. First of all.
We'Re not creating and putting together private equity deals. In other words, we're not giving a partial ownership or a percentage of your profit or whatever to the private lender. So here's another writer downer. The private lender is the bank. So just view the private lender as the bank. You own the property, your entity, whatever entity structure that you're buying in your. Be sure you don't put it in your personal name for goodness sakes. But whatever your entity structure is, your entity owns that property. Private lender is going to get the same protection as the local bank. Well what's that protection? Well of course the promissory note we talked about, the deed of trust we talked about. But we're also going to name the private lender on your insurance policy just like the bank. Remember the private lender is the bank. You're going to name them on the insurance policy as the mortgagee. So if there's a claim against your insurance policy, then your lender's protected in that way. You know mortgagees, when a check is made payable from the insurance company, typically they make that check payable to your entity, the ownership and to the mortgagee as well. So they have to sign off on those checks. Another layer of protection. We named the private lender also as an additional insured on the title policy. So if there's any kind of title issues down the road, then they are protected as far as the structuring of the deal. As I said, they're going to get a mortgage and we're going to pay. You got a couple of different options. I since most of what I do and I do have short term rentals myself, in fact I am now converting my grandparents home that's in the country. I'm converting that to a short term rental as well. And Scott, the original beadboard ceilings and the original pinewood floors built in 1927. And anyway I'm having a, in fact I talked to my contractor this morning. I'm having a great time converting that to a, to a short term rental. But anyway, on my flips and this is not a flip that house I was just talking about. But on my flips I'm typically, if I'm going to be in and out of a deal in six months or nine months, then you don't even have to make monthly payments. Just let the interest accrue. Right. Talk about fixing your cash flow. You buy a property, you bring home a big check because you borrow more than you need to buy it and rehab it. If rehab is involved, I bring him a big check and I don't make any payments or to the private lender until, you know, I cash out six or nine months down the road. But that's a different deal here now where we're talking about short term rentals because you're staying in that deal, you know, for quite a while. So you can either. And let the math make the decision. There's another writer downer. The math makes the decision, not your emotions. So you can, you can pay interest only payments if your cash flow, if your cash flow makes sense. So for a flip, I'm paying 8% and no points. 8% and no points. It's been the same program since 2009 and I haven't raised it since. Craziness has been going on the last few years. But now on a long term to where you're going to be holding that property, then you know, depending on what, how much monthly income, you know, take out your vacancy and all that kind of stuff. Tim can teach you those percentages. But be look, what's your conservative cash flow looking like or revenue coming in. So you know, on the long term hold, you may only be offering, you know, 6 or 7% for the long term right now, I believe, and I do not have a crystal ball, but I got some very, very smart friends that do have crystal balls. I think we're going to see a reduction in mortgage rates within the next 12 months, probably significantly for a number of reasons. But.
You can structure it at 6 or 7%, right? I mean I've, I have sold a lot of homes on rent to own and I was paying out 8%. And of course rents have gone crazy. As you know, Tim, rents have gone crazy like in recent times. So it comes down to the cash flow. Now if you can buy a property and get it to cash flow, you can pay principal and interest rate. Particularly if you could pay that thing off in 10 or 15 years. If you can get it to cash flow, then you can pay principal and interest payments. Right. Another way to approach it, you know, so often when you're buying A property speed is king. Fast closings are important, right? To particularly a motivated seller. And by the way, some of my best deals, I've just recently bought it from tired landlords. I don't know what's going on with the tired landlords, but they seem to be everywhere and they're getting more tired by the day. Anyway.
You can, you can use private money to close quickly. See, I make all my offers. I can close in seven days. Well, the bank can't close in seven days. I mean, in this world of private money, there's no appraisals. You don't have to wake on appraisals. You know, you can close very, very quickly. So what you can do is you could use private money to close quickly. And then if you're going to fix it up, furnish it, whatever, use that private money for that in the short term, maybe for six months or whatever. Then you can go conventional and you can refinance it for a 30 year, you know, amortized or whatever you want, pay off your private lender. Now you got that private money sitting there waiting to get your next deal that you can close quickly. Because I tell you, I'll get deals and my offers accepted at a lower price. In fact, I got one right now, competition offered 135,000, but they can't close for two months. I'm buying it for 100,000 because I'm closing in seven days. So use private money for a fast closing and then just refinance it out with your conventional lending.
Yeah, that's, that's great advice. And it's just my mind spinning here because it really is like sky's the limit. I mean, with private lending, right, we can set up our loans however we want. And I was thinking of something when you were going through all that, Jay, in terms of closing quickly. And also you mentioned there's a lot of tired landlords. I mean, the reality is that a lot of our baby boomer generation, which is the second biggest demographic in the US are retiring, you know, and they're at those ages. A lot of them own their properties outright, so they don't have any loans on them, but a lot of them want to sell them. So there could even be some sort of mix going on here where the owner's providing seller financing, but they still want their down payment. Maybe it's 25% percent. We could use private lending, for example, to get that down payment. So again, it's not coming out of our pocket. The owners selling their property, they're a Happy camper because they got, they're getting out of a deal in a time where it's not as easy to sell. So there's just, gosh, there's so many ways to do it, isn't there?
Absolutely. And I'm glad you brought that up. I mean, the seller could care. I mean one question we ask our sellers, tired landlords is what's more important to you? Cash today or long term monthly income. And you know, a lot of those tired landlords, I mean they will, you know, they'll finance it for you and take back a note. But of course most of them are still going to want the down payment. So I'm glad you brought that up to him. You can use private money in what we call second position or a junior lien position.
But here's the formula. You still want to protect your private lender. You want to, you know, protect the landlord in this example that's, you know, has got a first mortgage. So again, typically depending on the, the scope of the rehab, if rehab is involved and most of the time you want, if you're getting a short term rental ready to go. Tim, I probably, you probably do advise, you want it to be looking good and smelling good.
You want it looking good. That's right. And smelling good.
Even more important, you can put that private money in second position as the down payment money as well. So I'm glad you brought that up.
Yeah, a lot of, a lot of flexibility. I love it. Jay, I know you've been teaching on the subject for a long time, so we're going to let people know where they can reach out to you. And I've got one other question. It's actually not related to real estate, but before we get into that, any other last nuggets that you might have out there or words of wisdom?
Well, in the real world out there, most real estate transactions that take place, the seller is going to require the cash, most of them in the real world. And if you don't have the cash readily available, you're simply just going to miss out, miss out on deals if you don't have, you know, it ready to go. And by the way, here's the big, here's the biggest advice, most important advice I could give as we're starting to wrap up. But don't go anywhere, folks. I'm getting ready to give away my book.
Write this down. The money comes first. Now what am I saying? Tim, let me tell you something that just drives me bonkers and I just want to go run headfirst into a wall every time I hear this. But you've got educators out there, AKA gurus out there going around and I've heard it. I don't know how many times. I'll say, oh, just get the deal under contract. The money will show up. Because money follows deals. I want to say, where in the world is the money going to show up? Is it like going to rain out of a cloud somewhere or whatever? So I preach and I teach and I practice. Get your private money lined up first. With one or two private lenders. There's always deals. There's always deals. I mean, you know.
I've reviewed thousands of property lead sheets over all these 20 years and my statistics show. And I'm a pretty good closer. And my acquisitionist has been with me 18 years. My acquisitionist that negotiates with sellers. And my statistics show that 13% of those for sale by owners, FSBOs. 13% will sell creatively either with owner financing or subject to the existing note or, or any of those other creative financing methods. But 87% of them require all the money. Get your private money lined up first.
Excellent advice, excellent advice. And I don't think it could be more timely. Well, Jay, as we wrap up and before we let everyone where they can get in touch with you and learn from you, I've got a question. So the name of the podcast is Short Term Rental Riches. So when a lot of people hear that, they think about financial riches. Right? But as we know, living a rich life is so much more than that.
Right.
And so I'm just curious if you have any sort, anything that you've added in your life recently that's not financially related that's helped enrich your life?
Absolutely. I've got a really, really good friend, his name is Tom Crowell, K R O L. And he shared not too long ago, a practice that he started some time ago in the past. And his practice is read eight pages a day in whatever book that you're interested in. And the reason he advises that and he practices it is that, you know, I love to read, right? I mean, the book that. The book that changed my life and had the biggest impact way back when I was 24 years old was University of Success by OG Mandino. And I read that book, changed my life, got my head screwed on, right? But, you know, I would be buying these books and they'd sit there and I never get around to them, right. Even though I wanted to. So eight pages a day. And what I learned when I started practicing this Reading eight pages in the morning as part of my morning routine. What I learned was most of the time I read more than eight pages, but I'm setting it up as well. I can read eight pages, particularly in a book that I'm interested in. Well, the average size book is 200 and some pages. Well, eight times 30 is 240. So when you read just eight pages a day in the morning or whenever, well, that's 12 books that you have, you know, read over the, over the course of the next year. So it's a simple practice that has a huge impact. And you know what?
I love it.
If you're not constantly learning, you're going backwards.
I love it. That's, that's gold. Jay and I, I agree. I'm a huge reader. The thing that fascinates me about books, well, I'm just curious person, but.
Someone can dedicate their whole life to one subject and they can boil it down for us in one simple little book that we can read in a couple weeks or even a month or even if it took us a year. We're taking someone's experience from decades and we get, we get the benefit of that. So I guess that's a good segue into the fact that you have a book. Can you tell us about that and where we can find that?
Absolutely. So the name of the book is where to get the Money Now. Where to get the Money Now. And the subtitle is how and where to get money for your real estate deals without relying on traditional or hard money lenders. You can't download it. I mean, believe it or not, the post office is still in business. So I will send this priority mail out to you. The book is free, just cover shipping and you can pick this up at J. Connor. By the way, I'm an er, not an or so J connor.com J a y C-O-N-N e r.com book. So that's J. Connor. J A Y C O N N E R.com forward slash book. I'll autograph it and we'll priority mail it right on out to you.
That's awesome, Jay. That's awesome. And you are also a fellow podcaster. Can you tell us the, the name and where people can find your podcast?
Absolutely. Thank you, Tim. So we're in our sixth year of the podcast and the name of the podcast is Raising Private Money with Jay Connor. And I have fantastic guests on there all the time. In fact, Tim, I got you lined up and we always talk on the show. About private money and how my guest have gone about raising private money and what are the words they use and how do you start conversations. And so wherever you like to tune in on your podcast, whether it's itunes or Spotify or wherever, whatever directory you like, your iPhone, purple podcast icon, whatever, it is easy to find. Just type in and search for raising private money and with Jay Connor and that'll pop right up.
It's fantastic. Jay. Well, I really appreciate you being on today. I mean, words of wisdom and these are life skills for any serious real estate investor. I mean, it all starts with getting money before we get the properties, right? So I really appreciate you joining us today and we look forward to staying in touch.
Thank you so much, Tim. It was great being on. Thank you.
I've dedicated years figuring out how to manage my personal portfolio remotely and it wasn't always easy and it took a long time. But now my amazing team can professionally manage my properties without me. And good news, our team can also manage yours. Let us save you the stress and headaches and some money by offering you an industry low fee. To find out more about partnering with us, head to Strike. Hit the property management button, answer a couple quick questions and meet with me personally. That's strict. Rest easy knowing that with my team, your properties will be in excellent hands.
More from Tim
Airbnb profit insights to get your business ready for sale! #podcast #realestate
What Most Successful STR Investors Are Focussed on Today: From a 300+ Investor Meetup