Mock Appt with Tanya Hughes
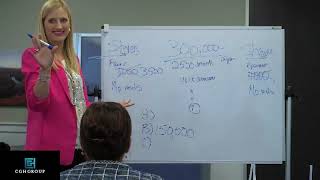
This transcript is a mock appointment led by Tanya Hughes (YouTube video) demonstrating how to sell mortgage protection through a role-play with Michael, Stephen, and Shawna. Tanya walks agents through rapport-building (occupations, incomes, medications, kids), quantifying household finances and mortgage ($300,000 referenced), creating emotional "pain" (income loss, foreclosure risk, children’s schooling), and offering coverage options (examples: $150,000 partial coverage, 90k short-term bridge, full $300k). She gives concrete pricing examples (monthly quotes), suggests plan A/B/C, the accidental death rider (doubles payout in accident), and closing/follow-up tactics ("three strikes, you're out", book callback, capture reasons on lead). The training emphasizes fitting coverage to budget and prioritizing client protection over upselling.
Chapters
You just. You're just gonna sit right here. We're gonna act like I'm on a birth control, okay? Now I'm asking questions. I'm gonna put Stephen up here, and let's see, We're gonna put Shawna here. We're gonna act like you're married. Just so I can cut. Just so you can see it, okay? So I'm gonna put Steve down and put you here, and I'm put. Sean. Now, remember, I've already built the report. Now I've got to go, and I've got to find the pain. You. If you do not find the pain, you do not find the game, period. If you do not find the pain, you do not find the game. Okay? So let's say they've got a $300,000 mortgage, okay? First and foremost, we represent about 20 different companies. You are not going to learn all 20 companies. Right now. You're going to focus on about two, maybe three. I'm going to get you contracted with everyone that you need to. So if that one kind of happens, I'm like, hey, guess what? Today we're going to go do this. Then we can. Okay. The other thing is, Michael, I'm going to have you put the. Is it in the link to the. Of my training with the videos that has, like, a product training. Oh, I forget Kayla. Y' all has. Kayla, she changed that website to me.
Kayla, post it in the chat.
Kayla, post the chat where those videos are. Okay? And it's a working car, so it's not done, but we want it available to you so you can see it. Okay. You're talking about the training site, right? Is that what I heard?
Yeah.
Yeah. All right, Steven, 35. Okay. Stephen's 35. All right. Shauna. I'll be 35, too. Okay, 35.
Shauna's 29 again.
I will be 29. Okay. Okay. And we're gonna save a $300,000 mortgage. Okay. So I'm gonna ask. I'm gonna. I'm gonna do this like I would do it in your presentation. So I'm asking questions. Help me understand where you're coming from. Okay. Because I need to kind of paint this picture however you want to say it. I don't care. Me. I say pink is pink. Right. Stephen, do you work? Yes. Okay. What do you do? I'm a farmer. You're a farmer? Awesome. You enjoy it? I love it. Awesome. Roughly how much would you say you make per month? Per month?
7,000.
7,000. Now, remember, I've already built rapport so we're gonna act like you guys can build rapport. You know how to be a friend? Just be a friend. You're gonna make a friend. Be a friend. So you make about 7,000?
Yes.
Okay. About $7,000 a month. Okay. And Shonda, do you work? Yes. Okay. What do you do? Apartment managing. Your apartment manager. Okay, awesome. How do you like. Okay. It's okay. It's okay. All right. And roughly how much do you make per month? 50,000. 50,000. So roughly. Oh, a year. A year. Okay. I'm sorry. So about. I want to know. Not your gross. Because I don't care about Uncle Sam. I mean, we gotta pay taxes. I know, but that doesn't really help, right? We don't care where Uncle Sam. So tell me where your net income is on a monthly basis. Would you say 5,000? 5,000 times 12 would be 60, so probably more like 3,500, right? 4,000.
Well, four is 48, so it's a.
Little less than 4,166. There you go.
And 37 cents. Don't forget the cents.
So I'm going to find out their incomes. Why am I finding out their incomes? Because I want to know, if something happens to Stephen, how's that going to affect Shawna? And if something happens to Shawna, how's that going to affect Stephen? You're creating the picture. I'm creating the picture in front of me. Okay. The next thing I'm going to ask is, I'm going to say, now, Stephen, do you currently take any medications? No. None. Zero. Man, you are so lucky to be healthy. That's awesome. Okay, no meds. Okay. He has no meds. Okay. So I'll be like, yeah, that's the time to get this. Because you wait till you need it. It's too late. Right? All right. Shawna, do you take any medications? No. Awesome. Okay. And I'll talk to you. We're having a normal conversation. Do you have any kids? That kind of stuff. In the beginning, I always tell them a little bit about me, right? I said, tell them I had six kids. You know, I tell them I do special these kids, right? That's my passion. Or, you know what? You got a story or. I don't know much about you yet, Steven, but you might know someone that got sick, that maybe this could help. Right? You gotta have. You've gotta have something to help people. Facts tell, stories tell. They gotta be able to relate. Be able to relate to it, because they never can feel like they're gonna relate to it. Okay? So in this situation, I'm gonna ask them now, how much is your mortgage for how many years is your mortgage for?
15 years.
15 years. Okay. Is your goal paid off and less?
Yes.
Okay, what's your goal?
Six years.
Six years. Okay. So really, the next 10 years, your biggest concern. Okay, okay, let me ask this question. What do you currently have in place if something were to happen to you?
Nothing.
You have nothing. Nothing. Okay. Nothing. You have nothing. And that's okay. 90% of people don't. It just helps me understand where you're coming from. Okay. Sonra, do you have anything if something were to happen to you? 401k. You have a 401k. Okay, roughly how much do you have? 300,000. You have 300,000? Yes. Okay. Are you happy with the risk you're taking and the money you're getting on that one? I'll joke around about it. I'm like, you're losing money on that, aren't you? Well, we won't talk about that right now. Right. Move on. Okay, so you got 300,000. Do you have any kind of life insurance or anything like that? No. Okay. All right. So they neither one of them have meds. To not be ready to ask this question. Stephen, do you get a short term, long term disability at your work? No. None.
No, I'm self employed.
So if you get sick tomorrow, this goes away? Yes. 100%.
100%.
What does life look like for you, Shawna? Tomorrow you lose $7,000 a month. Hard right. It's going to be tough. It's going to be tough. Yeah. The animals need to be taken care of. Expensive. Well, you got a payment here. How much is your house payment? About 2,500. All right, 2,500amonth. Okay. Now remember, today would be your foot and door is what fits your budget. You're just moving into your home or if they refinancing, just refinance your home. You consolidated. You're trying to save money. I get that. Okay. Okay. So if he gets sick, if he gets sick tomorrow, he's got nothing. Okay, Shauna, I'm gonna ask you the same question and do the exact same thing. But the other thing I'm going to ask them is do they have any kids? Do you guys have any kids? Three. Three kids. Okay. What are the ages? Eleven. Okay. Nine. Seven. Okay. So now most people's biggest concern is with their youngest to school without any disruption. We don't want that 7 year old to have to worry about if something were to happen and the Parents were to get sick or heaven forbid, pass away, you have to pull them out of the school, teaching away from the friends. This is for one of the hardest days in their lives. The last thing your kids need to do is have to be able to paint that picture of their kids literally leaving this house. Because right now, if something happens to you tomorrow, she's going to have to sell the house immediately. And now not only do you not grieve, not only do you not have time, but now you've got your kids, girl. Losing their friends and having to readjust. Okay, do you pay that help receipt? Multi's biggest concern is getting your youngest through school. Would that be your concern? Let's say I got a 30 year mortgage. Let's say your mortgage is 30 years, pay off early. Yeah, we're playing on it. Okay, great. Now most people's biggest concern is getting the youngest year of school. That's probably what, the next 20 years, right? Getting through college. Yeah. Okay. All right, well, let's look at least the next 20 years. Or maybe you're working here, right? Because remember, if you get sick tomorrow, your income goes away. Okay? You're creating the pain. You understand? You guys have questions? No. Okay. Okay, Sean. So. And I'll do this. And I do it for myself, more so I can feel. Might seem kind of weird, but it helps me feel that same pain. I'll try to imagine what I would be like in that shoe. Okay, so his income goes away. Now I'm going to ask the same question to Shawn. Okay, Shawna, you short term, long term disability at work is. No, no. Okay, so you're telling me if you get sick tomorrow, this infant goes away 100%. 100%. 100%. 100%. So tomorrow you wake up and you get diagnosed with something or you have a heart attack, this goes away? Yes. What is life look like for you? You have three kids. Three kids to take care of. You're pretty tough, so be tough. Okay, so what most people do is look at eliciting something that would give them time to get on their feet if something were to happen. Basically that will give time. Whether it's the full mortgage or half a mortgage. You've got to figure out what fits your budget. Okay? You're creating the pain. Okay, so no man's. No man's. If they get sick, there's nothing. Okay? Now in my presentation, I'm going to act like you have a short term or long term disability. I'm going to rewind the clock so you can see what I would do if I have a short term and long term disability, Right. Let's say. Let's say they had a short term and a long term disability. My race. Here it is. Okay. Let's say they have a short term, long term disability. So if something happens to you, Steven, you're going to get about 3,500amonth because you get short and long term disability at your work, right? Yes. Typically it's 40 to 60% of your income. If your income gets cut by 40%, Shawna, what does life look like for you? Well, we lost money. It's going to be hard. It's going to be hard. Thanks. Not counting the doctor bills. Correct. So all of a sudden, when someone gets sick, what happens? Your income goes up, Your expenses do what they go up. I do talk with my hands. But you know what? It's very powerful. You say, what do they do after they go up? Yep. And what happens to your income goes down. You see the gap. Mortgage protection is designed to be that bridge to allow you to get back on your feet if something were to happen to you and not lose. Because in 2015, three out of five homes were foreclosure due to a major medical, a heart attack, a stroke, a cancer, something like that. Okay. This at the hardest times of people's lives, they were losing their most valuable possession at minimum. We want to protect the equity at minimum. Okay, so then I'm gonna go, I'm gonna look at Stephen and go, now, Steven, if we can only cover one person today, do you agree that you're the most important person to cover right now?
Yes.
Okay. We can always add your wife later. Or if it makes sense, we just gotta figure out what's the magic number that fits your mind. Gives you guys that peace of mind, knowing if something happens to you, that your family's gonna be okay. Okay, so I'm looking at Stephen. Right. So the mortgage is 300,000. Okay. I'm going to say. And I just say no. Typically, I like to do a plan A, a plan B and a plan C. I'm be very honest and transparent with you. I just need you to stay back to me. Can you do that for me?
Yes.
Perfect. Okay. Michael, will you run me up? Will you run me accountant? You run me a quote? Just run.
Sure.
Couple quotes.
So he's already $47.30.
No. Okay.
Oh, you want a room.
I'm always going to start off in the middle. I'm always going to start off right in the middle. Here's why. If you get a If you have a short term, long term disability at your work, it's 40 to 60% of your income. What I know is if 50% of that mortgage was taken care of, you'd be okay. Because there's a gap, okay? In this situation, all of it's gone. Right. But I'm still going to start in the middle. I'm going to go, okay, we're going to look at 150,000. Okay? Now, he says he's going to pay it off in six years. So normally I focus on 10 years, but I'm going to actually pull the kids into it because you're going to see it all the time. You mentioned your biggest concern is getting this one through school. Okay, so let's look at that. Let's look and see what the next 20 years apply for. You. You're working years. Most people. Most people. Keywords, Most people. Typically, most of my clients. Most people in your situation. Right. That's what we do. So let's say if I have Stephen at 35, let's do GPM 150,000.
You have the recalculator shortcut on it?
I do. If you don't have the right short calculator on it, you need to ask me for it. And we'll get it for you because you can save it on your phone. Now you can use the toolkit. It's awesome. It's a guide. It is not the end all, be all. You're going to be filling this needs analysis up. Once you create the pain and you show me the picture, I'm going to tell you what you're going to write. Now, do I do it? All the ones who do what I tell them to do get business placed. Good news. Place your paid right. Number two, you learn as you go. Right? And at the bottom of the lead, I want you to write back. On the bottom of every lead, I want you to write why the client needed the coverage. Not just they be in trouble. They would lose $7,000 a month and the wife would have nothing. I want you to put that at the bottom of that lead. So if you don't close it, we're going to talk about what you do to create the pain and help you see it more. Okay? We are always going to do what's best for the client and it is to protect them. Now, most people have a life insurance. Let's say you told me you have a life insurance at your work. I'm going to say that's awesome. I'm so glad you do, man. You know what? You don't own it, you don't control it. I tell people all the time, it's like the ketchup bottle at the restaurant. It's great while it's there, but you can't take it with you. You just can't. Okay? And you know what? It only covers if you die. Most people looking at mortgage protection, they're not looking at if they die, they have life insurance. What happens if they get sick? What happens if they get sick? Right. Okay, so let's go back. 150,000 is what I want to put.
The accidental rider on it too. 630.
Yeah, that's probably a good idea. 150,000. So we'll do 150,000. 150,000 accidental. What that means is if it's a life related death, you're going to have 150,035. What?
Instead of 35 years of age. Okay, you do that, right?
Yeah. So 150,000 is a life related death. It was an accidental death. And at 35, any age below the age of 50, you're more likely to die of an accident. Once we hit the 50, we're moving to the other threshold. More likely. Life related. 60 for sure. More life related. Okay, so in the event of an accidental death, it's going to double. What is that number, Michael?
$56.30.
$56 whatever. Just call it $56 whatever. Okay, got it. Budget wise, what does that look for you guys that's comfortable? It's comfortable number. Okay, perfect. Well, I'm gonna go ahead and work my way up and work my way down and we're gonna figure out what makes the most sense where you're at today. Remember, all we're doing is getting your foot in the door with what fits your budget and where you're at today. Okay. Okay, I'm going to turn back around and put 300,000. Go ahead.
This is without accidental. Yep, just a straight 383. 74.
For what?
$83.74.
That's for that for 20 years.
30 years. Both of those are 30 year terms.
Okay, you can do 30 years, but do 20 years. Because we're trying to. Our biggest concern is that seven year old.
Well, so 20 years on 300,000 is back down to the $54.86.
Okay, so then you got into the other one. This is probably wrong.
So we're just doing 20 years.
Yes, because our concern is getting the seven year old through school. And here in 20 years from now, 5486. Which one?
That top 300,000 is 5486.
Okay. 5486. Okay. And do this on it now.
Yeah, just a second. The accidental 4187.
4187. Budget wise. Okay, so let's ask the question again. Budget wise or does this fit for you?
That's comfortable.
Okay. Okay. And the $300,000 is $54.
We could work that.
You can work that. Okay. Now, most people, typically the average in a household is $89. Right. Some do more, some do less. We need to figure out if it makes sense for both of you to get covered or just one. So if something happens to her and you gotta take care of these three kids at home, having something's probably better than nothing, right? Yes. It'd be hard to work and do that. Okay. All right, so then I'm gonna turn back around and do the same thing for her. Okay. So, Michael, turn it around to do a woman.
Option B for Shawna is $39.24. Just right on the left side of.
Yeah, that would confuse me. 34. What?
39, 24.
I'm not picking all of these, but I am that. Okay. 3494.
Yeah.
Okay.
And then 300 is 3961. Or 4961.
Okay. And then what about. Okay, well, let's just do those because he's already told me these are a comfortable number. I'm not going to work my way down. But let's say these are too expensive. But if something's better than nothing, I'm going to take their mortgage of $2,500 a month. Okay. I don't have my phone. Oh, wait, here it is. I'm going to take that mortgage at $2,500 a month, and I'm going to multiply by 12. For one year. That's one year. That's for 30. That's 30,000. What I want to do is I want it less than 150. So five years is 150. So I'm gonna do three years. So it's gonna be 90,000. So I'm gonna say. Let's say this is too much. You can't afford it. So we're gonna get. Pays the mortgage for three years. I don't remember all this on here. I'm just doing it right now for. So you can see it. Right. And then I'm going to put that number. What is that number, Michael.
For 90,000 for Shawna is $18.56.
Okay? Most people can afford $18.56. If you can't, you're going at it way too much. I'm just saying.
Okay, for Steven, it's $20.13.
Oh, well, whatever. Okay. He gets one. You understand what I'm saying? You get the concept. You understand what I'm doing? Okay? Something is better than nothing. This at least gives them three years. If you were to get sick, the kids can get adjusted. She can sell a home and save the equity. It's all in how you present it. Okay, so then I'm going to say, okay, now, we talked about both of you. So between the two of you, what's that magic number? So you feel like this is a comfortable number. Are you thinking about $80? Is that what you can afford on a monthly basis? Yeah. Okay, but $8. So we want to get the highest on you because you do make the highest income. So let's go ahead and look at this for you. Now, remember, today I'm going to do the process, start to get you qualified. I'm not the person that makes the decision. I think you qualified. Okay. And then right here. Let's do this. What about this? We can do this one to that. That would be.
Just a little over 80. Yeah, that works.
A little over eight. Is that for your budget?
That'll work.
Okay, that's a comfortable number for you. Yes. So if someone comes and slides all four tires in your driveway tomorrow, can you afford that? Yes. Okay, you go. You want it. You've got to help them. See, hey, if some. You don't want them to be going, I had to go. Yeah, I think I can afford it. I think I can. I have one guy. Oh, yeah? $400 a month. Yeah, no problem. Okay, I understand. You want that. $400 a month. You're just getting home and just getting situated. Let's do this. How about we start off with like $300 a month, and then we can add to it six months, nine is down the road. Because here's what I don't want to happen the first, if you. If you barely like. If you create something that they can barely afford it, you're going to cancel it. They're going to cancel because it's the first thing they're going to afford. I'm going to reinstall them. Now, this is really important because now, now you're going to have something that. If something were to happen to either one of you, one, you can say the equity, you can Sell the home if you need to. Your kids can say, remain in the school and so on. Is living proof of it, right? That you can make it in trouble with three. With three kids. When I met Shawna, I never knew that was. Six months later, her husband passed away. You are making a difference. Yes, you get paid for what you do, but do not focus on the money. The money will come when you do what's right for the people. That is the key. Don't make them overspend. If I'm going to do anything, I'm going to talk them up. I'm going to talk them down. I'll talk them up. One guy. Why do you keep talking me down? I'm like, I'm not going to talk you up. I'm not like everyone else. I'm not trying to make the most money. What I want to do is what could fit your budget and protect your family, because that's the most important thing. I'm not here for today, unfortunately. I'm here for one of the hardest days of your life. That's why I'm here. Re instill that. Do you feel that? Do you feel the emotion?
Yes.
You've got to create in us. You got to feel the emotion. If you're not, even if you can't imagine what, you got to try to imagine a picture of your life. How would that look like for you? So today we're going to go ahead and get everything started. I just need you to grab your driver's license. I'm going to quickly go through these questions to start the process, get you qualified. Okay. Takes a few minutes. Want to think about your okay? Throw me an objective. I need to think about it. Great. No problem. Then you think about you, too. We don't even know if you're going to qualify. Right. And then you think, oh, well, I really need. If three strikes, you're out. If they said you need to think about it three different times, I'm going to turn back around and say, it sounds to me like you really need to think about it. That what I'm hearing? Yes, I completely understand. How about this? How about I just book a time? What time are you. What. How long are you thinking? I don't want to bug people, but this is one of those things a lot of people said, you need to think about it. And then you get that phone call from the mom who says, my daughter just had a stroke and it's in the hospital and can't pay her house payment. And she has a mortgage. She got A mortgage, protection. And you look that up and you find out that she never got it because she was thinking about it. True story. My own client, I had another mom. The girl lost her home. She was healthy. She was 40 years old. She had a massive stroke in the hospital. Sometimes we think about just a little too long, right. So helping them understand, Right? So if I recognize it's three strikes, you're out. That's my. That's my. In my mind, that's the key. Three strikes, you're out. So it sounds like you need some time to think about it. I completely understand. When is a good time for me to give you a call back? You know, most people, this is one of those things that a lot of people just kind of like, they think about it, they forget about it. And then when they need it, it's not there. So. Or they can't get it later because all of a sudden they have a heart attack and everything else. And then now when you want to get it, because you can see that certain things can happen. It's an arm and a leg. That's right. Okay. Same thing though is Michael, how much time you're getting ready to get acid on? Right.
Her camera's up. She's got a window where she's not feeding the baby or changing a poopy diaper. So we need to take advantage of it.
Okay, that's okay. And we're gonna let her go and I'm gonna show you. What do you do when you have someone 85 or 90 years old and they have a $400,000 mortgage or $300,000 mortgage? I just want to cover the whole mortgage. I don't care about anything else. I just want to cover the full mortgage. My wife's going to be okay. What do you do? You know, it's going to be crazy expensive. Or. Or I'm going to give it to you. While you think about it, what are you going to do and what is affordable for them? Think about it. I've got an 85 year old. I'm going to have a set 85 and a 75 year old in a little bit. They're going to have a $300,000 mortgage and that's crazy darn expensive. And they're sick and they have heart attacks. What are you going to do? How do you do it? When I mastered this, I took my business to the next level. And when you master this, you will watch yourself and succeed at a very high level. It is things that people at equity still to this day do not know how to master because no one taught them. There's always something on that one phone call. There's always that something on that one dial session. There's always something on that you miss. Literally can be the difference of you like hitting those producer or making a sale.