This content was created by Alexander Lorenzo. This content was uploaded by Alexander Lorenzo. This is a YouTube video titled "Did the US Government Just Turn Crypto Companies Into Banks?" (uploaded July 11, 2026). The excerpt is a single-speaker monologue explaining recent U.S. regulatory actions (June 18–22, 2026) by FinCEN, the OCC, the Federal Reserve, the FDIC and the NCUA proposing to treat permitted payment stablecoin issuers as financial institutions under the Bank Secrecy Act. The speaker outlines implications: requirements for written customer identification programs (CIP), risk-based identity verification, identity data collection, recordkeeping, SARs, OFAC/terrorist-list checks, and reliance on federally regulated institutions. They emphasize the rule targets direct issuer relationships (issuing, redeeming, reserve management, custody) rather than every secondary-market wallet, framing this as integration that could enable bank-grade controls, greater institutional trust, and wider stablecoin adoption into payment infrastructure. The speaker also briefly references personal claims about AI automated trading and a promotional link in their bio.
Chapters
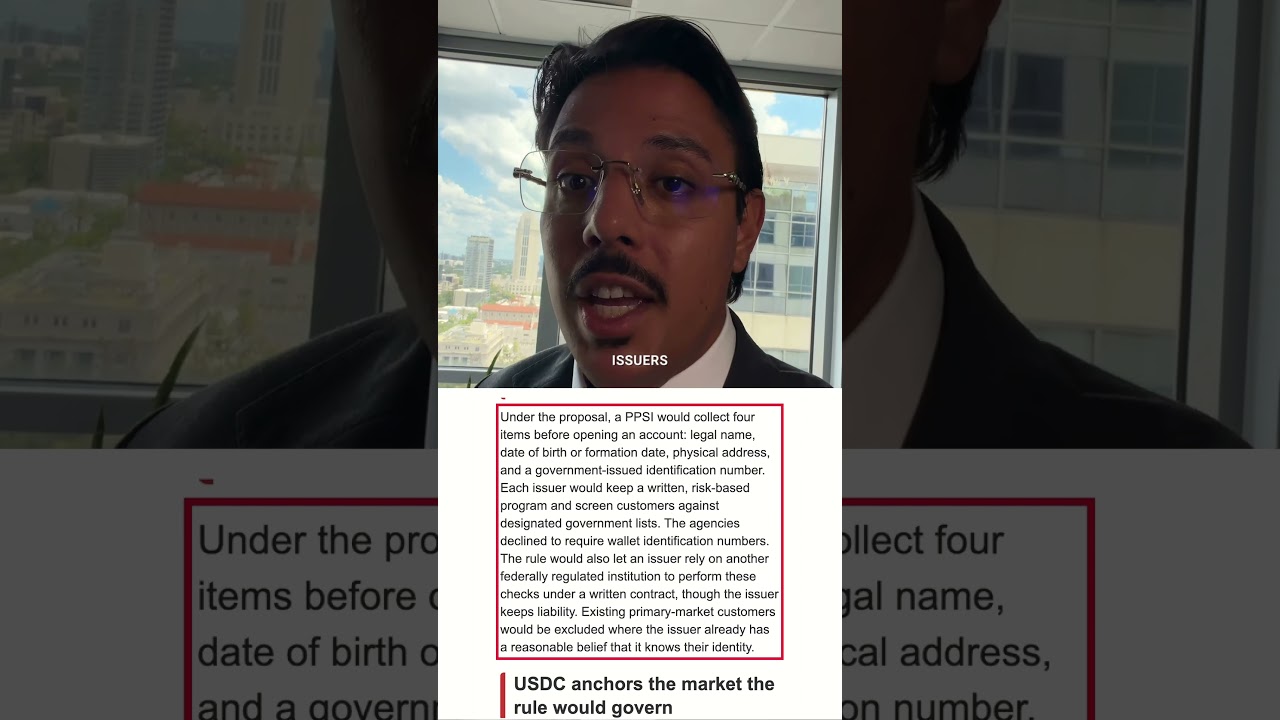
This sounds completely bearish until you understand adoption signal. Regulators are not treating stablecoin issuers like apps anymore. They're actually writing them into the same compliance system that actual banks use themselves. And there's a lot of money to be made with AI automated trading. I've been making millions off the system for years, and we just now automated it. Take advantage. Link is in my bio. On June 18th, 2026, FinCEN and the US banking agencies announced a proposed rule under the Genius Act. On June 22nd, It was published in the Federal Register. The agencies involved were the FinCEN, the OCC, the Federal Reserve, and the FDIC, and the NCUA. That's the first thing to notice. This is not a random regulator yelling about crypto. This is the US banking and anti-money laundering stack moving together. The rule would treat permitted payment stablecoin issuers as financial institutions under the Bank Secrecy Act. That means that these issuers would need effective customer identification programs, Similar to the identity rules banks use right now. Most people hear that and say, "Oh man, more regulation! Who cares?" But the deeper story is integration. The proposed rule requires a written customer identification program. Issuers will need risk-based identity verification. The basic information includes name, date of birth, and date of formation, address, identification numbers, and things like this. If the issuer cannot verify identity, it needs procedures for. for when not to open an account, when to restrict use, and when to close the account, and when to file suspicious activity reports. It also includes recordkeeping, checking customers against government terrorist lists, customer notice, and reliance on other federally regulated institutions. Now, here's the kind of nuanced part about these situations that people miss. This does not mean KYC every wallet on Earth. The Federal Register proposal says owning a payment stablecoin by itself is not automatically in an account. The rules are mainly about direct issuer relationships. We're talking about issuing, redeeming, reserve management, custody, safekeeping, and certain digital asset service provider activity. So the government is separating issuer infrastructure— listen— to secondary market wallet activity. And that's important. This fits a bigger picture. In April 2026, the FinCEN and OFAC proposed AML and sanction rules for stablecoin issuers. Then came customer ID layer by layer, the US is building the compliance package banks and institutions need before they can safely plug in. And this is why it's not just a regulation story, it is the distribution story. The companies can afford bank-grade controls become easier for banks, payment networks, and enterprises to trust. Regulation can slow weak players down, but it could also make winners easier to adopt And this is how stablecoins move from crypto product to permanent payment infrastructure. People should be happy because you can invest in a lot of these crypto platforms.