In this commentary, the speaker explains how major U.S. banks (JPMorgan, Citibank, Bank of America, Wells Fargo) and Visa are developing tokenized deposit networks that turn traditional bank deposits into blockchain-based, programmable, always‑on digital cash. The focus is on corporate treasury needs—liquidity management, settlement timing, cross‑border payments, and idle cash reconciliation—rather than retail use. Tokenized deposits keep funds on the banks' balance sheets while offering the 24/7, programmable capabilities of stablecoins, allowing corporations to move money on-chain and interact with tokenized assets. The clearinghouse infrastructure (CHIPS, EPN, RTP) and Visa’s global network will enable these rails to connect across institutions worldwide. The speaker argues this is banks’ strategic response to stablecoins, preserving deposit outflows, monetizing the service, and further driving crypto adoption by increasing demand for blockchain settlement, interoperability, custody, compliance, and smart‑contract payment rails. The narrative also hints at broader economic implications, noting that the richer institutions benefit while the poorer are left behind.
Chapters
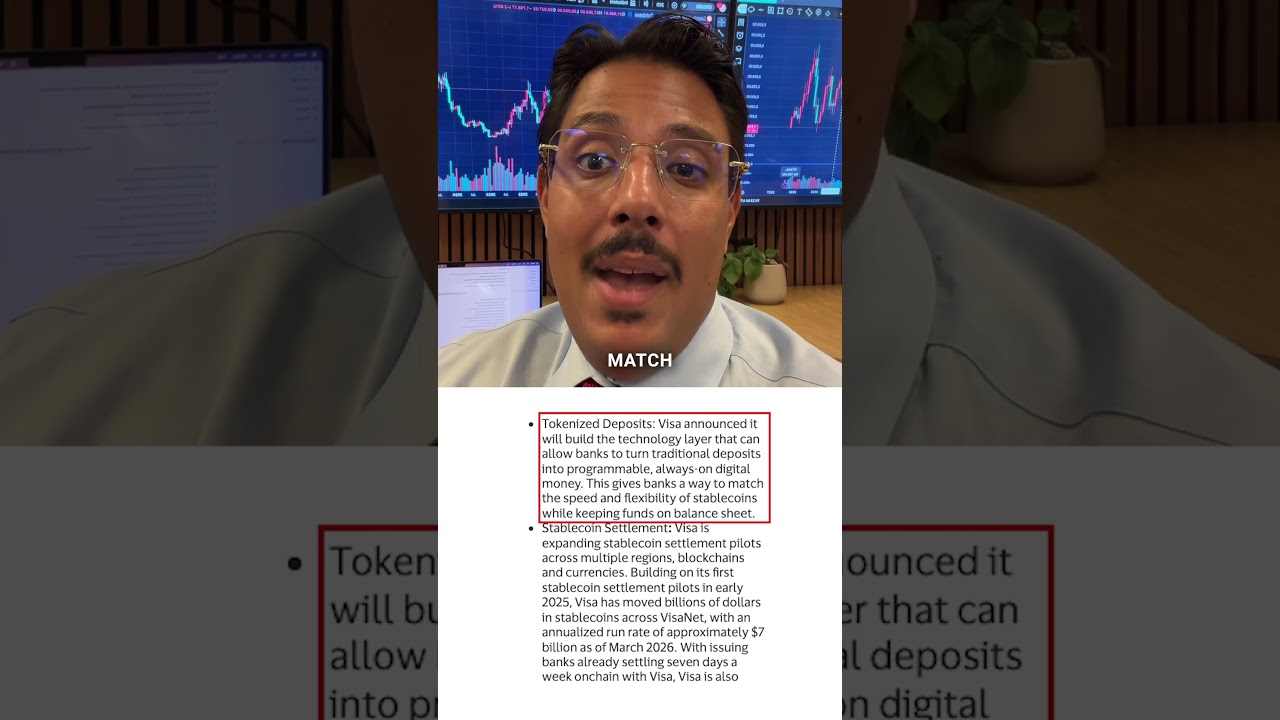
Banks are turning corporate cash into programmable money now. Tokenized deposits are the bank's defense against stablecoins. Corporate cash stays on the bank balance sheets but moves through a 24/7 market through programmable rails. What is going on? Tokenized deposits are not really a consumer story. They're a corporate treasury story. Corporate treasury means the investments of corporations. That is exactly why big banks care. A corporate treasurer does not wake up asking how to buy coffee with a stablecoin. They care about liquidity, settlement timing, cross-border payments, idle cash reconciliation, and whether the money can move when the markets are closed. They want freedom. Stablecoins prove that digital dollars can move 24/7. We know this, but big banks do not want corporate deposits leaving the banking system and moving into tokens issued by non-bank companies. They want to make money. So banks are building tokenized deposits. A tokenized deposit is a bank deposit representing a blockchain token. The money stays on the bank's balance sheet, but the movement can become programmable and always on 24/7. Visa said it's building a technology layer that can let banks turn traditional deposits into programmable Always-on digital money, and they're helping them. Visa said it lets banks match the speed and flexibility of stablecoins while keeping the funds on a balance sheet. The clearinghouse story points in the same direction. Major U.S. banks, including JPMorgan, Citibank, and Bank of America and Wells Fargo, are planning a tokenized deposit network operated by the clearinghouse themselves. The target is not retail payments; it's corporate treasuries, liquidity management, and eventually cross-border payments. By the way, this is what it looks like when the rich are getting richer and the poor are getting poorer. The clearinghouse already operates. Important bank payment infrastructure, including CHIPS, EPN, and RTP. So if it operates a tokenized deposit network, banks are not experimenting at the edge. They're already upgrading the core. Visa's own network already reaches more than 15,000 financial institutions across more than 200 countries and territories. That matters because tokenized deposits are not useful if they stay trapped inside one bank's lab. They become useful when they connect to the networks corporations already trust. This connects directly into crypto adoption because tokenized assets need tokenized cash. If a company buys tokenized treasuries, settles tokenized invoices, and moves collateral or pays across borders specifically, it needs a digital cash instrument that can settle at the same speed. Stablecoins are one answer, but tokenized deposits are the bank's answer. The crypto asset connection is that both models increase demand for blockchain settlement, interoperability, custody, identity compliance, and smart contract payment rails. Crypto already won the product argument. The banks are not copying the speculation, they're copying the utility— always-on programmable global money. But what they're going to do is they're going to adopt it everybody else and then get rich selling it to other people. When corporate money moves on-chain, the rails around it become more valuable. We saw a massive adoption of crypto corporate treasuries with Bitcoin, Ethereum. Now we're seeing it with bank deposits and a whole bunch of bigger institutions. The crypto adoption is real. As soon as they come to the public market, it's going to be an altcoin season frenzy.