This content was created by Alexander Lorenzo. This content was uploaded by Alexander Lorenzo. This is a YouTube video titled "THE BANKING ELITE IS QUIETLY PUMPING THE CRYPTO MARKET" (created 2025-12-20). The excerpt is a single-speaker monologue presenting a financial/crypto analysis: it discusses the federal funds rate and its effect on markets, argues banks profit from interest and conceal that fact, claims a recent law called the "Genius Act" legally allows banks to issue stablecoins, and describes a mechanism where banks take customer deposits, issue stablecoins, and invest those deposits in Treasuries to earn yield with little risk. The speaker asserts this creates a new, large liquidity injection into crypto (cites ~$400B stablecoin market cap but estimates actual liquidity in the trillions) and promises to provide proof in a subsequent video.
Chapters
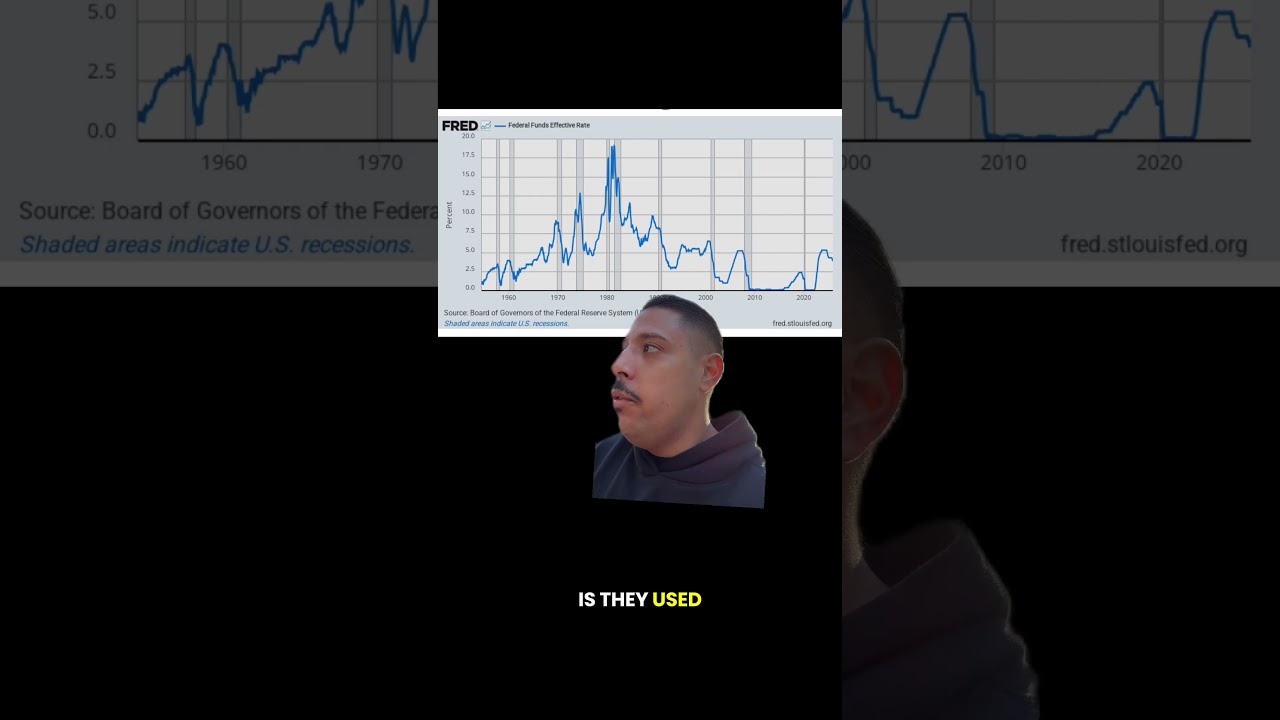
This metric exposes exactly why the market is dropping, and then it also shows when it's going to come back. What we're looking at here is the federal funds rate, which is pretty much the rate and the cost of borrowing money. The reason why this is the most important metric of all finance is because 71% of all of the liquidity and all of the money rotation in finance right now comes from credit. So typically when we have lower interest rates like this, very low interest rates usually lead to a big bull run. Look at where we're at right now. We do not have 0% interest rates. So this could be a reason to why we are not experiencing an all-out bull cycle. But just think about it for a second. Who makes money off the interest rates? The banks do. They are the one that put out the loans. They literally make money off of interest. It is their main revenue source, interest. All they care about is making money off of interest. Also, they care about public perception. They don't want the public knowing how they make money, where they make money, because if the public knows, they're going to realize that we're in a modern-day Ponzi scheme. And some of you already know that, but there's a lot of people that really think that banks are safe. Now, this right here reveals where the banks are now making money. This is important because it shows the trajectory of our financial system. This is called the Genius Act, and the Genius Act was a law that was passed in July that allows banks A completely new product for them to sell. They're allowed to legally create stablecoins. So now the banks have a new product to sell that will get them what they want, which is interest. Let me explain. If you want to buy into the bank's product, which is a stablecoin, you want to use the stablecoin for crypto, you can go to the bank and give them $100 grand. They will give you a stablecoin that you can use on crypto, but also they are legally allowed to take your $100 grand and get interest on it. So they take your real money, and right now we see from the public documentation that the vast majority of their money is going to paying back government debt, which gives them a yield. People don't know this, but the government actually offers a product. It's called Treasuries. You can go to the United States and say, here's $50,000. They give you a $50,000 coupon plus interest. That $50,000 coupon is called Treasuries. So remember, the banks gave you a stablecoin and you gave them $100,000. They're legally allowed to take that $100,000 and get yield from the United States government. The main product that banks used before is they used to give out loans to get interest payments. They would sign for a mortgage, which is a house loan or a car loan or any loan, and they get paid interest. But the thing is, if the person doesn't pay off the house, they can go in default. They— there's risk because the person doesn't pay their interest. If they don't pay their actual house payments, the bank is at risk. So now the banks have a new product to where they take no risk. Remember, the initial investment capital was your money in the first place. So you're giving them the money for them to get interest. And all they need to do is when you ask for your money back, they just redeem it. So what I'm basically saying is the banks have a new interest play without any risk at all. This is exactly why we see JP Morgan, arguably the creator of the Federal Reserve itself, launching its own stablecoin on Basis public blockchain. So what I'm basically saying is the 71% of liquidity that's in our current markets that leads to bull run is no longer through just bank loans and dropping interest. We have a completely new liquidity mechanism that's injecting money into the market, and the market has not understood this or caught up to it yet. We have the banking elite drawing liquidity secretly, and the market's going down because people have no idea what's going on. This is exactly why we're experiencing the largest adoption of stablecoins in human history. The market cap for stablecoins is $400 billion, but through the multiplication, I estimate it's in the trillions. The amount of liquidity that just came in through crypto is in the trillions. I can prove that. I'm gonna prove that in the next video.