In this YouTube video, real‑estate professional Austin Klar (a former lawyer) addresses common fears that the 2023 housing market is headed for a crash similar to the 2008 Great Financial Crisis. He outlines five key reasons why the current market dynamics differ fundamentally from 2008 and why a crash is unlikely in 2023. First, he shows that foreclosures, while up year‑over‑year, are still roughly 90% lower than the 2008‑2010 peak, and homeowners now hold record‑high equity, reducing the risk of mass defaults. Second, he points to tighter lending standards, illustrated by the Mortgage Credit Availability Index, indicating that banks are now far more selective than they were in 2008. Third, he highlights the stark contrast in inventory: today’s supply is about one‑million homes versus over four million at the height of the 2008 bubble, creating a supply‑demand imbalance that supports prices. Fourth, he explains that recent bank failures (SVB, Signature, Credit Suisse) stem from sector‑specific liquidity issues rather than poor mortgage‑backed‑security holdings, unlike the 2008 failures. Finally, he notes that Bay Area home prices, after a pandemic‑driven surge and a brief correction, are stabilizing and beginning to rise again as interest rates ease. Throughout, Klar emphasizes that the market’s challenges are tied to borrowing costs, not underlying asset quality, and predicts a resurgence in demand once rates continue to fall. He concludes with a personal invitation to contact him for market advice and a call to subscribe to his channel.
Chapters
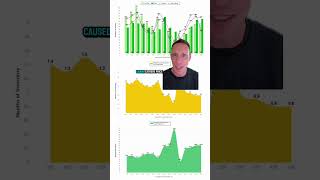
Banks are failing. The tech industry is laying off thousands of workers. Prices have started to fall from the red-hot peaks during the pandemic. People are seeing what's going on in today's market and thinking this is 2008 all over again and the housing market is about to crash. But in this video, I'm gonna break down 5 reasons why today's market looks nothing like 2008 and why a housing crash is not on the horizon for 2023. This is Austin Klar, your lawyer turned real estate agent, real estate developer in San Francisco. I have lived in multiple neighborhoods throughout San Francisco, giving me in-depth firsthand knowledge of what it's like to both live and work in the city. If you're thinking about relocating or want more information about the housing market, definitely reach out to me. My contact information is in the description below. I will personally answer every call, every email, every text, and I would be more than happy to help you. And if you like videos just like this, please consider subscribing to my channel, and don't forget to click the bell so you're alerted every single time I post a video. All right, so this video is all about why the conditions in today's housing market are nothing like the conditions in 2008 that led to that major housing crash back then. We're coming off an insanely hot pandemic market where median home prices across the nation soared, almost 50% in a matter of just 2 years, unlike anything we've ever seen in the housing market. After the Federal Reserve started hiking short-term borrowing rates and mortgage rates increased as a result, the housing market came to a screeching halt and prices have since started to correct. But as I'm filming this video, only a small chunk of those pandemic gains has been given up in this housing price correction. It's different market to market, certainly more in the coastal markets like here in San Francisco. But nationwide, the housing market has only given back a a small chunk of those pandemic gains. But just in the last few weeks, we've seen multiple bank failures. Silicon Valley Bank, Signature, and Credit Suisse all failed. There are different reasons why each of those have failed, but with the bank failures, with the layoffs that we're starting to see, with the home price correction, buyers and sellers today are wondering, is the market about to crash? So in this video, I wanna break down 5 reasons why the market today looks nothing like it did in 2008 and why the conditions that exist right now do not lend themselves to a crash in 2023. The first reason is that foreclosures today look absolutely nothing like they did back in 2008. One of the headlines you see in today's media is that foreclosures are up over 100% in 2022 compared to 2021, an indicator that there might be a housing crash on the horizon because an increase in foreclosures is one of the things that we saw back in 2008. But the amount of foreclosures we're actually seeing today is nothing like we saw in 2008. This graph shows the number of foreclosures since 2005 all the way through 2022. Mm-hmm. And as you can see, just like what the headlines are reporting, there were 324,000 foreclosures in 2022 compared to 151,000 in 2021. So yes, is it up over 100% like the headlines are reporting? You bet. But if you go back and look at what the number of foreclosures were in '07, '08, '09, 2010, in '07, in the lead up to the great financial crisis, there were 1.3 million foreclosures. In '08, 2.3 million. In '09, 2.8 million. 2010, 2.9 million. 2011, 1.7 million. 2.9 million. So yes, foreclosures are up in 2022 compared to 2021, but they're down about 90% from the peak that we saw in 2009 and 2010. So it's not as if there's going to be a wave of inventory coming to market because banks are foreclosing on all of these properties and then need to sell them to offload them and recoup their money. And you shouldn't expect a wave of foreclosures to come. Why? Because the amount of equity people have in their homes is still near record highs, notwithstanding the correction that we've seen since the peak of the the pandemic market. As you can see, the amount of equity people have in their homes on the far right of the graph has corrected since the peak of the pandemic market in the spring of 2022. But if you look at where it is compared to '08, '09, 2010, the aftermath of the Great Financial Crisis, it's almost double what it was at that time. So people have way more equity today than they did back in 2008. So you shouldn't expect a wave of foreclosures to bring a bunch of inventory into market. People are not underwater on their mortgages today. like they were back in 2008. Reason number 3 why today is nothing like 2008 is because lending standards are incredibly more strict. This graph shows the Mortgage Credit Availability Index from June of 2004 through the beginning of this year. The Mortgage Credit Availability Index is basically a barometer of the availability or supply of mortgage credit using different criteria from, you know, various institutional investors who purchase loans through brokers and other channels. A higher index means that More credit is available while a lower index means less credit is available, supply is tighter. Basically, the lower the number, the harder it is to get a mortgage. And as you can see today compared to 2008, it is substantially more difficult to get a mortgage. Back in '08, banks were lending to consumers with no income, no jobs, no assets. And when the economy started to correct, they couldn't afford their mortgages anymore. They were going underwater on their mortgages. And that's why there were so many foreclosures at that time. And as you can see, because people have more equity in their homes today almost than ever before, and because lending standards are much more strict, chances are people are going to be able to withstand corrections in the housing market. They're still gonna be able to afford their mortgages. They have enough assets to cover their payments. They have enough equity in their home that they're not gonna go underwater on their mortgage. Reason number 4 is that inventory today is nothing like what we saw during the housing bubble in 2008. During the 2008 housing bubble, there were a record number of homes available. Inventory was at all-time highs. Demand was not available to satisfy that supply. And notwithstanding, prices kept going up, which is not what you would expect in normal rules of supply and demand. When demand is lower than supply, typically prices go down. But in the housing bubble, prices were going up. That inventory situation is not what we're seeing today. There were over 4 million homes available at the peak during the housing bubble, and today there's just about 1 million homes available. And those houses are selling at a relatively quick pace because there's substantial demand for housing. If you look at this graph of inventory just over the past couple of years, you can see where inventory sits today at this dark red line in the middle, which is for 2023 as of the last week of March, compared to what we saw in each of 2017 through 2022. And it— you can see, yes, it's above the pinch pandemic years where inventory was at record lows, but it's about 50% below what we saw in 2019. And it's well below what we saw in 2017, 2018, and even most of 2020. In 2017, '18, '19, you know, all of those years were considered incredible years in real estate. Inventory was still tight then, not enough inventory to satisfy the overwhelming demand for housing. And the same is true today. Millennials and Gen Zers make up a huge portion of the home buying population. They're reaching the prime age for home buying. There's a lot of pent-up demand to buy homes. The reason why a lot of people are sitting out of the market right now is because interest rates are so high. But the second those rates even come down a little bit, you should expect to see a huge burst in demand, and there's just not enough supply of homes to satisfy that demand. So inventory is low, demand is very high. That's the opposite of what we saw in 2008, where inventory was high and demand was lower. And getting even more granular, you can see how low inventory is here in the Bay Area compared to what it was in the Bay Area in 2008. On the far right side, you have inventory levels as of February of 2023 in 4 different Bay Area counties. And if you look on the left side, the peak of the GFC, 2008, 2009, you can see that the inventory situation, both from a month's supply of housing standpoint and active listing standpoint, it's a much, much different picture. There's simply not enough available inventory to satisfy the overwhelming demand for housing, even in today's higher interest rate environment. The 5th reason today is nothing like 2008 is because the bank failures that we've seen so far have not been caused by any issues with the underlying assets of the banks themselves as they relate to housing. Whereas back in 2008, the reason these banks failed is because they were heavily invested in mortgage-backed securities. And because those mortgages were lent to people with no income, no jobs, no assets, they weren't good, healthy assets. Silicon Valley Bank, for example, failed because it had a very unique customer base. It was very tech-focused, very startup-focused, a lot of cash-intensive businesses that don't generate a lot of cash flow. They need a lot of cash and a lot of investment and as interest rates rose and borrowing became more expensive, that money that they needed wasn't as readily available, so they had to go into their reserves to the bank. The bank, because it was mismanaged, did not have enough money to cover all of those requests for withdrawals, and as a result, there was a, there was a bank run. Everybody rushed to get their money out as quickly as they can because they were worried they wouldn't be able to if they waited any longer, and the bank failed. The bank's failure had nothing to do with the underlying quality or non-quality of its assets, of, for example, mortgage-backed securities. And what you've seen in recent weeks, like you often see during times of economic uncertainty and in recessionary periods, there's a flight to safety or a flight to quality. Investors are taking their money out of what they deem risky assets and putting them into things they deem safer. And one of those things they deem safer are mortgage-backed securities because those mortgages, they know because of these tight lending standards that I talked about earlier, these mortgages are unlikely to go into default. They're unlikely to go into foreclosure. They are much safer for less risky assets than the equities market today, for example. Not only is there a belief that the mortgage-backed securities are a safe investment because of those lending standards, you actually look at what's going on with home prices in real time. Yes, they're down year over year, but at least here in the Bay Area, they're actually trending up. You can see from their pandemic peaks in the spring of last year, both from a price per square foot standpoint and an average sale price standpoint, um, they peaked in spring of 2022 and then they trended very sharply down relatively quickly. Mm-hmm. Once the Fed started increasing rates. But as you can see, in 4 major Bay Area counties, uh, Santa Clara, Alameda, San Francisco, Marin, prices are leveling off toward the right. They're starting to level off. And as of early this year, January, February, March, prices are actually on their way back up. So those are the reasons why what we're experiencing right now is not a precursor to some major housing crash. Just the situation today looks nothing like 2008. There's such little inventory out there, and there's still more demand than that inventory is able to satisfy. There is no underlying issue issue with mortgages, with homes themselves. It is simply an issue relating to the actual cost of borrowing and the cost of ownership. Interest rates have been coming down over the past 5 months. They're going to continue coming down as inflation gets under control, as the economic picture becomes more certain, less volatile. And once that happens, there's going to be an immediate resurgence in demand. We've already seen it this year in little peaks as mortgage rates have come down. So there is not going to be a major housing crash this year. If you were thinking that there's going to be a housing crash, I would love to to talk to you about that and see what data you're relying on so that we can get to the bottom of it and make sure you really understand what's going on in today's market. If you do wanna chat about that or you have any other questions about the market, or if you're thinking about relocating, definitely reach out to me. My contact information is in the description below. Like I said, I will personally answer every call, every email, every text, and I would be more than happy to help you. And if you like videos just like this, please consider subscribing to my channel and don't forget to click the bell so you're alerted every single time I post a video. Hello.