In this market‑update video, lawyer‑turned‑real‑estate agent Austin Klar analyzes San Francisco’s single‑family home market for Q1 2024. He explains that despite higher mortgage rates than a year ago, prices are up because inventory is extremely low while demand remains very strong. Using weekly and quarterly data, he shows that inventory and new listings are near historic lows, months‑of‑supply are well below the 4‑5 month neutral range (1.7 in Jan, 1.4 in Feb, 1.1 in Mar), and absorption rates are near 100%. Closed and pending sales are both higher than Q1 2023. Prices have risen – average price up 8.7% YoY, median up 3.5%, price‑per‑square‑foot up ~2% – and homes are selling quickly (average 25 days) and often above list (≈105%). Fewer homes are taking price cuts than in recent years. Klar concludes that, barring a sudden supply surge or a dramatic rate hike, prices should stay stable or rise, especially if the Fed begins cutting rates later in 2024. He invites viewers to subscribe and contact him for personalized advice.
Chapters
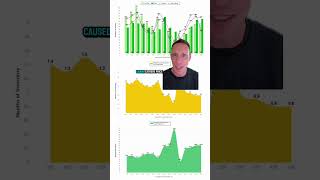
Interest rates are higher right now than they were at the same time last year, yet prices for single-family homes in San Francisco are actually higher, and it's because we have extremely low inventory and very high demand in relation to supply, and that is keeping prices elevated, and there are no signs in the data suggesting any change to that trend anytime soon. I'm Austin Klar, your lawyer-turned-real estate agent in San Francisco and Marin County, and in this video, I'm gonna break down everything that happened in the San Francisco real estate market for single-family homes in Q1 of 2024. So whether you're buying or selling or just wanna keep a pulse on the market, you know exactly what's going on and can make the best decisions for yourself based on data. So let's get right to it. Now, the key to everything is supply and demand. And what's most interesting, at least to me so far in 2024, is where inventory sits compared to last year. Even though we have higher interest rates right now than we did at the same time last year, inventory is actually lower. You'd expect for things to be lingering on the market longer and for inventory to be growing. And while inventory is technically growing, it is a lot lower than what we saw the same time last year. If you look at this black line right here, which represents 2024 on a weekly basis, basis, you can see where it shakes out to each of the prior 4 years. And the only year that was actually lower than where we are right now on an inventory basis was the very start of the pandemic, where nobody was listing their homes because everybody was freaking out. Nobody knew what was going to happen or what was going on. So inventory was already very constrained during the, you know, height of the pandemic and was very constrained in the aftermath of the pandemic. And it continues to be incredibly strained, and we're just not seeing any signs of some crazy spike in inventory that totally outstripped existing demand. And you can see that the number of new listings isn't really spiking either. This black line, same, representing, uh, new listings on a weekly basis for single-family homes in San Francisco. The only time where there were fewer new listings at this time, uh, in each of the last 4 years was at the very beginning of the pandemic when nobody wanted to list their homes because they were scared out of their minds of what was going on. Nobody was out there buying homes. Nobody could leave their house. So inventory is incredibly constrained. And on the flip side, we're actually seeing higher demand even though interest rates are higher right now. So if you look at months of inventory based on pending sales, basically how long it would take for all existing homes to go into the pending state to get into contract, anything below, you know, 4 to 5 months, which is a neutral market, is considered a seller's market. And anything above that is considered a buyer's market. And you can see in Q1 of 2024, demand is very, very high from a monthly supply standpoint, 1.7 months of supply in January, 1.4 in February, and 1.1 in March compared to 2.2 last January, 2 last February, and 1.6 last March. So overall, you know, all of these numbers show a pretty robust, you know, seller's market for single-family homes in San Francisco. But these numbers right here, the, the sub-2 months and really close to 1 month of supply in March, that is incredibly high demand in relation to existing supply. It just means there is more than enough demand to satisfy the limited number of homes that are actually on the market. And it's the same story when you look at it from an absorption rate standpoint. Absorption rate is the percentage of homes that are on the market that get into contract. And as you can see in March, pretty much every single-family home that was on the market in San Francisco got into contract. And as you can see over Q1 of 2024 compared to Q1 of 2023, absorption rates were much higher. So even though we have higher interest rates right now, because we have lower inventory, absorption rates are higher and monthly supply supply is lower. All that means higher demand. And on an absolute basis, you can see that higher demand play out both with the number of closed sales and the number of pending sales. Closed sales Q1 of 2024, uh, 395 compared to 351 Q1 last year. Pending sales 504 Q1 of 2024 compared to 390 last year. So both, uh, closed sales and pending sales are both up. Monthly supply is down. Absorption rates are up. All of that means more demand in relation to supply. — and you can see that greater demand have an impact on pricing. If you look at where things stand Q1 of 2024 on a price per foot standpoint compared to where it stood Q1 of 2023 is up about 2% and on an absolute basis average prices up each of the last 3 months compared to the 3 months starting of 2023. Same thing with median prices, uh, up each of the last 3 months compared to where things were Q1 of last year overall. Uh, average sold prices up 8.7%. for this last quarter compared to the same quarter last year. Median price is up 3.5%, uh, this past quarter compared to the same quarter last year. And you can also see that greater demand play out with days on market and how much homes are going above list price. Days on market was a pretty staggeringly low 25 days. You know, in a little bit over 3 weeks, homes were selling on average in San Francisco, which is really, really fast. They were selling for on average about 105% of list price, and last month 104% of list price. And you See how that compares to, you know, where things stood last year. Still pretty robust, getting almost ask or a little bit above ask in Q1 of last year, but it's even more robust now for sellers than it was at the same time last year. And another way to look at the demand side is to see how many homes are taking price cuts. So at current interest rates and current prices, which we know are higher than the same time last year, what percentage of homes are taking price cuts? And you could see the black line representing 2024 on a weekly basis. Less homes are taking a price cut than homes did in 2022, in 2020, and in 2023. The only time, you know, in the last several years where homes took fewer price cuts than they were right now was in 2021, which is like in the peak of the pandemic market. So overall demand at current prices and at current rates in relation to current supply, very, very robust. And what that means going forward is that you should expect price stability, perhaps even some upward momentum on prices, especially if interest rates do start to come down. And unless the variables change, unless we get a huge uptick in supply, which we're not seeing in the data, at least not yet, or any further crash in demand, like if interest rates, you know, reached 8% again or went even higher, which we don't really foresee, especially because predictions are that the Federal Reserve is going to start cutting the federal funds rate in the summer of this year, maybe a little bit later than that. But as inflation continues to get under control, the job market continues to slow down, expect interest rates to actually come down, not go up. Don't expect major shifts in the supply-demand equation that is going to lead to some, you know, dump in single-family home pricing in San Francisco. It is likely to remain robust because of how much more demand there is in relation to supply. This market is incredibly challenging and changing every single week. If you're curious about what these changes are and how they affect you, whether you're a buyer or a seller, or you're thinking about getting into the market at some point, Make sure to subscribe to my channel for more videos just like this. And if you have any questions or want to talk more about what's going on, definitely reach out to me. My contact information is in the description below. I will personally answer every call, email, and text, and I'd be more than happy to be a resource for you. Look out for more updates, and I'll see you in the next video.