In this instructional video, CPA Bill Hanna walks controllers through the entire financial consolidation process using a three‑step framework: Combine, Eliminate, Consolidate. He begins by explaining why consolidation is required when a parent company holds more than 50% of a subsidiary, illustrating the need to combine balances, eliminate intercompany transactions (receivables/payables, investment in subsidiary, subsidiary equity), and finally consolidate the results while accounting for any non‑controlling interest (NCI). Hanna then demonstrates the method in a real Excel example involving Fintech Inc. (parent) and Tiny Quarter Inc. (90% owned subsidiary). He shows how to add the trial balances, record elimination journal entries (including the use of a separate elimination entity in ERP systems), remove the parent’s investment against the subsidiary’s equity, and calculate the NCI for the 10% owned by outside shareholders. Throughout, he emphasizes practical tips, encourages viewers to download the workbook, and reinforces the importance of accurate intercompany eliminations for a fair representation of the consolidated financial position.
Chapters
Hey guys, welcome back to another video with your favorite financial controller, Bill Hanna, here bringing about 20 years of experience in corporate accounting as a controller. Today's video is about financial consolidation. So we're going to try to make the consolidation process as painless as possible by doing 3 easy steps. Step 1: Combine. Step 2: Eliminate. Step 3: Consolidate. So the concept of financial consolidation comes from representing the economic position of the company fairly, right? That's why we do all of these things. So I'm going to show you some of the concepts that go along with these processes here on the whiteboard, and then we'll jump into an Excel file where I'll show you an actual consolidation example of the financial position.
So let's talk about these steps here.
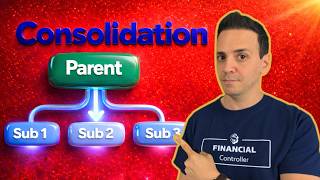
So when we talk about combination, why do we combine? So imagine you have a parent and the parent has interest in 3 subsidiaries: Sub 1, Sub 2, and subsidiary number 3. Now, the consolidation process comes into play when we have significant control. So significant control exists typically when we have more than 50%, 50% plus ownership. So the parent owns more than 50% of each of these subsidiaries, For our case here, we're going to assume that we have significant control, ownership more than 50%. Now that means we're going to have to consolidate. So consolidation means that we consolidate the books of those entities all together. Now combination is because imagine if the parent has $100 and the subsidiary number 1 has $100.
Also.
Now, when you combine, that means together they have $200, and that is fair because the parent has $100, the subsidiary has $100, together they have $200, and that makes a lot of sense. Now, imagine if in this case here the parent lends some money to the subsidiary. The parent lends to subsidiary number 2 $500. That means that parent here is owed $500, and we call it AR. It's an intercompany AR, right? And subsidiary owes to the parent $500, right? They have a payable, an intercompany payable. We call it AP, intercompany AP. So we have here a situation where the parent lends the sub $500. Now, when you combine, you have to do what we call eliminate. Why do we eliminate? Because as a combination, as a consolidated position, together they wash out. The parent is not owed any money from the outside world, and the sub doesn't owe any money to the outside world. It's all within the same house, so you have to eliminate these together.
So we talked about combination—
why do we combine some things? Why do we have to eliminate some of the things? There are some other things that we have to eliminate, and we then— we have to consolidate When we consolidate, we have to consider whether there is a minority interest. What is minority interest? Minority interest mean if the parent owns instead of 100%, if the parent owns 90% interest in one of these subs, that means that there is 10% that is owned by someone else. Could be another shareholder, right? So you have to display that on the consolidated financials as something we call NCI or non-controlling interest. Okay, so let's now move away from all of this stuff on the whiteboard and jump into a real-life example in an Excel file. Let's go.
All right guys, so jumping right ahead into an Excel file example. And by the way, before we go any further, if you're enjoying this video, go ahead and hit that like button, which is a big favor to me so that it helps this channel grow and reach more viewers. Okay, So we have here the balance sheet as of December 31st, 2025 for a parent, Fintech Inc., and a subsidiary, Tiny Quarter Inc. Okay, let's read that scenario together. Uh, Fintech Inc. purchased 90% stake in Tiny Quarter Inc. common stock on December 31st, 2024. So one year ago, uh, Tiny Quarter, the subsidiary, equity on December 31st, 2024 acquisition date, right after the acquisition. Common stock, $4,000. Usually that's recorded at par value, usually that's pennies. Additional paid-in capital, $7.9 million. Retained earnings, or rather here because it's negative, it's a retained deficit of $1.3 million. So it looks like they have been losing money prior to this acquisition. Fintech paid $6 million for this investment. This file here, by the way, can be downloaded in the description. Go ahead and download the file if you want and pause the video so you can follow along with this example. Okay, so the ask here is to prepare the consolidated balance sheet on December 31, 2025, which is 1 year after the acquisition. Be sure to perform the following: eliminate intercompany accounts, eliminate investment in sub, and calculate minority interest. Okay, let's go ahead and go through the steps together. So we said step 1, combine. Step 2, eliminate. Step 3, consolidate. So step 1, combine. This is the easiest of the steps. We're just going to go ahead and add up the assets, liabilities, and equity straight up from the parent and subsidiary. So remember, the parent owns 90% of the sub, but we're going to record— we're going to combine 100%, and then we're going to go ahead and record what we call non-controlling interest for the other 10%. That is not owned by the parent. So combination, easy, equals the asset here, which is cash and cash equivalent, plus the asset here for the sub. Let's go ahead and perform the same thing for every account that we have here. And again, we are just here combining. We're not doing anything special, nothing complicated. We are just combining. All right, that's great. So we combined all of the assets and liabilities and equity accounts for the parent and the sub. Now we'll go ahead and eliminate. All right, when we eliminate, we're not going to touch cash. Cash is— can be combined. Accounts receivable can be combined. Receivable from subsidiary. So the parent has $100,000 receivable from subsidiary, and we'll see there is a corresponding account on on the liability side payable to parent for the same amount, $100,000. So we'll go ahead and eliminate that. So we'll put an entry for $100,000 as an elimination. We're going to eliminate that both for the parent and the sub. And by the way, elimination are journal entries that are recorded. However, this is very important, they're not recorded on the books of the parent nor the sub. They are recorded in a separate entity we call an elimination entity. So this is an advanced topic of accounting. Um, you probably experience this if you're an accounting manager and above. You will do as a consolidation using a third entity in the accounting software, ERP. That entity is called elimination entity, where you record these elimination entries, um, not directly on the books. This is very important, not directly on the books of the parent and the sub.
Okay.
So we eliminated the receivable from sub and the payable to the parent. The next one you'll see is investment in sub. So the investment in sub, this is what the parent recorded when they made the investment in the subsidiary. And the corresponding item here on the subsidiary is going to be the common stock and the additional paid-in capital. So we'll go ahead and eliminate this account, equals negative $6 million. When we continue here, we have plant and equipment. We're not going to eliminate any of that. That can't be combined. Accounts payable, fine, we can combine. Accrued expense, the payable to parent, we said we're going to eliminate that, so we put a negative. Deferred revenue can be combined with no issue. The same thing for long-term debt. When we get to shareholders' equity, that's when we'll do our elimination. So we're going to eliminate the entire equity here of the subsidiary. So we're going to put a negative and remove all of it.
Okay.
So we're going to remove the common stock elimination, additional paid-in capital is eliminated. For the equity account, we're going to eliminate the $300,000. Retained earnings, but we're also going to calculate the 90% of the net income of the current year and eliminate that as well. So let's go ahead and do that together. We're going to eliminate 90% of the net income for this year. Let's, um, highlight this and let's go through the calculation. But before we go any further, if you are enjoying my teaching style and feel like you're ready to invest in a full accounting training program, be sure to check out the Controller Academy which is the course where I teach you my experience as a controller, and I teach you the entire function of the financial controller. If you're interested, go ahead down below to the description where you'll find the link. In the course, I teach you using a company example so you can see all of the steps it takes to create a world-class accounting process. I walk you through this setup of billing, accounts payable, equity accounting, payroll, among many other topics. We discuss revenue recognition under ASC 606 using real-life customer agreements. I also show you how to prepare and analyze the financial statements. If you're interested, head over to the website and check out the full curriculum. And now back to the video. All right, so we said for the elimination of retained earnings of the subsidiary, we're going to eliminate the balance of retained earnings plus we're going to eliminate the portion that belongs to the parent from its current year net income. So when we do that, we'll say, okay, on acquisition date, the retained earnings balance was $1— negative $1.3 billion, and then at one year later, it became $300,000. That must mean that net income for the current year was equal to $300,000 minus what we had before. So the subsidiary must have earned this year $1.6 million. So we go ahead and calculate 90% of this amount. So 90% is going to be equal to this number times 0.9. Okay. So that means the interest that the parent has in this retained earnings is $1.47 billion. We're going to additionally to the $300,000 here, We're going to eliminate further another 1.47, so we're going to say plus this number. So the elimination of retained earnings is $1.17 million. Okay. So we eliminated the equity accounts of the subsidiary right here, and now the final step in this elimination process is to record what we call noncontrolling interest. So we're going to add an entry here. I'm going to call it non-controlling interest. Okay? The amount of non-controlling interest is going to be calculated as the amount that the parent does not own in the subsidiary. Now, we said this parent owns 90%. That means 10% is owned by someone else. So you're going to take 10% and record it here, the 10% of the equity of the sub. So we'll do this here on the side here. NCI, or non-controlling interest, is going to be equal to the equity of the sub times 0.1, that's 10%. So we'll go ahead and grab this number. And that's going to be the number that we have for non-controlling interest. Now for our final step, we're going to go ahead and consolidate. So to consolidate, we'll combine the column, the combination column with the elimination column. So we'll say consolidate equals what's in a combination plus what we eliminated. So we'll go ahead and drag this down and repeat that for all of the accounts that we have here on the balance sheet. And our equity is already here combined with the same formula. Okay, great. So final check, notice that I have a check here at the bottom that says my assets, total assets minus liabilities and equity, just to make sure that I am in balance. The balance sheet has to be in balance, assets equals liabilities plus owner's equity, which seems to be fine here as well. Okay, so again, this file is available for download, uh, down below. Go ahead and download it. This has been a simplified approach to how to combine the balance sheet for a parent and a sub, um, as painless as possible. I hope that you guys enjoyed it. If you did, go ahead and hit the like button. Subscribe if you haven't subscribed to the channel because that's going to go a long way in helping me out. And I'll see you in the next video.