How to save taxes via FHSA first home saving account #taxcompliance
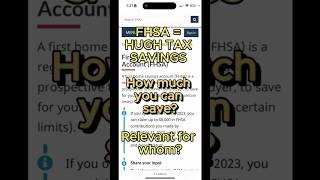
In this Hindi-language tutorial, the presenter explains how the First Home Savings Account (FHSA) can be used to lower personal income tax. The video outlines who the program is relevant for – primarily first‑time home‑buyers – and clarifies that it does not apply to people who already own a home. It details the annual contribution limit (up to $8,000 per year, with a deadline of December 31) and shows how each contribution directly reduces taxable income. The speaker walks through a concrete example, mapping the contribution amount onto Canada’s marginal tax brackets (e.g., 20‑29% and 29‑39% brackets) to illustrate the dollar‑for‑dollar tax savings, especially for those in the 29‑30% bracket where a $3,000‑$4,000 contribution saves roughly 24% in tax. The overall message is that strategic FHSA contributions can provide a meaningful tax reduction for eligible first‑time home‑buyers.
Chapters
More from Cpa

Ask yourself 3 questions:1. At what age you want to retire? 2. how much money do you need ?