In this solo episode of Weeks Weekly, Ed Weeks Jr. explains what a sell‑side quality‑of‑earnings (QoE) report is, why it matters, and when a seller should commission one. He describes the report’s core tests—add‑backs, revenue recurrence, working‑capital norms, and proof‑of‑cash— and stresses that discovering issues before a company hits the market lets sellers fix or document them, whereas findings after a letter of intent can erode price. Weeks shares a rule‑of‑thumb that founder‑owned firms valued above roughly $10 million should spend $60 k (range $35‑75 k) on a sell‑side QoE, while smaller deals often balk at the cost. He illustrates how rejected add‑backs can shave hundreds of thousands off a valuation. The episode also covers a regulatory change: since Oct 1 SBA lenders must order an independent QoE for purchases of $3 million or more, and must base loan sizing on the earnings the report supports (now at 1.25× coverage). Consequently, sellers using SBA financing will face a QoE regardless of who commissions it, making early insight valuable. Weeks recommends starting the process about six months before a planned market launch, cleaning monthly closes and documentation now, and using the report as a diagnostic tool even if a sale isn’t imminent. He concludes with a brief personal anecdote about selling an e‑commerce business (Goldleaf) and directs listeners to the full article and sources in the description.
Chapters
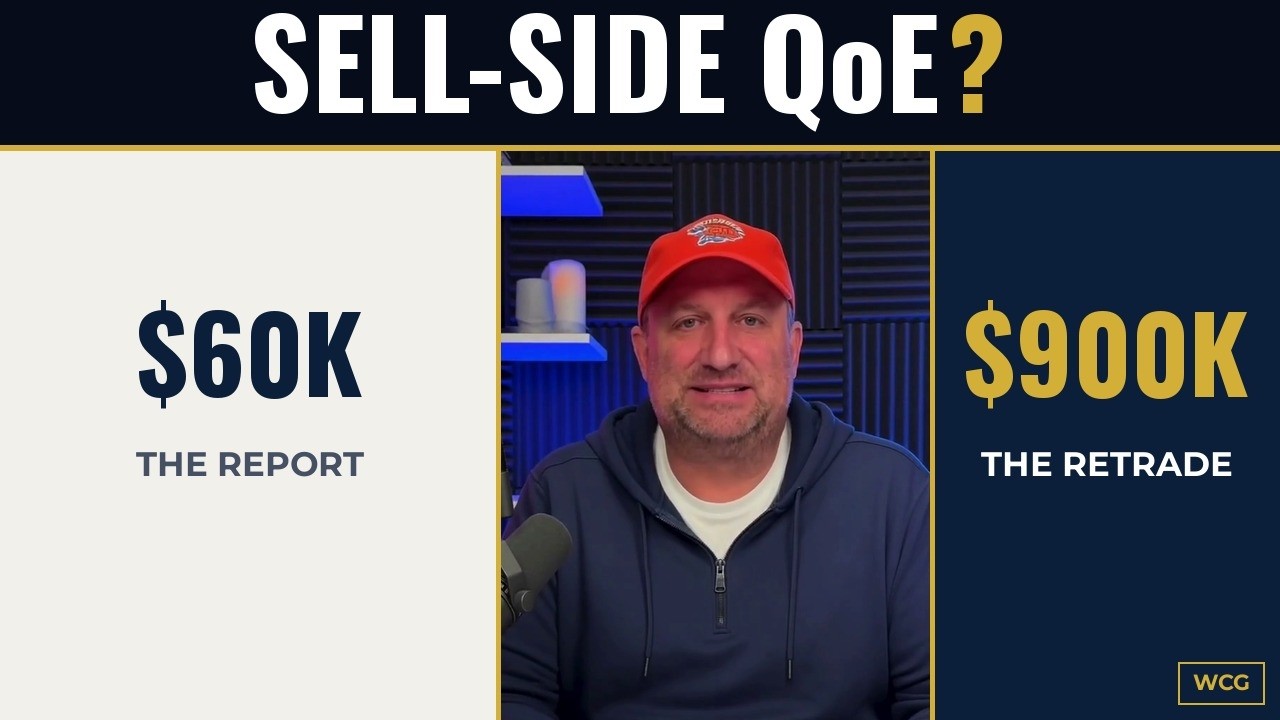
Welcome to Weeks Weekly. I'm Ed Weeks Jr. This week, sell-side quality of earnings, and whether it's worth paying for before you sell. If you sell a company of any real size, someone is going to test your earnings. The buyer hires an accounting firm. That firm spends weeks inside your books, and the number they come back with is the number the rest of the deal is built on. The only question is whether you see that work first. That's what a sell-side quality of earnings report is. You hire an independent firm to do roughly what the buyer's firm will do before you go to market. It tests your add-backs. It tests how recurring your revenue is. It sets a normal level of working capital. And it runs a proof of cash, tying what your books say to what actually moved through the bank. Why does timing matter so much? Because a finding before you go to market is something you fix or document. The same finding after you sign a letter of intent is a reason to cut your price, and by then you've agreed to exclusivity, And stop talking to other buyers. I talked recently with a quality-of-earnings provider who works both sides of deals. He's seen a lot of buy-side engagements over the last 18 months where the seller did no prep work and value moved toward the buyer. So who should get one? His rule of thumb: a founder-owned company worth more than about $10 million should have one, even at around $60,000. Below $10 million, he said sellers are hard to convince to spend $35,000 to $75,000. Many realized they needed it near signing, when working capital and quality of earnings findings hit the purchase agreement. Here's the math: at 6 times, $150,000 of rejected add-backs is $900,000 off your price. That's an illustration, not a promise. Now, the part that changes things for smaller deals. Since October 1st, SBA lenders must order their own independent quality of earnings report when the business purchase price is $3 million or more. A report you commission as the seller doesn't satisfy that rule. And, the lender has to use the earnings that report supports when it sizes the loan— now at a stricter 1.25 times coverage. So if your likely buyer is using SBA money, a Quality of Earnings report is coming whether you prepare or not. The choice is whether you see the findings first. When to start? The same provider suggested about 6 months before you're ready to go to market, Earlier, and the numbers go stale and have to be rolled forward. Later, and the report isn't ready when buyers want it. I've been on the seller's side of this. I bought an e-commerce business called Goldleaf, ran it, and eventually sold it to partners who were better positioned to take it forward. When you're the seller, you know the story behind every number. The buyer only knows what can be checked. So here's what I'd do. If you're above $10 million, plan for a sell-side report. If your adjusted earnings are well above your tax return, test the gap. If your buyer is likely using SBA financing, see your findings before their lender does. And if a sale is a few years out, start with monthly closes and clean documentation now. None of that commits you to selling. Knowing what your earnings look like to an outsider is useful whatever you decide. The full article and sources are in the description. I'm Ed Weeks Jr. More at edweeksjr.com.