Financial guru, Suze Orman joins David Kessler to give tips on money matters during a pandemic
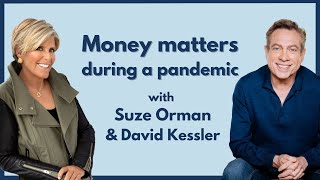
Suze Orman talks with David Kessler about money decisions when you're grieving during the pandemic. She covers what to pay first, how to handle debt and creditors, whether to set up a will or living trust, and why you shouldn't make big financial moves for six to twelve months after a loss.
Questions this video answers
2002
December 20, 2019
About $11.3 million (current threshold referenced in the livestream)
Regular price $199; discounted to $69 via susieorman.com/kessler
Approximately 12 hours 30 minutes (streamable for ~30 days)
Chapters
Susie.
Hello, my dear David. How are you tonight?
I'm good. I'm so honored to have you here. You are just the best. And the idea that you're coming on and helping so many people is just so amazing. And I. I know the public, Susie Orman, and I know the private one, and you are so generous. I just. I just love you. And, you know, you've just been such a hero of mine, and you've helped me with finances over the years, just whatever, you know. And that's not that you've been personally helping me, that's just. I'm just like a. I am one of your customers because I've just been watching you on tv, and your. Your generosity of information has just been wonderful. So it's no surprise in a pandemic, we're turning to you.
Thank you, sir.
We are turning to you during this time, so. So people are joining us from all over. They'll be coming on from all over the world. I'll give them just a moment. And for any of you who are joining for the first time, this is a group that I've set up in response to COVID19. So many people had loved ones die right before, were struggling with loss already, and their grief group got shut down. Couldn't have a funeral, couldn't go and see loved ones. All of this in a pandemic. And grief is isolating on a good day and in a normal world. And we're in such an abnormal world. So I wanted a place for people to come. And so many of you have showed up for yourselves to be here. And I have, like, amazing guests who are coming on, like Susie, because we want you to know, while the world's talking about reopening and moving on, if your loved ones died, it's not that easy for you. So we're here to say you matter and you help. We're here to help. And I'll tell you, I think of the total person, and, you know, people think, oh, grief. What about their sadness? I know you're in grief, you're sad, you're angry, you're lonely, and you have financial problems. That's why it's such an honor for you to be with us, Susie. And I just so love you for being here. So as people are coming on, one of the things I just want to start with is we're all here because someone we love has died, maybe more than one person. So if we could just take a moment in honor of that person, send them love wherever they are in your heart. Heaven, afterlife, wherever. So join me in that, if you would.
Thank you so much. I so appreciate you all doing that. I love that you're all here and still coming on from all over the world. So, Susie, you're no stranger to grief. You've dealt with loss yourself.
Yeah.
You know, you're more than the financial person. I have heard you talk many times about your mom.
How's your world been about these things?
Well, you know, David, I think I want to believe it or not. I want to tell you a little bit different story that I normally never tell. And it's a story that I think very few people know, to tell you the truth. And I think about it at this point in time where health, wealth, coincide. And it was back in 2002, and it was right around now, and I happened to be myself. I was told by a doctor that I had weeks and days to get into the hospital because they found a tumor on my kidney that turned positive. Right. It shown positive. So I ended up in Sloan Kettering Hospital in New York City where they removed it. And the type of kidney, the type of cancer that they thought it was, was a Wilms tumor that came on as an adult. And nobody had ever survived this when it came. And you were an adult, but for some reason, mine was negative. But they refused to believe that it was negative. They made me stay in there for 10 days while they kept retesting and retest. But. So I'm totally fine, everybody, because it was negative, even though it showed up as positive. But while I was in there, the word got out that Susie Orman was in the hospital. I was on this floor that people weren't really expected to leave. And one by one, the family members of these people who were in the hospital came into my hospital room and they said, please, Susie, we need your help. We didn't do what we needed to do. We didn't have a will, we didn't have a trust. We don't have emergency money. I don't know what to do. Should I take that? They were so confused about money. And my heart broke for them because at the time when they should be experiencing and mourning the very potential loss of their loved ones, they're sitting there talking to me about money. And. And I never wanted that to happen again for anybody. So it is my honor to be here. Obviously, I've suffered loss. I've had many people in my family and friends die. But the true loss doesn't have to be a relative. For me, it's everyday people, because I'm the one that besides the physical loss, I'm the one that you come to because you, you've had financial loss as well. So I think this is a perfect night for us to come together as one and to know that I know your pain and I also know your financial pain. And I hope, I just hope a little bit that I can alleviate it on both parts.
Oh, so sweet. Thank you so much.
I just know personally, whenever I've talked to you about someone needing a, there must have documents that you created and things like that. And I'm like, oh, and this person's dying, you're like, david, go give it to them. I love that about you.
Yeah.
So I got a lot of questions here. People sent them in. And I'll tell you, one of the things I told you the other day that shocked me is how many scammers, when you start a grief group, how many scammers come on, pretend to be widowers, talk about their wife who died and it's a scam.
Yeah.
And I told people, do not post your finance or questions on Facebook. Send them to me. So I got them here because I didn't want their finances there. There's a number that came in that are all about funds are limited. I'm waiting for my government check. How do I prioritize money right now when it's so scarce?
Yeah. So if you need your government check, if you need that stimulus check and you have no other money, that means you don't have an emergency fund. That means you really are somebody who has to make sure that you count every penny and make every penny count. So what I would do first, if I were you is I would sit down and I would divide my bills up between essential bills and non essential bills. And I would put the non essential bills away. The bills that, hey, if you don't pay them all right, they're not going to turn off your electricity, they're not going to cancel your insurance, they're not going to kick you out of your home. And I would only deal with my essential bills. Then I would pick up the phone or go online and I would take action. Because here's where I just want to veer off for one second. The main internal obstacle to wealth is fear. Because when you are afraid, you are paralyzed. You can barely breathe. So I'm asking you all to keep breathing because you need your breath to give you energy, number one. Number two, the only way for you to conquer fear is through action. So you're looking at these bills, you're Scared to death. You don't know what to do. Breathe, and let's take action. And the action that I want you to take is to pick up the phone or go online. Because right now, lenders and creditors are being most generous in nature. Not all, but many are. And at least make a call. Or where you call in and say, could you please help me? I need three months, I need whatever to postpone, pay my bills. If they say no to you, say okay with grace. Remember that they probably don't have the money to pay their bills either and that the person answering the phone is probably in the same situation as you, financially speaking anyway. Hang up, call back, because you might not get the same person. And you're going to call back and you're going to call back and you're going to call back until you find the person who has the heart to hear you and says, okay, you can have three months. All right? You don't have to pay your car insurance. Oh, your student loan. You can postpone that. That's what you're going to do. Number one, excuse me, number two, if you get this check, what are you and or when you get this check, what are you going to do with it? You are not going to take this check and pay off your credit cards with it. What you're going to do is you are going to postpone your bills. You're going to pay anything you can and charge anything you can on your credit cards, and you are going to pay the minimum payment due on your credit cards and you are going to hold on to any, every penny of that check or any money that you get and you are going to save it. And a lot of you are going to say, but, Susie, I pay 20% interest on my credit cards. Call up the credit card companies and ask them to reduce the payment of the interest as well as possibly to not let you pay your payments anyway. That's what you're going to do. So that's kind of the plan, David, for right now.
You know, I'm surprised at so many people I've talked to who have shame. And I said, you know, this is a time when we're all in this together. You know, I understand that you were raised to take care of yourself and this has to be embarrassing, but we're all in this. And that shame, just like you say, is just like fear. It can paralyze them.
Yeah. The three internal obstacles to wealth. And I've written about this in almost every book that I've written now, all 11 of them. But anyway, is fear, shame, and anger are the three internal obstacles to wealth. And especially. And correct me if I'm wrong here, David, because you. You know, I don't want to venture into an area that I'm not an expert in, but I have found over all the years of dealing with so many thousands of people who have lost a loved one, they are angry. They are angry that they lost a loved one, and they're afraid, and they're ashamed to tell everybody that they're angry and that they're afraid because they have to put on a good face sometimes for the kids or other family members that have lost somebody. And when that happens, you tend to make mistakes. You sell at the wrong time. You buy something to make yourself feel good. Don't let your emotions rule you. It's best to do nothing, financially speaking, other than keeping your money safe and sound for at least six months to one year after suffering the loss of a loved one. And I just really need to tell you all that, because for so many years, when I would sit there and people would show up in my office and I would tell them what to do after suffering the loss of a loved one, a year later, they would come back and say, why did you tell me to do that? I'm like, why did we do that? You're not. You may think you're in your body. You're not. So just keep your money safe and sound right now. You don't have to make big decisions in most cases.
No, you're many, many people are angry. The anger is a very common emotion in grief. A couple things that comes up that I say, I'll check out with you to see if I'm on the right track. One, people will split. Not right now with a pandemic, but otherwise, in grief, people will sometimes splurge and they'll go, you know, I'm in such pain, I'm going to buy myself that Maserati I dreamed of. Yeah.
Yeah.
And of course, they always come back and they go, that didn't help.
Yeah. You know, the biggest act of anger I ever saw was right after September 11th of 2001. I had the great privilege of speaking to many of the wives and spouses of all the firemen that had been lost. And just recently, I spoke to all the spouses of the policemen that were lost as well. And that was just a few months ago, believe it or not, but back then, I'll never forget somebody coming up to me, and she dumped her purse.
Front of me and she said, and there was $800,000 of checks in that purse. She said, this is blood money. I don't want this money. I want my husband back. And I'm looking at this, and she was riddled with anger. And then some of the other spouses, they got some nice settlements. They did. They went out and they bought houses and they did this and they did that, only to really regret doing it afterwards. So, again, the advice here is you are to do nothing other than keep your money safe and sound. Obviously, if you have some money, you can pay off debts, things like that, but you are to not invest it. You are not to listen to anybody who calls, because I can tell you a story about that as well. But you are to keep your money safe and sound for at least six months to one year after suffering the loss of a loved one. Got that, everybody?
Yeah. Good, good, good. And the other thing that comes up a lot of times that I say to people is, if you can, if you don't have to, don't many make any big decisions in that first year because you can't undo them.
So would you. Is there any rule that you would.
Say, yeah, it's to do nothing. It's. It's what I really want people to understand. And maybe this talks about our must have documents as well, David, that I know you use is that I just want you all to know something. And I'll never forget when I realized what. This one person that I knew was a financial advisor. And he would go down to the courthouse, because when you die with just a will, and you have a will, it's a public record because it goes through probate. And he would go down and look at the probate records, and he was able to see every single thing that you were left. He would then find out your name would be right there. He would find out your phone number, and he knew the person who died, and he would call because it was on public record. He would then call the surviving spouse and say, you know, Susie, your spouse and I have been conversing before he or she died. And she, you know, they told me to please call you, and here's a list of everything I know that you were left because you were. He gave this to me or she gave this to me. And so let's talk about what you should do with it. And of course, you trusted that person right away because they knew everything that you had. So really, everybody, you do not want to go through a court procedure known as probate. You don't want to do that. You do not want your assets to be public record. David's telling you he thinks scammers come on to here now and scam you. I'm here to tell you they everywhere.
Everywhere. Yep. And just so you know what we're talking about, I have spent in my life thousands of dollars with attorneys doing wills and living trusts and revocable this and all that. And then I decided Susie and I have the same publisher. I was going to put a lot of some of her stuff on grief.com and I thought, well, if I'm going to put it up there, I should just try it. And it was actually time for me to redo all my stuff. And I thought, I'll just practice on her stuff for when I go to the real attorney. Oh, my gosh. By the time I was done, I was done. I literally saved thousands of dollars by using her must have documents. It's amazing.
And the must have documents, everybody, every one of you must have these. Now, if you've experienced a loss and your loved one didn't have these documents, then you know what I'm talking about here. Because you have to go through probate. It could be six months to two years. It can cost you thousands of dollars. So every one of you should have not only a will, but a living, revocable trust, an advance directive and durable power of attorney for health care, as well as a financial power of attorney. And the less money you have, the. The more you need a living, revocable trust, everybody. So these are documents that you really need. I know you don't want them. I know that you don't want to hear about these things and do these things right now, I will tell you the biggest mistake you will ever make in life is not having these documents in order. Because when you suffer the loss of a loved one, which all of you obviously have, you know what I am telling you is true. You know that you then have to deal with attorneys and do this and do that and not have access to your money. Your minor children can't inherit money. So if you left your minor kids all the money via will, it's going to be locked up until they're 18 in a locked account until somebody petitions the court. Right. It's. And it goes on and on. So I'm just saying this is something you should all think about.
And literally, your program, you can do on your own. You don't have to have anyone. I mean, it's plain language. It's so great. All right, let's do some of these questions. All Right. So let me go through some of.
David, you can't tell them they can do it on their own and not tell them where they can get it because we created a special gift.
I was going to tell them at the end. Don't worry, I wasn't forgetting.
All right, then we can wait till the end till you tell.
You can.
Get it inexpensively because that's who she is. When I told her the regular price, she goes, no, no, no, not for these people.
The regular price on my website is 199. I said, David, don't charge these people 199. Let's sell it to them. Almost. It costs, which is 69. So if you go to susie ormond.comkessler. take a look there. Okay. Go on, boyfriend.
It's shocking. It's shocking what you're going to get. It's shocking. And, and I don't like to sell here, but this is a gift, believe me. All right.
Everyone's from Jane. I'm calling them all Jane.
All right.
Jane says her husband died two months ago today. No life insurance. He had a limited 401. Especially now after the recent drops, we hope to have that at retirement. But we weren't officially married. It looks like I need to start taking it out sooner and remove it all within 10 years. Have a mortgage, a ridiculous student loan that I've paid more than 1,000amonth in for 17 years and have paid well over 150,000. I still owe over 200,000 because of low interest. I'm on an income based repayment plan which they may release me from in five years. I still owe taxes on what's forgiven. We still have children. I would like to keep them at home if possible. I am wondering what you should recommend. Take out all the 401, take installments, pay down the mortgage, student loan, walk away from it all. Bankruptcy options. What do you think?
Oh, so Jane, as you'll all be called, is number one. I'm so, so sorry for your loss. Again, it's only been two months, so I need you to take your time here because this is where mistakes can be made. Listen to me very closely. Just keep paying on the income based repayment plan like you are in five years when they forgive it. I know you're afraid because normally you will owe income tax on that 200,000 or 300,000, whatever amount they will forgive. All right? However, please remember what I'm about to say. When you owe more than what you make, you are technically bankrupt. You are insolvent. So in your case, I doubt highly that you make or have as much in assets as what you will owe in taxes. So therefore it will be dismissed. So don't worry about it. That's your least worry. In terms of the 401k plan, I know that recently we all saw the market go down 38%. Now it's come up almost 30%. We're only down like 4,000 points or so from where we were back in February. However, with that said, I do think that the markets in the next week or two are going to come through some rough times again, maybe extending in a little bit longer. But if it's possible for, for you to keep this money, you now will transfer it into your own name. So it should go in from the custodian who has it now, your spouse's employer. It should now be an IRA rollover. It will be an inherited account in your name. And if you could just sit with it for a while, that would be great. Because I really think if you could not touch it for three, four or five years, you will see it and be happy that you did. Because the question is, what do you do with that money right now when interest rates are so low? However, with that said, if you need money to live on, to pay your mortgage to the reality of life, then okay, withdraw those amounts of money at this point in time and now that the market is relatively high here, I would actually do what you're going to need to spend in the next year. I would not cash it all out, but I would at least cash out what you know you're going to need in the next year. You can take it out monthly if you want. You could take it out all in one lump sum, but know that you will owe ordinary income taxes on it. If you had been married, you could have taken over that 401k plan as if it was your own. In December last year, December 19, actually December 20 of 2019, the Secure act passed which says you can no longer stretch a retirement account over your life expectancy. The maximum amount of time now that you have to withdraw is 10 years. But you could wait 10 years and then withdraw it all in 10 years or little by little. But this is the time that you just have to take day by day, step by step. So don't worry about your student loan. You now know that's okay. Just keep paying the, you know, income based repayment. Take out what you need little by little and make sure that the money that's in the 401k is invested properly for these times, if you can, and just really keep taking day by day. Now, with that said, I also have to say, you have two children. Can they help you? I don't know how old these kids are. David, did she say? Didn't say. But you know, when something like this happens, you all have to work together as a family. And when I was quite young, my father became seriously ill and it was 13 or 14. I had to work every day forever almost. So you're never too young for kids to pitch in and don't try to save them that and do everything for them. No, make them part of this process. Because when they see mommy grieving, and not only grieving emotionally, but grieving financially as well, it's really going to do them in. So all gathered together as a family unit now, what can you each do to help each other? Can you have garage sales? Can you, you know, when it comes to holidays, can you say, kids, I love you, but I'm not going to be buying you things right now. Let's go volunteer our times. Those are the types of things I think that will help.
Beautiful. All right. Jane says, my husband passed away one year ago. How do I determine if I should increase my life insurance and by how much? I have two kids ages 18 and 21. Ah.
So if I had kids who were 18 and 21. Right. You want to make sure that if you have insurance for them that you don't need it for very long. Please listen to me, everybody. Whole life, universal life and variable life insurance insurance in my opinions are total rip offs if you have them. Just hold on for a second. The only insurance, life insurance that I like is term insurance insurance that's good for a specific period of time. Whole life, universal, variable life Insurance is usually 10 times more expensive than term insurance. Insurance was never meant to be there for your whole life. It was only meant to be there for your younger years until you saved enough assets so that if something happened, you would be okay. You obviously are holding insurance now for your kids to be okay. They're 18, 21. I would, if I were you, I would only have at most a 10 year level term insurance policy because once they're at the age of 31, whatever, they should be on their own now. Mommy should not be spending her money to ensure that the kids are going to be okay. The kids should be working to make sure that mommy's going to be okay if mommy's not okay. So we can have a reversal here, everybody, because again, just like I said in the last Question. This needs to be to be a family unit here where you each take care of each other. And I just have to say this. Usually when somebody loses a spouse and it's a woman losing a husband, a father, you tend to feel so guilty, especially if your children are younger, that you spend all of this money on them, on buying them gadgets and doing all these things because of the loss of a loved one. No, all the toys and the iPhones and the things cannot make up for that. What makes up for that is for mommy to be secure, for mommy to have enough money for mommy not to have to be freaked out, for mommy not to fear one day she's going to have to be dependent on her children and to show them what a strong woman or a strong man is. And it isn't about taking care of your kids financially. It's about taking care of them or meeting their needs financially or their wants financially. You always have to meet their needs financially. It's about showing them what it is to say no out of love for yourself versus yes to them out of fear that they're hurting or they won't love you anymore. So especially the women out there, you have to learn how to do that. So I would get that. If you don't have term insurance in place, I would go to select quote.com this is not endorsement from them. They don't know I recommend them, so don't worry about that. And I would get the quotes or five policies which is what they'll give you. And I would get the cheapest one. It will not be that expensive. Okay. And then if you have whole life, universal or variable life insurance, I would cancel it. I would cancel it. Now your agent will probably tell you if you cancel it you're going to have to pay taxes. No you won't. You have paid more in premiums than what you're going to get back. So it's not a taxable event. That then will give you some cash. Either you put that cash in an eight month emergency fund or you put that cash in in your own retirement accounts or if you want you can fund a 529 plan or help them with college. But that's what I would do, David.
And I'll tell you, I couldn't agree more from the grief perspective that I always tell people you are going to have that tendency to over give and try to make up for that loss. And what we need when there's a death is we need everyone to stay the same and be themselves and not try to become Santa Claus and just throw everything at them. We need structure. So I am in agreement. All right, we've got another Jane here. Jane says, what is the best way to protect your assets so your children don't have to pay inheritance tax? And should you put your home in your children's name?
Yeah. First of all, you have to know what the current estate tax limits are. So if you have more than $11.3 million, I believe right now, yeah, they're going to have to pay estate tax. If you have under $11.3 million, I wouldn't worry about it because there is no estate tax on that. Obviously, between spouses, there's no estate tax whatsoever. Just so you know, even if you leave somebody $10 billion. So I wouldn't be worrying right now about estate tax. I just have a feeling that's okay if you have over $11.3 million, then that sometimes when you look into an insurance policy or something to pay estate tax. But I don't have a. I have a feeling that might not be the situation here.
Your question about should you put your home in your children's name? That will be the biggest mistake you have ever made. And why is that? That is because when you put your home in your children's name, so let's just say you even add them onto the title, it's your home. You're living in it. All right? Now, one of those kids gets in a car accident and they kill somebody because their house or seriously injures somebody because their name is on the title of a house. And that's public record. You have lawyers that are going to be able to find out that these kids own a home. And guess what? You could end up losing your home because of that. The best way to do it is to get the kit that David was telling you about where you get a living, revocable trust. It will take you 30 minutes to one hour to do this. That's all it takes.
Shocking. It's shocking.
Follow the instructions on it. You'll fund. You'll. It's so easy, I can't even tell you. But if you were to put the house in the title of the trust held for your benefit while you're alive, your children's benefit after you have died, it immediately passes to them without probate. And there's no public record of it. Everybody. So the very first story I told you about, the financial advisor that would go down to probate court to search the probate records to find your assets that would be listed in there because it wasn't in the will. And trusts are not public record. Wills are. The other thing is if you, let's say, bought the house for $200,000 and it's now worth $800,000 and you gift it to your kids, right now you're also giving it to your cost basis to them of $200,000. You now die and they get this house that they have a cost basis of 200,000. Now it's worth a million. They're going to owe taxes. The difference if they get it through the trust, they get a step up in basis on it to a million dollars. And if they sell it right away, they're not going to owe any taxes on it whatsoever. So do not make the mistake of putting a home in your kid's name or adding them to the title simply to avoid probate. Biggest mistake you will ever make.
I love that you think of all the things we don't. And obviously that's your wisdom and your expertise, but you cover it for us. All right, Jane says another Jane. I'd like to ask susie, I am 66 and a half and my retirement is stock. Should I sell them now since it's my only retirement?
It depends how much money you have in that stock. Stock really and what stock it is. So when she says stock, do you think that she means, David, that she has a diversification or she owns just one stock?
Don't know. I hope it's not one stock.
But let me give you rules of thumb. Everybody with the stock market right now, I think again that if this is money that you need within one year or so, two years even, sometimes three years, that is not money that belongs in the stock market. It never has and it never will. So if you need this money, that is money that should come out of the stock market, I'm sorry to say next, if you don't need this money for 3, 4, 5, 10 years or longer, preferably longer. I do think if you're in good quality stocks, you are diversified, you're in exchange traded funds or mutual funds. I would hold tight here. If you have extra money that you can be investing, I would be dollar cost averaging every month into your stock portfolios. This is not the time to be taking a lump sum of money and putting it all in the market right here. This is the time, little by little, you go in. When the market goes down, your money buys more shares. When it goes up, you buy less shares. But over time, you are averaging the cost of your investments with your dollars. That's what I would be doing.
Okay. All right, here's quite the story. James, husband died by suicide. And I'm going to take out some of this here. Died by suicide due to struggles with bipolar addiction. She was in the hospital with complications of a routine surgery. Let's just say he made a lot of bad decisions in the marriage and she's now permanently disabled. After his death by suicide, he left her with 100,000 in debt. It's now been three and a half years. She sold her house, downsized to a townhouse to pay off the debt in her name. She now has 18,000 in debt. After using all of her resources to pay down the other debt. She's requested mortgage assistance. Because of the pandemic, her expenses have decreased. She's hoping to delay her monthly payment. House payment of 700, the term stated. She can receive assistance for a year. Her question is, am I doing the right thing by using my mortgage to absorb the debt? I don't believe in bankruptcy, but I'm still struggling to stay afloat. My monthly income is 2,100amonth, and I was selling belongings online to help. I have okay, credit. 10,000 is on a home equity loan at 5%, and the rest is on a zero interest credit card till 2021.
Yeah, a lot.
Did she say how old she was again?
She did not.
She didn't. Yeah. So.
You'Re not going to like my advice, Jane, but I'm going to give it to you anyway, is that I know you don't like bankruptcy. Okay, I don't have a problem with that. But when all you have is $2,100 a month of income and all these things have happened to you and you owe money, are you caring more about your credit score at this point in time than your own quality of life it could have been? And I don't want to tell you this because it might upset you a little bit, because I had a case like this from the Oprah Winfrey show where the husband committed suicide and left the wife.
With so much debt, you have no idea. And we were able to get that debt dismissed. So it is possible that you could have gotten that debt dismissed that was in his name. But again, without knowing enough facts about it, who cares? It is what it is. But for those of you who relate or may be in the situation that Jane is in, just know that. That it is possible when a situation like this happens that you don't have to pay the spouse's debt. Got that? So just know that. So, Jane, you owe $18,000 right now.
And if you want, you didn't tell me what the interest rate was on that debt, but I have a feeling it's probably at a high interest rate. So if I were you, I would contact NFCC.org, the National foundation of Consumer Credit, and see if they will work with you to get whatever interest rate that you're paying on that debt at 18% or maybe that's the debt at 0%, I'm not sure. But if you're paying a high interest on any other debt, see if they can get that debt down to 0% and you pay just tiny amounts of money on it. If you can't, then I would just stop paying that. I have to tell you. And if that ruins your credit score, that ruins your credit score because you need every penny right now that you can possibly get. And if all you're getting is $2,100 a month, 700 of that is going to just your mortgage. So you have property taxes, you have utilities. It's leaving you no room here whatsoever. And that really concerns me. Your 5% home equity line of credit right now is a high percentage rate. So it would seem to me that before you maybe ruin your FICO score or credit score, what can you do to get down that 5%? Because right now interest rates are like at 2%, 3%. So could you extend that onto your 0% credit card till 20, 21 rather than paying 5%? The other thing is, can you really afford to be in a home right now? And this was the part that I was going to say, I don't think.
You would like me to say into a townhouse.
A townhouse. But is Jane in a situation right now where she said that she is right. She has some disabilities. So you're in this townhouse. You're obviously a little bit older here, I think. I. Again, I don't know. But are you better off? Just listen to me closely here. Selling the townhouse and moving into either an independent living facility, maybe she's 53. Oh, 53, all right. So, but you know, you could be 53 and have the body really of a 70 year old or 80 year old, I'm sorry to say. So if you don't have somebody to take care of you and you're having this and you're struggling with money, there's obviously equity in the home. Are we better off selling the home, moving into a place that somebody can take care of you, that you, you know, everything is in the monthly rent that you pay There. But you know that they also have assisted living and other types of living, skilled living for as you get older. Just something to think about, David, because it concerns me, especially when women have disabilities, they're by themselves and they have very limited income, you know, so it's just something to think about.
Right?
Yeah.
You know, one thing I want to just ask about that. I see people trying to be in financial integrity. And I think when we think of bankruptcy, we think about, you don't want to be one of those people who is a con artist that's manipulating the system through bankruptcies. That's who we think we might be.
Yeah.
I think people need to realize that's a different situation than something horrific happening in your life and throwing you underwater. Would you agree with that?
What people have to understand is bankruptcy is a legal procedure that's allowed by law. And I will admit that there are many people out there that charged up their credit cards and they went on vacations and they bought these cars and all these clients clothes, and it's like, all right. And most people like that who claim bankruptcy once ends up claiming it twice. Right. But then there are people who have been abused, who have been financially scammed, who have exorbitant medical bills because they didn't have insurance. And there's many reasons why people don't have insurance. People don't have insurance right now. Health insurance and. And on and on. And when you find yourself in a situation like our last. Jane. Jane number three or four, whatever it is, and bankruptcy is a viable option, there should be nothing wrong with it. Don't let your pride get in the way of saying, I need help. Can somebody help me? Because, Jane, you need help right now. You need help. And I'm just grateful that you have $2,100 right now, a month coming in. I don't know if that's from a widow's income. I don't know if you're entitled to Social Security as you get older. I don't know what else there is. Possibly. But when all you have is $2,100 and then money in a house that can be destroyed by the way by hurricanes, tornadoes, floods, mudslides.
Maybe we need to be just a little bit more protected.
And I think townhouse means two stories, if I'm correct, which isn't always the best thing. Limited mobility.
I have a feeling, though, Jane was probably smart enough where it was probably a townhouse this way. And she probably lives on one level.
Gotcha. All right, so this will probably be our Last one. Time flies with you, Susie. This person says that they're alive, but they want to know ahead of time what are the tax and real life consequences and implications of my nephew inheriting a home that's paid in full from an aunt in a revocable trust in California with no contest. Is there a way the aunt with no children can do something before death so that the nephew can inherit the beach cottage without property taxes being assessed? Nephew is low income environmental student graduate with heavy student debt in the time of COVID Yeah.
So here's the thing. Especially because they live in the state of California where probate fees are statutory. Everybody. So the worst state that you want to die in. One of them is if without a trust. California has the best trust laws, but some of the worst probate laws because they're set by statute. So in the state of California, $200,000 home with $180,000 mortgage on it would still be about 15 to $20,000 in statutory probate fees. They are set by law however, because she has a living revocable trust. Smart Jane. The nephew will inherit this house without any probate fees or anything. Number one, again, remember, estates can pass. $11.3 million can be passed right now. So I doubt highly there's going to be any estate tax on this property. And because she's leaving it to him via the trust, he will get a step up in basis on it. So if he then decides to sell it, there will be no income taxes at that point in time. As far as property taxes goes, she can set it up in the trust that the property taxes are to be paid from the trust until he decides what it is that he wants to do with this property. So she can set it up that there's a sum of money to pay for the property taxes for one year or two years or three years. Years. But if he is low income and everything, he probably will end up selling the house. So the question becomes, does she want him to live in the house and take over the house as his own and will he have enough money to do so? Or is she better off having the trustee? Whoever's going to be the trustee over all of this after she dies, sell the house and give him money to do whatever with. And remember, you can dictate in a trust what you want the trustee to do with the money to help a child who may be younger or a nephew or whatever it may be.
Susie, you're amazing. I can tell you the feed has been sending you lots of love. So many Comments of love and everyone's going, can there be a part two? Can we get Susie back? So let me tell you, this is not the only place you can find Susie. Although Susie, you can come back anytime. I want to tell you this is a woman who has so many resources for you. Please know you can go to susie orman audio.com so many, so many resources there.
Let me know. Let me tell them about that, though, David, not that I need to correct you, it's like, listen, everybody, it seems that many of you are a little bit older here. You're 50, 60, or a little bit older. I can say that given I'm going to be 69 next month. So I'm right there with you. However, what I'd like to say is that in February of this year, I wrote a new book. I actually wrote it last year and it's called the ultimate retirement guide for 50 plus winning strategies to make your money last a lifetime. So what I wanted to do today is because so many of you have suffered loss, I wanted to be able to give a gift to all of you that I think would really help you not only right now, but in future years as to what to do with money. And if you go to susie ormanaudio.com it's there that you'll be able to download or actually stream for 30 days, approximately 12 hours and 30 minutes of my book that is a New York Times bestseller. It's now still number two on the New York Times bestseller list after nine weeks. And you'll be able to stream that and listen to things as I'm taking you through it. And there's so many stories in there that aren't in the book and it's also just something that I think you'll enjoy. So it's there. And David, if you don't mind, I can do my own little commercial for myself because really nobody knows more about me than me. But David says, okay, take it away, girlfriend. Where I really want you to go.
Take it away, girlfriend.
You got it, sweetheart. I'd like you to join me every week on my Women and Money podcast. And the Men Smart Enough to listen. That is the official title. So all of you are welcome. Because it's in this podcast that I tell you what you should be doing with money. And and I and it drops every Thursday and Sunday. Also, we have just created the Women and money community and men smart enough to partake as well app. And if you go to Apple Apps or Google Play and you search for Suzy S U z E orman, you can download the app and right there, all free. You'll get all the podcasts and you'll be able to search the podcast by contact by just putting in what you want. And you'll come up with everything as well as you can, ask questions. We have a community. We live stream there. It's fabulous. And very shortly I'm going to have experts for long term care. I'm going to start an investment club with one of the expert women in finance in terms of what to buy, because I want us to all come together as a community and I don't want you to make mistakes with your money. So that's what I've created for all of you. So I hope you partake in that.
All right, Dana, that's amazing. And the last one I want to mention, so important is the Must have Documents. It's literally all the documents you need. The title says it all. It's the Must have documents. And@suziorman.com Kessler K E S S L E R Don't get any money out of that. It's just how we can get it to you easy. And I'll tell you, you know, I often say to people, I can't take away your worst moments when someone dies. I can't. I can't take that pain away. But I can make it a little easy, easier to get through the places you have to go through. And Susie, I think that about you. You know, we all just can't get a million dollars so that we don't have money problems. But you help us in our struggles, you make it easier.
You know, David, if I could just take a few more seconds, I just want all of us to realize what happened here tonight and what was fascinating for me anyway. And by the way, I'd be so honored to come back anytime you want me, David. And to all the people here, in any way I can help you get through your loss a little bit easier. It would be my honor to do so. But have you noticed the similarities between loss of life and loss of money? It's really an amazing thing how these two entities, people and money. And I've always said that money is the currency of life. It's the physical manifestation of who you are. So, David, I find it so fascinating that many of the things that I've told people over all these years about money are the same things that you're telling them about loss and death. So don't you find that fascinating, David?
Well, you know, listen, financial loss, I mean, look, most of, you know, I, you know, with Elizabeth Kubler Ross did the stages I have seen over the years, the stages of the stock market drop, the stages of financial things. It's a loss, is a loss. Obviously, we can get some money back in our life the way we can't get a loved one back. But it's still, people have jumped off buildings because of a loss of money. I mean, it's a huge loss that we often don't talk about. So, Susie, you're just helping the world so much. I love you so much. Such an honor for you to be here.
Thank you. Can I say one more thing about that? One more thing, and then I'll let you go. All right. Which is when people, when you suffer a loss and you inherit money, like you get a stock portfolio from your husband or your mother or your father, you don't want to sell it. You want to hold on thinking that you're holding on to them by holding on to the investments. Please don't do that. Right. Because a good investment five years ago does not make a good investment now. So just know that, that you have them with you. Their investments are not them.
That's their gift to you to take care of yourself in the best way possible. I just wanted to make sure I got that in.
And I tell you, I say that a different way. I say do not make things the evidence that your loved one lived, living, breathing evidence.
Susie, I love you. Thank you so much. I'm going to post the links in the comments. Thank you all for being here. People like Susie are showing up to remind you with COVID 19 and grief and loss. We have not forgotten you. We have not forgotten your loved ones who died. And we are all here to help you. Susie, thank you again. Tomorrow night is Will Reeve, Christopher Reeve's son, who's going to be talking about Superman as a dad who died in Dana Reeves. So I just thank everyone who's showing up for all of you and I will see you tomorrow 1pm I come on every day and then I'll be here with another guest tomorrow night. Thank you so much. Thank you, Susie.
Stay healthy, everybody.
Thanks.
Take care. Bye bye.