EP 38: Tax Saving Strategies from Tax Goddess who saved $1.2 Billion in Taxes
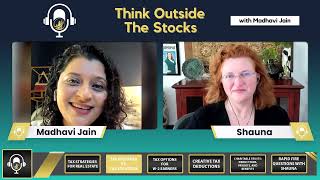
Interview (EP 38) of host Madhavi Nade Jain with Shauna ("Tax Goddess"), a top-ranked tax strategist who says she has saved $1.2 billion in taxes and ranks in the top three U.S. tax strategists. Shauna describes her transition from astrophysics into tax strategy after helping her mother, explains the difference between a tax preparer/CPA and a tax strategist, and outlines tax-reduction approaches for W2 earners (e.g., qualified real estate professional rules, short-term rentals, cost segregation, NUA and structured ownership) and entrepreneurs (wide deduction possibilities subject to "ordinary, necessary, reasonable"). The episode also covers estate/gifting strategies (annual $18,000 gift exclusion, charitable remainder trusts, family limited partnerships, current estate-tax exemption figures and planning urgency), infinite-banking (life insurance) as part of diversification, and practical examples/case stories (pigeons, yacht). Contact: TaxGoddess.com for consultations.
Questions this video answers
$1.2 billion (claimed in interview).
Top three in the country (she says she is in the top 1% and specifically top three).
Spend at least 750 hours on real estate and more than 50% of your working time on real estate (quick qualification mentioned).
$18,000 per person (2024 figure cited in interview).
$13.1 million per person (current-exemption figure referenced).
Chapters
I actually started in astrophysics of all places. Definitely a numbers mind. You know, I was kind of in focus on that front. And very long story short, my mother, my goddess, received an IRS notice one day and she was not very happy about the IRS notice. And she of course was kind of complaining. You know, my cpa, my tax attorney, I keep going for strategies. Nobody can ever seem to get my tax bill down. I, I'm a small business owner. You know, this is, this is breaking my back, right, to pay this level of tax and being, being a good daughter, right. I said, okay, well, you know, I'm kind of smart, maybe I can figure this out. So went and basically fell in love with taxes, started taking classes and so went through the ranks of cpa, master's in tax, certified tax coach, certified tax practitioner, certified tax strategist, and you know, up, up, up, up into the specific specialty of taxation to, as you mentioned, the ranking of the top 1%. I'm in the top three in the country for what I do and they refuse to tell us who's number one. But I've met the other two. So I'm thinking, I don't know, I don't know. But all I know is top three. So, yeah, so it's really always been about, you know, of course, figuring out how I can help solve a problem. You know, taxes are very much like a giant game of chess from that standpoint. You have a specific set of rules and a specific set of pieces. You know, are you married? Single? Dogs, business, real estate, you know, passive investment, what do you have? And looking at how you can apply which rules to which pieces to get to the final outcome, whatever that outcome is for you. So reducing tax or passing on legacy or taking that trip to Paris.
Are you frustrated watching your hard earned money ride the knee jerking Wall street roller coaster? Are you looking to diversify into alternate investments and set them on autopilot to achieve financial freedom? It's time to learn the ways of the wealthy. It's time to Think Outside the Stocks with your host, Madhvi Jain, an immigrant from India and ex IT professional who will bring you industry experts to illustrate a passive and holistic financial approach to build not just passive income, but also your generational wealth. Madvi is on a mission to change the financial trajectory of one family at a time. And a thousand more to go. Are you going to be part of this vision? And now, without further ado, here is the host of Think Outside the Stocks, Madhvi Jain.
Before we go ahead, just a little bit, 2 cents from my lawyer that this is information and education purpose only. If you want to engage with any of our guests, including Shauna, please do your own due diligence. And I am not particularly financial, legal, or tax advisor or investment advisor. So please seek your own team. And maybe Tashana would be one of that team members. Right. And also we, you know, we'll have some examples for education and information purpose only. So keep that in mind. These are point in time. These are not representative of any real information. Hey, hey, hey. Welcome back to Think Outside the Stocks, another episode with your host, Madhvi Jain.
And.
And we have a very interesting guest here today. Well, if tax is on your mind, this guest is going to blow your mind. Absolutely. This is not your typical cpa. This is a tax strategies that we have here who actually is going to take your tax savings and tax strategies to an exponential, exponential level. So, Shauna, welcome to Think of Set. The stocks are delighted to have you here.
Thanks so much. I'm in love with talking about taxes and I'm even more in love with spending time with you, Ms. Madhavi. So I'm very excited to be here. Thanks so much for having us.
Thank you so much, guys. And if you don't know what she's talking about, we actually did kind of a live webinar a couple of weeks back, and if you missed it, oh, my God, you missed a lot. And we are going to.
Don't worry about it.
We are going to give you a chance to go back and watch the recording at your pace. So don't worry about it. So let's just jump into the conversation today. And Shauna, I always love to ask, you know, kind of tell my guest about three interesting facts. So my listeners today, the three interesting facts about Shauna is, number one, she has saved a whooping and, wait for it, $1.2 billion of tax money. Oh, my gosh, Shauna, this is amazing. Amazing. Pete, this is incredible. And I would love to dwell a little bit more into the strategies. But not only that, the second fun fact about Shauna is that she is top 1% tax strategist of the country. I mean, that is incredible. Again, it's not easy to kind of get that. Get there. And the third fact, which is kind of alluding to what she has done, she's very fondly known as tax goddess, of course, Shauna, for a reason. And, you know, as she's focusing on taxes, she actually has this kind of a serial entrepreneurship mind that she not only has different ideas, but she Actually helps people with different ideas too. So we will talk about that again with that small introduction. Shauna, welcome back to Think Outside this talks. And can you elaborate a little bit about your journey so my audience would know that? Where does Shauna journey come from?
Well, I love it. It's kind of a long path, but thank goodness I'm still young. So hopefully many, many, many more years into the future on the path. So, yeah, I actually started in astrophysics, of all places. Definitely a numbers mind. You know, I was kind of in focus on that front. And very long story short, my mother, my goddess, received an IRS notice one day, and she was not very happy about the IRS notice. And she, of course, was kind of complaining. You know, my cpa, my tax attorney, I keep going for strategies. Nobody can ever seem to get my tax bill down. I'm a small business owner. You know, this is. This is breaking my back, right. To pay this level of tax and being. Being a good daughter. Right. I said, okay, well, you know, I'm kind of smart. Maybe I can figure this out. So went and basically fell in love with taxes, started taking classes, and so went through the ranks of cpa, master's in tax, certified tax coach, certified tax practitioner, certified tax strategist, and, you know, up, up, up, up into the space, specialty of taxation to, as you mentioned, the ranking of the top 1%. I'm in the top three in the country for what I do, and they refuse to tell us who's number one, But I've met the other two, so I'm thinking, I don't know, I don't know. But all I know is top three. So. Yeah, so it's really always been about, you know, of course, figuring out how I can help solve a problem. You know, taxes are very much like a giant game of chess from that standpoint. You have a specific, specific set of rules and a specific set of pieces. You know, are you married? Single? Dogs? Business, Real estate, you know, passive investment. What. What do you have? And looking at how you can apply which rules to which pieces to get to the final outcome, whatever that outcome is for you. So reducing tax or passing on legacy or taking that trip to Paris, whatever it is.
So I love that it's a game of chase, always thinking 10 steps ahead. Right. And I love what you shared as well, that, you know, there is a pain point that, you know, with your mother's taxes, it started. I personally believe that whatever, you know, that pains you, you're supposed to solve that in this universe. So I think, you know, for me, that's the investment strategies and you know, me finding out about this out of the box, out of the stocks option and being restless about the tails not available to my community. Right. So that's bringing in that back in. And for you, that's the taxes, you know, whatever you make money that you keep, that's the money can you can grow and it's the growth that you're compounding over period of years. So taxes, that's how I look at it and I love how you do it as well. So let's jump into it. Right. So you know, most of my listeners are going to be the, those, you know, W2 earner, probably husband, wife, working heavy, heavy taxes, the maybe from California, New Jersey and really paying every extra dollar that they're earning.
California almost feels like a stab to the heart. I'm so sorry, my California peeps. I'm so sorry.
Absolutely. So more money they earn, the more goes to, well, Uncle Sam's pocket. So let's try to solve their problem today and take through this conversation and their journey kind of build from there. Right. So tell me, you know what? Typically they have a strategy, they want to create something, they go to their CPAs. So tell me the difference between a CPA and a tax strategist.
Absolutely. Well, I think one of the pieces that many people just don't understand, first of all, they don't even realize that there's a difference at all between their cpa, their tax preparer and the tax strategist. Now I really look at it as there's generally four financial people within your basic level financial license. Okay, so you've got your financial advisor, right? And that person hopefully knows a little bit about insurance. They should know a lot about retirement, these kinds of things, right. They're looking at your overall financial health. You have potentially a bookkeeper somebody or an accounts payable somebody that's helping you pay the bills, track the money that could be you, could be your spouse. All right, you have your tax preparer. So that's the person that takes all of the information at the end of the year, gets it all into the forms, make sure that you're not going to jail. Right? Picking and checking the right boxes, getting everything in the right order, getting those forms filed. And then your tax strategist. The tax strategist job is to bring you strategies that you have never heard of, that you like, that you can implement to reduce your taxes before you hand over your documents to your tax preparer, to your tax cpa. And for Many people, you know, they say, oh well, I mean, I've got a tax preparer and they gave me a strategy. They told me to buy a car last year for my rental properties. Okay, well that's great for last year, but do you really need 10 cars over the next 10 years? Right? Like how many cars in this fleet do you need? Unless of course, you're opening up a turo business. So different passive income idea, but there you go. So, you know, the biggest difference is really the tax preparer focuses on getting the information, placing it properly in the tax return. And we need those people, right, to make sure T's are crossed, I's are dotted, everything's there. Your tax strategist is bringing ideas that you've never heard of to help reduce the taxation overall.
So. Right, I love that. So let's talk about little about those ideas that you have never heard about. So from, you know, I quite typically see people coming to me and saying that, hey, Madhvi, where's your next investment coming in and what's the IRR on that? And how much money I can make when it kind of, you know, completes or exists. Right? But I like to look at it from a different perspective. I always say that, you know, changing the perspective, how you look at things is really, really important, right? For example, if you're a frog in a pond and you look at the problems around you, there are solutions around you as well, right? But you know, if you have like a maybe 100ft view, an eagle sight perspective now, suddenly your problems change and your solutions change too, right? So now you're looking at the entire forest, right? So from that, you know, hundred or thousand feet overview, when we are looking at, I mean, especially the W2 earners and possibly going into that route of creating that little bit of passive income, some businesses, I mean, anything can you give us like that? What is it that they don't know of and what is that strategy should look like from, you know what? I always believe in it. From growing, preserving, protecting and passing their generational wealth. So any like buckets that you can, you know, help us look at?
Lots of buckets, Lots and lots of buckets. And I love the way that you phrase that because it really, when you start to look at tax strategies, we have to kind of start with, well, where, where are you at now? Are you in the accumulation? Are you in the eating, right. Or are you in the passing on to the next generation? Right? Where, where are you at in your life? And plus, what is most important to you okay, for some people that's charity. For some people that's children, you know, passing on to children. For some people it's actually, it is children, but it's not passing on money, it's passing on experience, knowledge. Right? I'm going to slide into the grave with zero, but I'm going to teach you all the lessons so you can go earn your own money, right? So when you look at it from that perspective, how do you know which strategies are right for somebody? Okay, some, some strategies are a one year thing in and done, right? It saves you some money. Some strategies are 5 years, 10 years, 15 years, some are 40, 50, 80, 100. Right? So you really need to know what is it you're trying to accomplish in the end? Now if it's purely passive income, right? So you've worked really hard. You've got a huge, let's say you've got million dollars in W'd in stock in one company, publicly traded stock. You're still a W2 there, but you're maybe thinking about retiring three, four, five years, something along those lines, right? But you're kind of nervous about having such a large nest egg all in one, one stock, right? One employer, you know, ways to get money out of that, right? You could look at using an NUA Net unrealized appreciation strategy, okay, which uses some life insurance, uses some special code sections that, that allows you to only pay tax on the basis of that stock basis, not the current fair market value, but on the basis of that stock when it comes out. And then the rest of it is subject to long term capital gain. That's pretty cool because normally when you pull it out of a 401 or whatever, you're paying all ordinary, all the time. So you could be looking at something like that to get out of that one category concentration. You could be looking at something like a structured ownership program which if you have a big gain, right? So again, you've sold, now you've sold all of this stock, right? So you pulled it out, now you have all the stock and now you're going to sell all that stock. You want to diversify, right? You want to get some of it into insurance, some of it maybe into real estate, some of it into stocks and bonds and ETFs, mutual funds, whatever that is. You could look at a structured ownership program which would split the funds between real estate and forex foreign exchange, right? So with a lot of these strategies, again, it really depends on, well, where, where do you want your money, right? Because real estate can put off some great passive depend. Are you the person managing it? Are you going to get the 2:00am telephone call about the broken toilet? Doesn't feel very passive to me. So you know, I always have to try to think about those things. So the definition of somebody's passive arena, like what. What does passive mean to you? Because we have seen for. Oh, I'm so sorry for, for many people, right. Passive is. Well, I was working 40 hours a week and I'm going to retire for two weeks and now I can't sit still anymore. So I need to do something for 40 hours a week. Should we set up a private foundation for you and your family? Is charity important? Right. Should we put away 30% into the private foundation and you only need to required contribute 5% of the assets to actual charity and you can run a business inside the private foundation from that. So there's a million ways to skin the cat I guess is is kind of the hard bit. And so it just depends on what you're looking for.
So I, I love it and just connecting the dots, right. I mean, you know, I'm passionate about again implementing just couple of strategies, not as many as you have and actually helping people understand kind of education. That's number one and that's I think where we resonate with each other a lot that there's a lot of education involved and then kind of helping them, you know, kind of implement it very structured way. Right. The correct way. Right. The strategic implementation which is really, really important. So you alluded to the insurance portion, the passive real estate portion. And you know, over the period of time I realized these two strategies when one is infinite banking strategy which is a saving strategy using that insurance as kind of a basis but kind of compounding that growth of your money instead of you just keeping it into your banks.
Right.
And then the second is the completely, completely passive syndicated real estate.
Right.
Where you can actually getting the benefits of the income that's coming from the property. The you know, once it exists then you have the growth of equity that's coming back and while you're utilizing it, it's also giving you that tax benefit because now you can take, you know, some portion of it and even though you just applied on your passive income you have some, you know, tax smart kind of dollar coming your way. So I love that is kind of, you know, how everything circles back and you know, what we do together, it kind of helps in a way. So let's talk about, you know, some of the strategies. There are different buckets right there's you know, passive income real estate strategies. But most of our audience is a W2 earner and then for them there's so much limitation on the strategies and even if you're, you know, getting the real estate benefit and you're getting the bonus depreciation, the huge tax benefit, you can't write it off on your W2 income.
So.
And we talked a little bit more in detail, much more detail in that webcast that we did. And guys, if you want to listen to it, you know there is going to be link in the, in the show notes and you can listen and on demand whenever you want to do it. Right? But let's talk a little about what can the W2 earners can do without, you know, just quitting their jobs and big full time real estate.
I was going to say quit your job and become full time in real estate. Yeah, well, and you know, I mean, we laugh, but there, there's always an option, right? One, if you're married, only one of you has to be a real estate professional, right? So that is an option, right. We have seen cases where, you know, the wife is making 500,000 a year, the husband's making 30,000 a year, the husband needs to quit his job and he needs to go be a real estate professional because the amount of write off is way above and beyond whatever amount of earning that the husband could get by being a W2 at that level. So that's always the first serious thing to consider, right? Is does it make financial, fiscal sense and I'll call it emotional psychological sense for one of the two parties to quit whatever their job is and you know, go become a real estate professional.
Now, just a 60 second interruption.
Yeah.
Can you just briefly wrap are ahead around and just for our audience to hear back, what is the qualified real estate professional and what's the quick qualification?
100%. 100%. So the quick air quotes, quick. Anytime you hear quick and IRS understand there's always 50 million more rules. Okay? But the quick qualification is you have to spend at least 750 hours on real estate and you must spend more than 50% of your time on real estate. Okay? So the husband will stick with our example. If the husband was a real estate agent, they would qualify. That's like 100% of their time on real estate, assuming they meet the 750 hours. Okay. However there's, that's the quick and dirty set of rules. There's a whole subsection of rules that's called material participation. So you have to have 750 and more than half and material. Okay. Now once you, if you qualify, if you can meet all those rules and you can qualify as real estate professional, effectively every property you purchase, you're allowed to do, as you mentioned, cost segregation, which would give you an instantaneous big dollar amount write off. Now as we speak right now, of course, this is a political year, right. We will end up with a new president one way or another. There is currently a, I'm going to call it a cap. It's a red percentage of benefit on cost segregation. It's still very strong, but it's reducing by 20% every single year. So depending on what happens with the politics this year, it may go back up to 100% or it may continue on its five year decline here heading towards zero. So fingers crossed. Yeah, fingers crossed. Yeah, fingers crossed. You know, we never know.
100%, it will go back and, you know, apply on the previous list.
Exactly. Talk about amending returns to get some cash back.
Good. Exactly. So let's talk further about, you know, what W2 earners can do. Can you allude to, you know, at least a couple of strategies?
Absolutely.
Apply on them.
Absolutely. Well, if you're in the mood to stay in real estate, because you don't, you don't have to be a real estate professional, you can also go the short term rental route. And this is a part of the reason, at least in, in this goddess's opinion, that Airbnb and VRBO were so popular, because effectively, if you've got a short term rental and you're providing significant services, so if you're picking them up at the airport, if you're giving them a gift basket, if you're taking them out to a ball game, whatever it is, your guests, while they're there, you can actually treat your short term rental property with average rental days of seven or less as a business, which is awesome because that means you can also do cost segregation and get that big write off and you don't have to be a real estate professional. So if you've got husband and wife, both of them are full time W2, but on the weekends they're providing significant services to their guests staying in Airbnb, you're good to go on that front as well. So that's an option if you want to stay in real estate. Now, if you're really, I don't want to do real estate, I don't want to deal with the 2am plumbing calls. I just, I just don't, you know, I want to try something else. That's when typically you start looking at what we call investment alternatives. So now you're looking at, for example, solar, right. Maybe you're going to invest either in a syndicate or directly in solar. You could look at oil and gas, you could look at film credits, you could look at conservation easements. A lot of these types of strategies, good or bad, you have to put money into them to get tax benefits. And so, you know, earlier you mentioned the irr, right, the internal rate of return. You're going to get an amazing rate of return in the first year because you get a tax write off. But if the oil and gas well dries up or you don't pull anything out of the ground, that may be the end of your money. Right. So when we look at investments as far as investing in something to get a tax strategy, I always tend to be a little more conservative on that front. And because they're great and they work. And yes, you can get deductions. I mean, there are some programs, for example leveraged gifting that can give you a 10 to 1. 10 to 1, you put in 100,000, we'll give you $1 million. Okay, but is the IRS happy with it? You got a deep dive and make sure that's a good above board legal strategy. There are some, not all, you know, so, so really when you start to look at investments for reducing the tax, they exist, but you've got to be prepared to lose your money just like any other investment. Be prepared to lose your money other than the money you got back for the tax savings. So really becomes a question of what you want to do and what you want to look at. So.
Yeah, and then, you know, not only that, some of these providers, right. There's so much fraud in this area that it's not about just losing it, that the investment in turnout. Right. It's the, the operator who didn't turn out right. Right. So dis easements and oil and gas, we hear it all the time that there's just, you have to be so, you know, kind of walk on that cautious cycle because it's your hardened money. And I always tell people that, you know, don't go into, for example, a single family rental just based on appreciation that this will appreciate one day without having a cash flow, because cash flow is gonna help you sustain. Just the same way I always say to my investors that don't go into an investment just because it's going to give you tremendous tax benefit. What if that money just gets wiped out? So be very careful and do your due diligence when you're doing that and, you know, be sure that you're connected to people. I'm sure you're also connected with people who suggest some of these things too. Right. As well. But due diligence is really, really important, guys. Right.
Very.
So. So thanks, Shauna, for kind of enlightening us on what the W2 owners can do. And again, guys, this is just the tip of the iceberg. I mean, it's not even the tip of the iceberg. Probably like a minuscule point on the iceberg because there's just so many strategies underneath. Right. So, Shauna, we talked about W2 earners. We also have the listeners, which are entrepreneurs, business owners. And I think this is your favorite topic.
That's my favorite 100%. Well, for the entrepreneurs, you know, the tax code is written for business owners, period. It just is. And I don't, you know, I've had some people try to argue with me on that. I'm like, listen, for W2 folks, you have like, 20 options. For entrepreneurs, you have, like, 2,000. So you can't argue with me that it's not. Yeah. I mean, to the point of. Listen, you want to write off. And I'm not talking about home office here, guys, right? I'm talking about renting your home to your business. Master's exemption, $14,000 a year minimum tax free, right off the bat. Okay? You want to write off your dogs, you want to write off your kids, you want to write off the boat. This morning I had a call with a client, said, hey, I bought a speedboat. I want to figure out how to write this off. Great. We're going to set up a chartering company, and that's the way we're going to do it. Okay? So, you know, with a business, effectively, the sky is the limit. Okay? And the only thing that you have to keep in mind is that whatever the expense, whatever it is you're trying to write off has to meet three qualifications. Okay? So ordinary, necessary, and reasonable. And if you cannot get it to meet those three, you might want to drop it. All right, so one of my personal favorite stories from. Jeez. Now, probably 20 something years ago, this was long before we had, you know, black ops with the Internet and all this kind of stuff. Had a client who did not trust telephones. Like, not. Not telephones, not cell phones, certainly not Internet. These kinds of things. Right. Him and his partner lived in two cities. I think it was about an hour and a half as the crow flies. So literally, birds they trained pigeons to fly between the two locations. Dead serious. Dead serious. And the IRS tried to call us on it saying you're writing off your hobby as a pigeon, you know, as a pigeon person. Right, whatever. And he said, no, this is how we do business is we send pigeons back and forth. And I don't trust the telephones or the government or whatever else. And we won in court because for him, for his business with security concerns that he had, the telephone provider could not prove that nobody else could see their communications. So he won as ordinary, necessary and reasonable to go pigeons. So, right, you know, you got to have a story. Like, you have to understand why, why am I deducting this? This can't just be. Oh, I think the Rolex is pretty. So I'm going to write off the Rolex and I'm going to call it marketing and advertising. You have to be able to prove that it helped your business. It's ordinary, necessary, reasonable. There's tons of court cases, professional dancers, okay, low, risque, but professional dancers getting some enhancements. Okay, absolutely. A tax deduction because they earned more money and therefore paid more tax. So there's a million and one stories here. But if, if you have a W2 and you can even open up any kind of a sidekick here, even just a small sidekick, go drive for Lyft or Uber or literally set up a lemonade stand, go sell something on Etsy, whatever it is. Mentor Cruise is a really big one for my W2 people. Because often, you know, my, my well earning folks, you guys have a skill, right? Your project managers, your CEOs, whatever it is that you're doing, you have a skill other people want to learn from you. Mentor Cruise is an amazing way for you to use your mind and the skills that you have to teach somebody else. So one, making the world a better place. And two, get as a business, you are now a consultant. You are teaching others and getting paid for that. Which means now we have all those fund write offs, houses and cars and kids and boats and dogs and pigeons, if that's what you want. So having a business is the way to go.
Love that. The pigeon story. Very, very, very interesting. Actually, at the end of our show, typically I ask very interesting questions, but it looks like this whole conversation is going to be interesting anyway with you. I can't expect any less, Shauna. But I love that. Ordinary, necessary and reasonable.
Reasonable.
I love that. And you know listeners, I mean, I often talk about what is the necessity of passive income, right. When you are in your W2 and you're like, well I'm really enjoying my job. I'm gonna stay in my job till I retire. Right? So just ask that question to yourself that your, your job is, it's growing, it's creating your wealth. It's not growing it, it's creating your wealth. You need to have something that creates the wealth and then something to grow, preserve, product and pass that wealth, right? And at the same time, each one of you, I kind of challenge each one of you have that purpose and passion in your mind. There's a passion that, you know, probably you want to start a yoga studio, probably you want to go, you know, climb, you know, some one of these difficult destinations, right? So there is a passion and then there's also purpose, right? What is it that you want to impact the world with your imprint? Right? So, and that's exactly what Shauna is talking about. Now you have kind of developed this skill, this massive skill which somebody say, you know, sitting in India and I was talking to somebody about just yesterday, last night in Shana that he started, you know, training for agile in the local language. So somebody who's like sitting in village in India learning about this technology in a local language. Now language, English is not barrier for them, right? So if you have that purpose in your mind that this is what you want to impact, there is no reason that you should stop yourself. Because if you question and that one person is supposed to get that benefit from you, by not doing it, you're actually doing disservice to that person. That's how I like to look at it. Right? So when you're building this business and why not have the advantages of in your favor, kind of turn the cards and start getting those tax advantages, right? That's really, really important perspective. So Shauna, thank you so much for bringing that. So, so share with us that you know, as a business owner and probably RW2 person, like this kind of a character that we are taking through the path, right? They have the W2 owners, what can they create as a, you know, some tax strategies while husband, wife, Both working on W2 like on a part time basis, some kind of entrepreneurship kind of business passion. What are the benefits that they can get from this massive tax code? You know and then you, you talked about, you know, all the write offs that. Yeah, what is the most interesting that you have done so far? They're like, oh my God, I could write off this. They already talked about dogs. That was the most interesting for me. So you cannot talk about dogs.
Oh, okay, yeah. I mean, and I guess this, like, what's the most interesting? I have not yet come across a case where there was something that we could not deduct if it was done properly. Okay. And so what's most interesting really kind of depends on the person. We've written off pools. Like an entire swimming pool. The build of an entire swimming pool. We've written off Rolexes. That. This seems to be the big question from the men. How do I. How do I write off the Rolex? Right. How do I write off the Rolex? Cars, boats, planes, of course, even, even small things. Private school for the kids, which I guess isn't all that small anymore, Right. I mean, at this point, it's $25,000 a year for per child, you know, this kind of thing. Medical care facilities for the parents. Okay, those. Speaking of 25 or $30,000 a month in many cases for the parents. How do we get that as a write off medical expenses? Yeah, dogs, of course. Trying to think, I don't know what was the one that shocked me the most. I always come back to pigeons because of course that, that was just. That was new even for me. Was the pigeons one. Yeah. You know, education, you know, there's. There's many people that, you know, so you have your main job, you have whatever it is that you're doing, okay. But you have a real passion in something. We had somebody who had. There was a real passion in, I'm going to call it Egyptology, right? So the pyramids and reading hieroglyphics and just all of these things. And, you know, he, he kept going to his tax preparers saying, I want to write this off. I'm learning so much. This is education to expand my mind. This kind of thing, coming at it from that angle. It's personal expansion, right? Like, you know, it has nothing to do with his job, right? I think if I remember right, he was like a sales guy or something, right? Nothing to do with the job. And so when he first came to us, he said, yeah, you know, I've been asking my, my CPA for years, how do I write this off, right? It's. I'm spending 10, $15,000 a year on trips to Egypt on, you know, like, I'm really doing a thing. And I said to him, I said, well, have you ever taken tours, like friends and like, taken tours with them and, like, been a tour guide there? Well, yeah, I mean, a couple of times. I'm like, and did they ever pay you for that? Well, I mean, they pitched in for like the hotel and the flights. And I said, listen, if they paid you $100 a day, right, for a seven day trip or whatever, for you to be a tour guide, everything you just spent all of your learning, all of your equipment, your tools, your specialty clothing, everything is now a business deduction.
Wow. Oh.
So it's really more when people say, what's the coolest thing I can write off? What's cool to you, right? Farming. Do you want to raise bees? I don't know, what is it that you want to do? And then look at that and say, okay, how can I use the tax code legally above board. How can I use the tax code to scratch my own itch? How do I make this a deduction?
Bees.
We have a client that did that. She wanted to raise honeybees. She became a bee farmer, teaches lessons on her farm about bees to other people and wrote off her entire orchard. I think it's 60 something trees and her bees and all the equipment and a tractor. I mean to her that's what was important. So yeah, I hope that helps it really.
Of course. Actually homework for you guys who are listening, you know, think about what drives you, what that passion is. And you haven't dwell into being an entrepreneur, being a W2, you know, this is your time to kind of, you know, launches, think about it. But create an LLC and create a, you know, start, start somewhere, right? And there's so much advice by the way that, that, that can help you through this, right? So, so taking this journey, right. So Shauna, we have the W2 owner, business owner. Now let's start talking about creating that kind of a retirement income and more of towards like paying it back to themselves. The strategy around it or maybe even the estate planning, right? Like passing this, some of this generational legacy without this huge burden of taxes. And people you might, you know, you might think that, you know, estate tax, that's not my problem. But look at the history of this country, guys. I mean we have, you know, what, more than 5 million per person currently, but it's going to sunset pretty soon. You know, 2027, January, that is going to change. We don't know what that going to change. And I don't know if you have any idea what that's going to be, but really depending on the administration, you know, politically that can change. You know, in 2007, not too long ago, it was I think 650,000. So what it means like, you know, anything above that is going to apply the Istech tax, tax, taxes, right? So that could be anything beyond 45 to 55%. That's how much your heirs will end up paying. So if you think that that's not your problem. Yes, it is very much going to be a problem depending on when you die, which I don't think we can time after that, right?
Not normally. 10 minutes. 10 minutes.
But you cannot time your time, by the way. I think the best time was to die was. What was it in 2010 or 12 where they had repeated for just one year.
I remember there was one year where it was zero and everybody was like, pull the plug. Let's go, little Mormon.
Yes to the land. So that's. So let's talk about, you know, that like letter year kind of tax strategies consideration and passing it to the astir.
Absolutely. Well, and, you know, one of the. The most underutilized tools is not really even a tax strategy. Okay. Gifting. Basic gifting. Okay. In 2024, the current gift limit is $18,000 per person. Okay. Now you're allowed to gift $18,000 to anyone. Anyone. Okay. It could be to your children, it could be to their children. It could be, if you're still alive, to their children, okay. Nieces, nephews, aunts, uncles, whatever. Okay. If you have. This is where people just kind of. I'm not sure because we don't know exactly what day and minute and hour we're going to pass on. Okay. People like to have a little bit of security, right? I don't know if I'm going to need a little more money, like what's going to happen. Okay. So of course we get the entire life insurance side, which is fantastic because, you know, you will. They will have money to pay for your burial expenses and do whatever they need to do. You'll have money that you can pull out of your life insurance to live on and eat, and you have a very clear schedule of how long that is. Okay? So insurance is fantastic for this kind of side, but the piece of it that people just miss is that if you've got an estate large enough so for this year currently, and you're right, the politics could change this at any moment. Okay? Currently the estate exemption is 13.1 million per person. So if you're married, it's 26.2 million. So if your estate's more than that, you should have been estate planning a while ago. Okay? But they're expensive, expecting it to drop somewhere between 3 to 6 million per person. So, and I mean, I hate to say it, but in today's dollars, $3 million per person is actually not all that much if you're, if you're 65 and you and your spouse. So 3 million each. So you're at 6 million. Total cost of health care is going up. Cost of housing is going up. The insurance companies are jacking up their rates on just housing insurance. I mean everything is coming up. But what did I see the other day? Groceries are now four times as expensive as they were two years ago pre or three years ago pre Covid. So everything is going up. So deciding what you want to do is kind of step one, right? How much do you feel like you need to keep? Okay. And I think, Madhavi, that's where this, the government's going to get. What the government's going to get comes from, right? Is like I need to protect me first. Now there are ways and types, typically types of trusts that you can set up that says when I die, this amount goes to charity, this amount goes to my kids trust, this amount goes to my grandkids. A generation skipping trust. You know, you can do those things on death, but effectively the instant you die, whatever the estate exemption is applies. So if you're above it, or if you think you're going to be above it, planning ahead of time to the best of your ability, start there. Gifting. Great way to do it. $18,000 per person to any person, once a year, every single year. Something else that a lot of people miss out on is gifting percentages of, let's call it a family limited partnership. So if you do have real estate properties and you've amassed quite a portfolio, instead of gifting cash, consider gifting 2% of the portfolio to the heirs. Start getting that out of your name. Okay. If you're into charity, of course, look at charitable remainder trusts. There are some amazing things you can do with that. Where, let's just say you are going to give a gift of $400,000 this year. In 30 years your heirs will get the 400,000 plus the earnings back and the charity got their $400,000 payment. So you're actually double dipping on your same money. Not, not for you, but between the charity and your heirs, some great things you can do there.
Can you elaborate a little bit of it? That, that went too quickly even for me. So let's.
Sorry. Absolutely. The downsides to knowing too much. Thank you for stopping me. I appreciate it. Yeah. So, so let's try, let's run an example. So we're going to do $400,000. Okay. Now normally with any kind of Charitable giving, and it depends on what kind, but for this purpose, and the maximum you're allowed to give is 30% of your adjusted gross income, AGI. Okay, so in this case, we're doing 400,000. That's, that's. So we had 1.2 30%. We're doing a $400,000 gift. Okay. In the first year, my $400,000 gift is now a deduction for my taxes. So I've saved my tax money. I'm happy that $400,000 is going to go into a special kind of trust. And there's about 15 different acronyms. CRAT, CLAT, CLUT, CRUD, CRT. I mean, all these acronyms, they generally start with a C and end with a T. So if you have C, something, something, T, that's typically one of these. Now you put the 400,000 into the trust. The trust has a payout schedule to whichever charity. So let's say you're going to work with the, the Humane Society, okay? Free animals. So over the next 30 years, 40 years, 10 years, whatever it is you set up, you get to pick it. When you make the original donation, whatever that schedule is, the trust pays out every month, every year pays out a chunk of that 400,000 to the charity. But in the meantime, it's sitting on a bunch of money. It's going to invest that money, right? So that money is going to grow and grow and grow. And so if you have a longer time period, like a 30 year or a 40 year, they call it the lockup period. If you have a 30 year, 40 year lockup period by the time that all the payments, because the total amount that has to go to charity is still only 400,000 over 10 years or 40 years or whatever it is, right? So over that time period, the trust has earned a bunch of money. The charity gets paid out, okay? The heirs, when the trust stops at the end of the 40 years, the heirs get the money back. So you got a tax deduction, charity got their 400,000 and your heirs got their money.
Yeah.
And anybody hear the IRS anywhere?
I love that. And the reason, right. I mean, you know, there are, you know, some example is in this country that people have done philanthropy and they think about philanthropy, they passed that where the money, the bucket is, Right? So, yeah, instead of trying to create a bucket, let it grow. And it's kind of, if you want, you can do perpetual strategy because you're basically just taking the cash flow and kind of, you know, generating that for the charity purposes. So you Know, why stop at just that 400 if you want, you know, that growth also kind of go towards a charity or go to your heirs. You have a choice now and it's, it's good always to have, have the choices. So I love that. I absolutely love that strategy. I think estate planning is definitely something that is so powerful that in. Everybody needs to look into it and start taking, you know, taking a note of it. We talk about a lot of, like that, those irrevocable trust and, you know, being a trustee, can you talk about, you know, how that trustee can also get paid while they're managing, you know, the activities of this trust as well?
For sure, yeah. So it, it is allowed to have a payment to the trustee. Typically it has to be written into the document of the trust. So while you're doing your estate planning, make sure that you're looking at, you know, what, what are the terms, what are the conditions, how much can somebody get paid? Often the attorneys will write it in as a reasonable amount, because in today that might be 35,000 a year, but in 20 years from now that might be 100,000, including inflation. Who knows? So often they'll write it in as a reasonable amount. It is a deduction to the trust. It is taxable to whoever receives it. So you do want to kind of be careful about what powers the person has. Can they increase their own salary? You know, often trust documents. We. I think one of the biggest issues that I see with trust and estate planning is these, I'm going to call them the online planning softwares, where, oh, you know, you pay us $500 and we're going to create your trust and make sure you have all the proper paragraphs. Right? Madhavi, that face. No, that's not what's happening. You're getting a cookie cutter. And more often than not, I mean, I hate to say it this, but you've actually caused more problems for your heirs than spending the 2 to $10,000, depending on the complexity of your estate, spending the proper money to get the proper documents up and running and really laid out the way you want them to be laid out. So when it comes to trust, estate and trust planning, 80 different options, 100 different options. There are so many different ways to skin that cat. Do you want to include like an eyelet with life insurance because you have young children? Do you want to have an external trustee that is maybe an attorney? Do you want it to be a family member? Some of the most common clauses that I've seen that I thought were really smart. One of them is if anybody contests this document in any way, they say peep, they're disinherited immediately. Like, no inheritance, you're out. Which prevents family fighting, especially if you have siblings. Right. And the second one that I really liked earlier, you talked about legacy teaching children that, you know, you have to become a productive member of society. You can't just inherit all this money and then loaf around and do nothing. One of them that I really liked was, listen, at 16, you know, you get, I think it was $5,000 to buy a not so good car, but you get a car, but not a. Like Ferrari. Right. You know, you get $5,000 to get a car. At 18, you get a deposit of 20% on a very small condo for wherever you're going to go to College. Right. At 25, you're allowed to take a $50,000 loan to start a business if you want. But it's a loan, you got to pay it with interest. Right. And then once they hit 35, right now you can get distributions from the trust. However, you only get to take out as much as you can prove that you earn. So if you go and get a W2 job and you're earning $45,000, you can get 45,000, but you have to be able to prove how much you earn. And so it prevents children from kind of becoming these trust fund babies. Exactly. So, and we, we talk about infinite.
Banking and a lot of discipline kind of is built in because that's when the money is growing and they can access it using the leverage the loan so that they are responsible about using their own money.
Right.
So I love that. On that note, what are your thoughts on infinite banking? Because, you know, infinite banking is one of that out of the box strategy, which I was actually very, very skeptical, by the way, about it. And I go back to my numbers and spreadsheets when I'm skeptical about things, and I created a ton of scenarios and it's like, oh my God, this thing really works. And I need to educate other people. This is the pain that I want to solve them. Right. So what are your thoughts? I mean, you talk about insurance kind of in infinite banking as well. What are your thoughts? That.
Absolutely. I believe that every portfolio for almost every person should be diversified. So insurance is a part of that diversification. I love it. As you said, you can borrow against it. It's not reachable by creditors. You can create smaller policies, bigger policies, as your family grows, you can add more policies. Right. I do believe that it's a part of an overall diversification. So having some in real estate. Having some in stocks. If you know stocks, if you know real estate. Okay. If you are completely. How do I want to say that some people don't want to know? They just don't. They don't want to follow stocks. They don't want to follow the real estate. Like, they just don't want to know. They want to be able to hand their money to something, somewhere and just have it managed for them. You might be looking at a mix between a professional manager and infinite banking and using that life insurance. Right. Because it's. It's so much more passive. And so really, I guess we end our conversation with where we started it, which is, what. What do you want? How much energy and effort do you want to put into something?
So absolutely. I love that. And that kind of leads to our, you know, next segue, and we can have this conversation with you for hours and hours together, but unfortunately, we have a time limit today.
So.
Yeah, I'm gonna, You know, on the diversification note, I'm gonna ask you a question, which I love to ask, especially experts like you, that, you know, just to give a little bit more perspective to our audience that, you know, how does Shauna, the tax goddess, you know, thinks outside the stocks. How do you diversify your portfolio? Where do you.
What.
What are the all buckets that you does for yourself? And maybe not all significant. And, you know, how does.
How does that work?
How. How do you, Shauna, think outside the stock?
I love it, but you're gonna kill me because I think inside the stock. Personally, I, like, honestly, I don't have.
Anything against the stock, but like you said, it needs to be diversified. It needs to be.
Yes.
All eggs should be on bucket. So. Yeah, go ahead, please.
All good. So, well, how do I want to say that? Okay, so I have businesses. Of course I have. I used to have rental properties, and I got out of it. I was very. I don't want to say lucky, because I kind of. Something was coming. The market crash in 2008. I kept looking at the properties I owned. I'm like, these prices are unreasonable. I'm just gonna. I'm gonna sell them. So I sold everything before it crashed.
Wow.
So kind of go with the. I was good with that. Did my thing in real estate time. You have the perfect item. I'll tell you what. Something just wasn't right. Something wasn't right. You know, now I'm in stocks. I do a lot of options trading, but I am Also very active in, I mean I look at my options twice a day, every day in about four or five portfolios. So I don't tend to suggest options trading to somebody who doesn't have the time to go look at options. Like it'll destroy you if you don't look at it. Right. Same as real estate. If you don't look at the deal, you're going to be in trouble. So of course, life insurance, of course, you know, I think it's a great tool from that standpoint. Yeah, I think those are, I think those are kind of the big, the big, the big chunks, I think.
Love that. Thank you so much for sharing that, Shauna. And you know, by the way, you know, listeners, you heard about a lot of strategies and if you want to dwell deeper into it, we do have that on demand webcast which is going to be linked then almost like a master class. So go and spend the time to listen to it in an hour of a visual, kind of a presentation mode that Shauna, explains a lot of things there. But Shauna, if they want to get in touch with you, you know, how can they get, get in touch and how can they, you know, reach out to you to solve their tax problem?
Well, we would love to, we'd love to solve tax, but it is our favorite thing to do. So we're pretty easy to find. Taxgoddess.com you can book a call with the team, they'll gather data and then we can come back with what kind of options we see for you.
So thank you so much as well. Also in the show notes, Shauna, and with that I'm gonna have end on a very, very peculiar note. I do a kind of a, kind of a fast paced questions called rapid fire. Just three interesting questions like, like a surprise questions and, and you know, three interesting so quick, you know, like 30, 30 seconds, one minute, two minutes, whatever it takes.
Right.
So are you ready for my rapid fire?
I think so. Try me. Let's go.
Yeah, well, one of the question I wanted to ask is one of the most interesting story. You already gave out the pigeon story. But you know what is the. I would say the maximum amount of taxes for a client that you have saved that you remember.
112. 12.6 million. So that was a single deal. Yes, that was a single deal. It was five partners. And yeah, they were happy second there. They, they were very, very happy with that, let's put it that way. So yes. Yeah, I will not forget that number until I beat it. So I met at 112.6 million.
So that leads to my second question. What is the most interesting thing that they have done? Not they, but anybody has done with the money that you send them?
Oh. Oh, you see, that's a tough one. My brain instantly goes to buying a yacht. Had a client that came in and said since he was 5 years old, that was the one thing he's always wanted. And now that he's made it in business, he wanted to buy a million dollar yacht. So we saved him the taxes, bought the yacht, saved even more taxes because we bought the yacht. And there we go. So, yes, very, very good. We bought a yacht.
It's like, you know, absolutely.
It takes money to make money.
Exactly.
It's good stuff.
So the last question is about you, Shauna. Then when Shauna and the tax corners is not saving the money, what do you do?
Oh, okay. Well, you did mention the dogs. There's a reason why dogs always get brought up in my world. I have five dogs and I loved. Yes, I have two German shepherds, two boxer mixes and a Connie Corso Great Danes. So she's big. She's like 135lb tank. And I love gardening. So often we'll just roam around. We'll roam around the garden and eat fruit off the trees and go dig our hands in dirt and play with puppies. It's awesome.
That. Love that. Well, Shauna, such a pleasure to have you. This is such a fun conversation. I had a feeling at the beginning of the meeting that this is just going to flow and it has, it has done that. Such a complex, complex topic. And you know, guys, if you want to get in touch with Shauna, there's going to be information there too. But hopefully you took here some notes and see that there is hope because, you know, as the, the rich dad of the country has said that there's four, four part, you know, you are, you are that, you know, self employed. Then W2, as you start going towards the right hand side, the business owner, that's when really it starts getting there. And as you become the investor now, you can like literally write off much more. Right. I have seen people with like zero dollar tax taxes, even if they made like a million dollar cash flow or income that month, that year. Right. So there's a lot to think about, a lot to dwell upon and lot to kind of rethink and come back to it. Shauna, really, really pleasure. Thank you so much again for being here. I really truly appreciate your knowledge and your zeal to share this education with us. Thank you.
Thank you so much for having me.
Thanks for tuning in to the Think Outside the Stocks podcast. If you enjoyed today's episode, please like and subscribe. MADVI is on a mission to change the financial trajectory of one family at a time. With a thousand more to go, we hope you'll be a part of this vision. Please join our growing community. And to get your journey started, visit thinkoutsidethestocks.com to download your free guide on active income with Passive real estate investments. If you learn something new, please share it with one person today. And if you have 60 seconds, please leave us an Apple review to help us reach more people like you. Tune in for the next episode.
More from Madhavi

The "Holy Grail" Real Estate Strategy Most Passive Investors Miss | Featuring Glenn Hanson

Be fearful when others are greedy, and greedy when others are fearful. #shorts

Building Recession-Proof Wealth Through Mobile Home Parks & Self-Storage with Matt Ricardella

The "Holy Grail" Real Estate Strategy Most Passive Investors Miss | Featuring Glenn Hanson
Think Outside the Stocks: Breaking the Financial Fear Barrier with Liz Faircloth
Why Health Is Your Greatest Financial Investment | Chris Orestis with Madhavi Jain
The #1 Retirement Killer That's NOT the Stock Market (Most People Miss This)
EP47: Private Credit Explained: Stratus Financial’s Impact Investment Model | Brandon Interview