EP 41: Investing in Syndications? Top Red Flags in Underwriting with Jason Williams
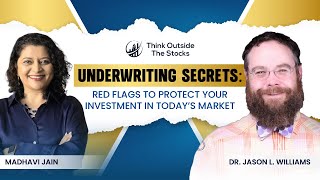
Jason Williams breaks down red flags in multifamily syndication underwriting that passive investors miss. Watch for lack of third-party verification, unrealistic renovation timelines, weak operator teams, and insufficient stress testing. His Ironclad Underwriting Mastery program teaches you to spot these problems before you invest.
Chapters
Every, I teach all my students this. Like, you have to get third party verification on all of your input. You can't just blindly say, all right, I'm going to increase rents $150 per unit and, and we're going to do some rehab. And we're already what, 300 per unit below market. So if we increase it to that and then we start increasing it 150 a year, it's like, yeah, that looks good on paper, but it's not feasible. You want to have third party verification on every single number you put in. And that, that's one of the big, big red flags is, is you're trusting but you're not verifying. And so it's like if you have a property manager who's going to be running the property, you want them to give you a budget and you want them to tell you what they think they can increase those rents to be.
Are you frustrated watching your hard earned money ride the knee jerking Wall street roller coaster? Are you looking to diversify into alternate investments and set them on autopilot to achieve financial freedom? It's time to learn the ways of the wealthy. It's time to Think Outside the Stocks with your host, Madhvi Jain, an immigrant from India and ex IT professional who will bring you industry experts to illustrate a passive and holistic financial approach to, to build not just passive income, but also your generational wealth. Madvi is on a mission to change the financial trajectory of one family at a time. And a thousand more to go. Are you going to be part of this vision? And now, without further ado, here is the host of Think Outside the Stocks, Madhvi Jain.
Hey, hey, hey. Welcome back to Think Outside the Stocks. I'm your host, Madhvi Jain and we have a very interesting guest with us today, Jason William. And Jason, you are here with my most favorite topic and that is underwriting. So we will talk about a lot about numbers in today's episode. So you know, roll your shoulders, get your pens and pencils out, you're gonna take notes today. I'm very excited about this episode. Before we go ahead, I do want to mention that this is information and education purpose only. Whatever we are providing as an education on this podcast, please be sure to do your own due diligence on it. Consult your tax professionals, your law, so that you can implement this strategy in your financial structure. Jason, welcome to Think Outside the Stocks.
Thank you.
Absolutely. So Jason, before we go ahead, I always like to talk about three fun fact about our guest and you actually have many interesting facts. The first interesting fact is, hey, we have a doctor in the house. We have our PhD. I mean, Jason has done PhD from Texas Tech University in chemical engineering. That's very interesting. Jason with, you know, 20 plus years in real estate and his, you know, the Ph.D. now he's kind of creating this massive education about underwriting, and he applies all these techniques to his underwriting. And he has. That's his second fun fact that he actually has an, like a mastery course in underwriting. So that's really close to his heart. And the third fun fact, Jason, I would love to share is that you are proud father of three girls and a boy who actually has special needs. And we will talk about about it in today's episode and how, you know, sometimes when life gives you challenges and we kind of taper it and create some completely different journey out of it, and, you know, we'd love to talk about that and what has it done to you and how it has motivated to kind of change a little bit of path of yours. So with that, you know, Jason of ironcard Underwriting Mastery Program and many other Lauren Capital, as well as, you know, one of the conferences that I spoken at Academy presents, you know, you have a lot of hats that you wear, and we would love to explore in all into it. We are so humbled by you being here. Thank you so much for being on the show and welcome back again.
Thank you for having me.
Thank you, Jason. So with that, you know, let's. Let's jump into a little bit about your journey into real estate and chemical engineering, to real estate. Do you want to allude to a little bit of that path and, you know, just a background about how did you get here?
Yeah, so my wife, angel and I both sort of grew up with real estate. Our families did it, so it was always something we just assumed we would do. And since she. She came from that background, I came from that background. It was like, never a discussion of, all right, well, let's try to get into real estate and make money. It's like, we have already. We're gonna do that. And my dad always mentions to get into real estate, find a business that makes your money, and then you can do whatever you want as a career for fun or whatever. Now, granted, it does take a while to get up to that point. So I, I picked the career one, because it's challenging, two, because at the time I thought I'd make a whole lot of money doing it. And so that was chemical engineering. And I was like, yeah, I'm going to be a chemical engineer, make a lot of money and then I'll get into real estate after that. Well then 2001, September 911 happened. I graduated in May of 02. So I couldn't find a job because nobody was hiring. So then I went to grad school thinking, all right, I'll go to grad school, I need even more money as an Engineer, earn my PhD, got out and then realized, yeah, I'm not making as much money as I was hoping to be making. So, so definitely we got into real estate when we started it, when I was in my graduate career. So we bought our first house, we lived in it and then we started renting it out when I got my first job. And then we cash out, refi, we started rolling it over into some other single family homes, cash out, refi those. But it was a long process. It took maybe like five years to get any equity out so we could buy a new one. Then I learned about multifamily syndication and haven't even looked back since. And when I realized I could buy properties with other people's money, then like the doors were open, my eyes were open. It's like now I can do what I want. And, and so I have been in 2022, I was laid off from my position, my company moved to Houston. I was hired on as a consultant for the company. But what it let me do is concentrate more on the real estate aspect. And I haven't had to find a new job in over two years because I've been doing my real estate thing. So that's more or less my journey in a quick nutshell.
Nice, nice. Thank you for sharing that. I know, you know, market cycles we have seen at different times and I have seen 2008, especially with the real estate impact, job impact, it just kind of makes these twists and turns but we end up taking a path that otherwise we wouldn't have taken. So I think, you know, you and me, you know, we are grateful for what has happened, otherwise we wouldn't have been here doing what we do. And not just that we have found the path, but we are passionate about educating others. And that's what I like about you. When you have created this, you know, entire system for yourself and now you're looking at it and, and trying to educate and trying to have the right fit forward for your investors. I really love that. So let's talk about how did you get to the, the ironclad underwriting.
So, so when I got into the multifamily aspect. I started. I was learning underwriting. I didn't know anything about it. I have a mentor who started leading me in the right direction. My wife, angel, goes to a lot of meetups, and so she was getting a lot of resources for me. I was helping people with their underwriting, but really I was learning more about it as I was helping them, as always, kind of like one or two steps ahead of them. So I was able to help them, but I didn't know everything yet. I still don't know everything, but I. I'm still working on it. And so I was getting all these different models from different programs. I was creating my own model because I didn't find anything that I really liked. And so I started creating my own. And then we use. I mean, that's what we use today. We use it to buy all our properties. We put all our information through my models and to determine. I know some coaches, they'll share you a model with you that they don't even use. They just have one that they send you, but they don't use it themselves. We actually use our model ourselves. But it was in BEC of 2023. People, like, came up to me in droves, like, hey, can you teach me how to underwrite? Or, hey, can you sell me your model? Because the one I'm using just not working. And then from that conference is what really spawned my under ironclad underwriting master programs. Like, I never thought I would teach underwriting. I never thought I would be able to sell a model. I was like, this is what I created on my own, and people found value in it. And so that's. That's what kicked that off.
Love that. Love that, Jason. And congratulations on taking that path because it's not only helping you, but it's helping many, many others. Because getting the underwriting right, the finances right, is the first step forward when it comes to multifamily. And there, you know, so many coaching programs, and like you rightfully said so that there is a model in that coaching program. But the question is, then, when they are underwriting their hundreds of, you know, properties, are they using that model? And that's, you know, pointed out so correctly that if they're not using it, why are they proposing it? Right? So I love the differentiator that you have. So let's talk about. I mean, you know, our audience today is passive investors. These are people who do not have so much time. I mean, underwriting, as you and me understand it, it could be really a giant task. I Mean, you know, underwriting a property could take hours, but understanding that the model itself could also take many, many hours. Right. To get really expertise on that. And we have our listeners who are, you know, tech savvy, medical professionals or you know, other really active, you know, W2 earners or business people as well. They do not have time for that. So let about first of all, you know, what is underwriting and why should they actually should consider spending couple of hours because now there's, you know, they're putting their hard earned money, hundreds of dollars, hundreds of thousands of dollars into, into syndications, multifamily or otherwise. Right. So let's talk about what is underwriting and what are the things that they should keep in mind? Why should, why should they keep the underwriting in mind? Why is that the top 1 priority?
So underwriting is more or less just running the numbers on a property to see if it's going to make money or not or how do you change up your business plan so that you can make money with a certain property? I've helped many operators, people who are buying the properties, but I've also helped many passive investors as well. They're probably with passive investors, sometimes they may get underwriting from the group they're going to be investing with, sometimes they won't. You almost always get a pitch deck. So I, I show or I help people go through a pitch deck what to look for. If you don't have the underwriting, you can start seeing if things are making sense. Yeah, I've gone through many pitch decks before and the numbers just aren't adding up from like your second slide where you're, you're doing this versus the 40, the slide that has all the financials and stuff. It's like, well, these two slides aren't jiving so what's going on? And so I, I help people look for those little nuances that yeah, the pitch deck looks perfect and it's amazing. But for some reason the numbers don't add up. And so as an investor you want to make sure those numbers add up. And the details, the devil's always in the details. Like how the group does one thing is how they're going to do everything. If they're overlooking the smallest details, which are easy to fix in a pitch deck, what details are they going to overlook? Whenever they are running and operating a property, will they just say hand wave and hope somebody else takes care of it or will they, will they take care of it themselves? So these are a lot of things you can actually Pull from a pitch deck without even going into the numbers yet. So love that I've helped a lot of passive investors in that regard.
Yeah, love that, Jason. You know, it's kind of completing that story. I quite often get a request from my friends, my family and you know, something probably like off Crowdstreet or other platforms that, hey, this is a deal in Austin. And you know, I'm in Austin, right. So, hey, this is really in Austin. And what do you think? You know, it's, it has great, you know, numbers, annualized returns, 20% or 25%. And I always say that, you know, don't fall for the shiny numbers and what you're talking about, knowing the real story behind the numbers. Real story behind whether things are adding up from the, you know, second slide of the page tag to the 40th slide of the page deck. And that kind of tells that complete story. And that's, you know, behind the curtain. The look a little bit passive investors when they're putting, you know, 50,000 is typically the minimum. So that's a lot of hard earned money that they're putting into. So take that couple of hours, do a little bit research, do a little bit of analysis. What is the most important aspect that you do? I mean, you know, we think outside the stocks. Our focus is capital preservation. Right. We are trying to understand and analyze that risk. It's very difficult to kind of quantify that, the risk. Right, but that's what you are trying to do. You're kind of, you know, doing the risk profiling to see how it impacts your investment strategy. So let's talk about the risk and how, how do you relate the underwriting with the risk and the capital preservation kind of completing that circle.
So outside of underwriting, I think the biggest aspect is the team you're investing with. I've invested with a team. Underwriting looked good. All the numbers added up and made sense and it was 100% doable. But whenever it came time to, to execute the operation, the team didn't raise all the money they were planning on raising. So they were. So they were doing all their cap or. Yeah, they're doing all their cap X from the cash flow of the property. So the investors didn't see anything. But the construction firm got every little bit and it was vertically integrated. So they were doing their own construction. They're paying through it with the cash flow and then they ended up selling it. And I think over 18, 20 months or so, I think I ended up getting like 1200 bucks or something like that as, as the investment was supposed to be a 2x equity multiple in like three years. And I got, at least I got my capital back, but I mean, I would have rather invested that in something else. And so even if the numbers do look good and can work, you still are betting on the jockey, not the horse.
So that's true.
So that, that is probably the biggest risk I think there. And if you have a good solid team or you trust the team, then that's when you start diving into the numbers.
So yeah, yeah, very, very well said. You know, bet on the jockey. You know, we, we talk about that and think outside the stocks as well. Is the operator, you know, an operator with their experience, if they have seen different micro cycles, right, they know how to handle the challenges because in every environment there's going to be different challenge. If they're equipped to handle the challenge and kind of, you know, change their strategies, that's what is going to impact. You know, a good operator can get, make a, you know, a good deal and make it like really good, but a bad operator can take a good deal but, you know, you don't know, you can kill it. Right. So let's talk about our favorite topic here. Underwriting. Now, you know, for passive investors, really, without getting it more complicated, keeping it at, you know, enough depth level, what can we tell them today? You know, if we are to identify that, hey, let's look at this as red flags. And when you see these deals and if you don't see in your pitch deck these questions, these answer questions answered, then go and probe those questions from the operator. So at least, you know, at least if you and me together can save them from stepping on one landmine together. Let's try to do that. You know, so let's try to identify those red flags and whether it's 5, 7, 10, whatever we can cover today, let's try to jump into that. So tell us about, you know, few red flags that passive investors should keep in mind to, you know, just stop stepping on those landmines.
So every, I teach all my students this, like you have to get third party verification on all of your inputs. You can't just blindly say, all right, I'm going to increase rents $150 per unit and we're going to do some rehab and we're already what, 300 per unit below market. So if we increase it to that and then we start increasing at 150 a year, it's like, yeah, that looks good on paper, but it's not feasible. You want to have third party verification on every single number you put in. And that, that's one of the big, big red flags is, is you're trusting but you're not verifying. And so it's like if you have a property manager who's going to be running the property, you want them to give you a budget and you want them to tell you what they think they can increase those rents to be. You can't just do some hand waving and assume it's like, well, this property down the street is doing this. And it's like, no, this is specific to this property. That property down the street might be a class A or a B plus. And you're sitting here at a C minus. You can't do the same. Same thing. So that, that is, that is probably one of the biggest ones is getting verification on all the numbers. And that is very easy to put in your pitch deck. Say, hey, this is what our, our third party verification people said. This is what we should be able to attain. It's reasonable. So if they don't put that in the pitch deck, then they either don't know or hiding something or they probably just don't know they should put it in because they don't know what they don't know. So.
Got it. Got it. I love that. Trust but verify. And if they have done that third party verification, I think that's important to highlight in there. That's number one. Let's go to the next one.
So another one that I've seen not so much recently, but sort of during the time when interest rates were climbing, people were using temporary trends for the long game. So before interest rates were climbing, San Antonio was booming. They were getting 30% year over year increases in rents.
Outrageous. Yeah.
I helped people with their underwriting and they put that into their model that they were planning on doing 25 to 30% increases year over year. It's like that might work for a year, two years, but that's not going to work for the long game. And, and it's obvious is now they're having to decrease rents because people are moving out of San Antonio into other markets. So Austin's same way. Phoenix, they're, they've been on the decline. They might be on the up now, but like whenever those interest rates were climbing, they were dropping. And that's why places were getting foreclosed on left and right because of, of all that. They were hoping to get the rents and then, well, interest rates were a whole other aspect. But that's one big Thing that I've seen. Why would you do that?
Absolutely. Absolutely. And let's talk about it a little bit and how important it is because you strike a really important point here, right. The temporary trends, right. I mean sometimes what would think outside the stocks? I mean I'm looking at and you know, I kind of bring these investments in my fund model to my investors, right. And when I'm looking at and vetting this, operators who are already by the way, are under contract, they have done their underwriting and I'm vetting them to see whether I should be bringing in front of my investors. Right. So I'm looking at their underwriting and when I say that, you know, I just want to see the numbers and I want to see the conservative underwriting. Right. And sometimes I go back and say that, hey, your rent growth projection, it's not conservative, Right. I want to see something which is in alignment with inflation at least. Right. So it's, you know, zero percent first year is what my comfort is. And maybe 3%, you know, maybe 4% year. Three, four. But 3% starting, you know, second year. That's kind of the conservative numbers I'm looking at. And. And why really? Right. Because they will come back and say that, oh, it is conservative because COSTAR is, you know, projecting whatever 12% in this area and we did 8%. So it's conservative than CoStar. But that's again, exactly said it's based on temporary trends. You know, we had inflation and I quite often see the rent growth and inflation kind of going hand in hand. Right. Inflation. Couple of years back we saw that it was just outrageous. And that's why, you know, we saw the rent growth was. And as you pointed out, you know, markets like Phoenix, Austin, we are seeing a negative, it's a rent decline and it's going into negative territories while it's going to go and adjust. Right. And those kind of numbers, when you go from 4% to 8% and that's just like a 4% jump, but the IRR can significantly jump, right. That can take you from like 12% to even like 20%. And then that's exactly what we are talking about. The 20% is a shiny numbers going behind the curtain and kind of unwelling a little bit and seeing that is it even doable for them? Right. Are they going to achieve it? So that's a very, very important aspect. Thanks for pointing that out. Let's talk about the next one.
So this one may or may not apply to limited partners or passive investors. I know a lot of LPs or passive investors are in like mentorship programs and they get in it so that they can get the deals. They're not looking to be operators. But one thing is that they're arbitrarily following that guru. They don't know. It's like, this is what he says, so this is what you should be doing. It's like, well, this sort of goes back to the trusting and verifying, but in regards to who you are listening to and who you're putting stock into, I've known people who. And, and again, a few years ago, you can pretty much invest in anything and make money, and now you can't. I mean, people are losing deals. So it's like you have to be. It's like, it's, it's really testing the strength of the operator now just because of the times. And so if you're just listening to a guru, you listen to him a few years ago, when everybody's making money, he's like, yeah, this guy is doing great. But now, now your guru is doing capital calls, he's doing getting foreclosed on. He's now become an ostracized and not becoming a guru anymore. And it's like, so you followed him because he was doing great things back then, but now it's not so arbitrarily. Following a guru is one red flag that I've seen. And again, it just goes back to trusting and verifying.
And so, yeah, yep, very important aspect, Jason. And let's talk a little bit about it, right? What you mentioned, that's really true. You know, the. There is a lot of coaching program that got kind of induced into the market last seven, eight, nine years or so. And a lot of them actually just wrote this, you know, the cap rate wave that we call it. And they didn't have to do anything. You know, they didn't have to do anything because the direction cap rate was growing. Even if you just sit on the property, even if you don't do any value adds and you sell it after two or three years, you would still get significant. You could 2x your investor capital easily, right? And if that became their track record and they did like thousands of units and they're like, okay, now I can do thousands of units. So let me create a coaching program based on what I know and let me teach other people. And now there are, you know, hundreds of people plunged into this coaching programs and following the same things. And one of the riskiest thing. Right. I've seen that, you know, if the, the guru did not know how to manage the interest rate climbing up. And you know, the, the rate caps especially and the, you know, the, the students didn't know how to manage that either. And then suddenly there are a bunch of people who have got into this, you know, thousands of units of properties without a rate cap or without sufficient rate cap, even if they had the rate cap. And certainly these are the properties who are at risk. You know, people have, they have turned their keys to their lenders, they have lost investor capitals, they have done significant amount of capital calls, dilution for passive investors. And this is, you know, go to my heart because this is their heart and money losing. And that's what I keep talking about. If they can stop stepping on one single landmine if because of this, this podcast, right? That's, that's totally worth it. So, so that's really important. I think you highlight that, that very well. And this is why I like to look at, going back to our discussion about betting on the jockey. What have they seen? What have different cycles that you have, they have gone through. Like look at you. You have seen 20 years of real estate and you know, with your families also probably even a little bit more that growing up seeing the real estate. But when you see the, the cycle, the cycle is going to throw you different set of challenges. Not a, not a single challenge is going to come back and say that okay, this is the same challenges that, I mean there are some challenges which are same, but there is going to be new challenge. And that's why it's really important for the team to be able to equip with handling those challenges. So thank you for sharing that. Tell us about the next red flag that they should watch out about.
One thing that I, I'm a big proponent of is looking at like monthly cash flow or monthly numbers generally with, with a pitch deck, you might just get the annual numbers and that's fine. But you want to make sure that the operating team is looking at the monthly numbers. And the reason, reason why this is important, especially with like a big value add play, is when you're going in and you're buying a property that's 70% occupied and you're going to do some renovations and flip it around and bring it up to a different, bring it up from like a B minus to a B plus or A, you're going to be putting in a lot of rehab and you're going to be facing a lot of vacancies or any or something a lot of outlay of cash and so what I show my students, and I have models that show this is like, for year one, it says, yeah, you're going to be net positive. You're going to bring in $18,000 in cash flow year one. But what it doesn't show you is for the first six months, you're going to be going down 24,000 coming out of pocket. Because when you have to make your insurance and your, your taxes and you have to make your debt service, so all of that stuff is still accumulating, you're going to be negative until you can start getting those units occupied at the higher rates that you think you're going to be getting. And so, like, for the first six, six months, you're going to be negative 24. And then for the second six months, it's going to start doing a hockey stick. So at the end of the year, you're going to be up 18,000 or whatever. But you don't know that. Yeah, you don't know that. If you're only looking at the annual numbers, like, oh, 18,000, that's about 8, 1500amonth. I can do that. And then it's going to grow from there. It's like, so now you need to know if, if you're going to be doing capital calls on day one, or if you're, if you raise enough reserves to cover that downpour or whatever, or the low spot. So you need to put that into your business plan. And that, that is one thing I harp on is like, what is it going to look like from the month? Or even if it had a refi or something, you do a refi, you give all your money, your, your money back to your investors. But now all of a sudden, your debt service doubled because you got it at a higher, higher principal, so now you can't cover it. So then that helps you know how much capital you need to keep before you give it all back to your investors. And so that, that's just another aspect that I've seen.
I, I love this point, Jason. And you kind of, you know, hit the hell in one nail in, you know, one of the biggest challenges that I used to have because, because you. Nice to see. Look at this underwriting. And by the way, I love this. I love this conversation. It's just like, feels like we're bouncing off, you know, each other's challenges and kind of pointing our investors to a right direction. So one of the challenges that I was, you know, talking about when you started talking about, you know, the cash flow and how you're renovating, right, Is that I would look at underwriting and they would say that, okay, these are the number of units that's going to be renovated. Right. And there is no schedule for the renovation. Right. That's the biggest challenge because either they cannot assume that at the end of one year all the units are renovated and everything is, you know, hunky dory and everything is kind of up and running. And you know, with that, whatever occupancy that they projected, that's going to get start get there at the end of the year. But the challenge that I was having is just kind of putting it that, okay, in a month, month, you can only bring so many units up. Right. You cannot empty out entire apartment complex, renovate everything and then start putting people in there. Right. So looks like from what you're talking is your underwriting model kind of takes a look at that systematically. That, okay, this is kind of the schedule. I said, you know, these are your number of units it could be up in for six months and then that's going to impact this much of vacancy. And then, you know, gradually getting to that, that, you know, 18 to 24 month cycle where all the units are up. But on a gradual level. We're not expecting. Because underwriting could be challenging if you're, if you don't understand and as an operator, you're using that model with somebody else some guru created and you plugged in those numbers and it's just assuming that everything is going to be up at the end of one year or.
18 months or whatever to even prove that point. I've seen and I've helped numerous people, they are assuming it from day one. Everything's going to be renovated and they can get.
I wanted to be nice and not say no day one, Jason, I have.
Seen that so many times and it's like, do you know what you're doing? And that actually goes into another of my red flags that may not, may not pertain to limited partners, but I mean, it would at least let them look at it. It's like, yeah, yeah, people just blindly put numbers into a model and not really know what they do.
And so, and these are operators, these are, you know, what you're betting your money on this jockey and their operations and they, they don't know they're having this challenge. And there's going to be cash flow problem in the first year because obviously it's not going to be up at that rate after the renovation. And this is, I mean, I, we kind of, you know, started Modifying our templates to kind of put that schedule in. So we knew what we, you know, what's that impact going be. But if you're listening, I mean, this is really important. This is why you need somebody who understands it. And Jason, quite honestly, I like my position because I feel like I'm a bridge between, you know, the operators and operators. Sometimes they're great operators, they know what they're doing. And that's why, you know, person like me can read through this, you know, poorly underwritten or well underwritten, you know, investments and day and night difference. Right. And that can bring to the investors because the investors don't have time or expertise to look at it to do that. Due diligence. Right. And by the way, we also use like a third party underwriting company. Even if I understand very well, we use third party underwriting to kind of re verify, provide all the T12 and you know, provide all the rentals and stuff and kind of re verify. Because underwriting is the prime, most important aspect of any deal, of course, after the operators. So. So thank you for sharing that.
But underwriting is like so many people that I, I deal with, they just like, just gloss over it or they do some hand waving and they don't treat it like it should be treated. And that, that baffles me too. He's like, well, I'll worry about this later or, or I have the underwriter on my team. He knows what he's doing. You assume he knows what he's doing. You don't know really. I mean, but I mean that I have. And, and I do help with underwriting. I have underwriting consultant and consultation and people come to me already under contract and they're like, does this deal make money? Because I don't know, I'm already under contract and we're supposed to close in two weeks. I'm like, you should have brought this before you even submitted an loi. But I'll. Let's see what we can do to at least turn your business plan around so you can figure out how to make money on this thing.
Absolutely. So love that. Let's talk about one or two point more and then we'd love to talk about your. The ironclad mastery program and what it entails. So let's talk about a couple of red flags for our investors.
Okay. Another one is not stress testing. It's like or, or not stress testing enough. So. And what you can do is you go in and say, well, what happens if Occupancy drops to 70% Are you going to be in dire straits or can you make it? I know Break Even says it's going to be 84, but how long can it drop down to 70 before you do a capital call? Stuff like that. So that, that would be one aspect. Or what if it's like, well, what if the cap rates are growing that exorbitant rates and, and you're going to be getting out, you're hoping to get out at five and a quarter and it's looking like it's going to be seven and a half. What does that do? And so that, that would be another thing at least. So you can have numbers, say, all right, this is where we're hoping to be and shooting for, but we might end up in here. So, so there's just some other things you can stress test for how long you hold it. It's like, whoa, what if we hold it for 36 months or 72 months or 84 or what if we sell it at month 65, what is it going to look like? Because most people, they sort of round it to the nearest year. It's like, well, let's do it at 48 or 60 or whatever. But no, you can, you can hold it for longer or shorter than a year and then get rid of it. So, so those are some other aspects.
Yes. Stress test is, is so important. Thanks for pointing that out. I mean, there are so many aspects, right? The, the market rent, the, you know, like you said, the, the cap rate, you know, the, the occupancies, if you're refinancing, the interest rates, you know, there's.
So many stress tests that when you refinance, you refinance in month 24 or 27 or 36.
Exactly.
All those can affect your numbers as well. And that can also affect your cash flow for a few months as well. So.
And that 2x or, you know, whenever they're seeing that 18, 17 annualized returns and 2x in five years, every single aspect, by the way, listeners, we are talking about every single aspect, even individually, even if, like, you know, the four or five we talked about four didn't materialize and one materializes of any of them, it's going to impact those numbers directly. So it's the validity. Why are we doing this? Underwriting re verification on a property which is already under contract is because we want to make sure that the numbers that they are saying they're planning on, the projection that they're seeing, how viable is it for them to reach that, that numbers and Jason, to Just to give a glimpse around our process is what we do is we take an underwriting and we really, really stop at it. Right. And all these different aspects of it, you know, what's the rent growth, what's the, you know, other conservative underwriting assumptions that they have, the insurances, the property taxes, the stress test. And we kind of take, take, you know, certain parameters, 5, 7, 10, whatever the parameters, and like push, push, push, make it super conservative. And then we take our underwriting model, not their model, a completely different underwriting model, plug those numbers in and see now once the IR is IRR is going to be right. So if they're projecting 17% and we push, push, push, and becomes like 12%, 13%, which is still looking good because not everything is going to occur, but some things are going to occur and then, you know, it will land somewhere in between. So I like that if it goes to like 3%, 4%, and sometimes it does, sometimes it goes even negative, that's definitely a deal that we don't want to go into. Because they have considered, I mean, I've seen deals, Jason, that they're just looking at property taxes, that they're going to reduce the property taxes, they're going to challenge it. And that's how there's just, you know, the whole strategy, the like or at least 70, 80% of the strategies coming up from just that operational, you know, efficiency of property taxes. And it baffles me. Right, so that's.
Well, I mean, if you're in a, in a state like Texas, which is non disclosure state, where you don't have to tell them how much you bought a property for. No, let's say you bought a property for $10 million and it was being taxed at 3 million. It's like, you're not going to go and say, hey, I bought this at 10 million. Can you tax me at 10 million? It's like, no. Yeah, but what, what happens is the county CEO, this changed hands, so it must have probably sold at this amount and they can get access to a loan document or something. They'll say, oh, well, you assume you bought it at, at 7 million, so we're going to increase your taxes to 6.
Yeah, yeah.
Okay. And so now it's like, well, you can't do that because I bought it at 10. It's like, okay, we'll change it to 10. It's like, no. So you have to find someone to protest that. But if they lose, I mean, your taxes doubled, it went from 3 to 6 million and there's really nothing you can do about it. And that happens all the time. So you have to be able to say, all right, well what happens whenever the tax value goes up to 6 million where this is what it's going to be and can we cover it it. So I mean there's, there's a lot in Texas and other nondisclosure states that you have to take into account and, and most of the time you don't know what you don't know. So it's like, well we'll hire somebody to take care of it and bring it back down to three. Like maybe they'll bring it down to five and a half, who knows?
Yeah, yeah, no, that's, that's an excellent point. I mean, you know, again, one assumption can change the entire outlook of it. Right. So, so let's talk about your here a little bit. You know, is it something that even passive investors can reach out for and can get a help from you? How, how does it work?
So I have online course. I can do either face to face like this through Zoom Call every week for about an hour, hour and a half. We have, it's about a 12 to 16 week curriculum depending on the speed at which you pick stuff up and how quickly or not quickly you understand stuff. I've had one student take 20 plus weeks. I've had another student take like exactly 12. So I mean it just depends on, on how you keep up with with it. I mean it's a course so I mean you're gonna expect it to do some on your end. Also do an online where you can do it at yourself pace where or you can watch like different modules and stuff and work through exercises. So I do it that as well. And then I have office hours for all my students once a week, 10, 10 o' clock on Thursday and, and at least at the time of this being recorded it might change later, I don't know.
Sure.
But at least an hour a week of office hours where you can come ask questions, work. We work through live deals, we go through pitch decks. I have some videos on on YouTube of us going through pitch decks. So this would be good for your passive investors to see. What do you look for in a pitch deck to make sure it's at least worthy of going on and finding out more information or just washing your hands clean of it. So and I also have a community in LinkedIn or LinkedIn group where anyone can join ask questions about underwriting and that that's another thing is a lot of people, they don't know what they don't know and they don't know where to go to find information. Yeah, there, there might be some YouTube videos, there might be some books, but I mean those just basically cover the rudimentary stuff, all the textbook stuff, not actually what's happening. And so if you have a place where you can go and ask questions and that's, that's what I provide as well.
So thank you. Thank you so much, Jason. And you know, I'll, I'll take the information and I'm going to put it in the show notes. But where can they go on the website to, to look for the program?
So, so I, I can be found on LinkedIn. I also have ironcladunderwriting.com where I have some sample videos you can watch. You can. And I'm working on making some quick resources for, for you to download and stuff. I'm still working on that. I haven't gotten those out yet, but hopefully I will by the time this is aired. And so you can, yeah, you can go there, you can down download stuff, you can schedule a time to meet with me on, on via Zoom, or you can go to our community where my wife has all her stuff, where we have all of her summits and stuff stuff. It's all in the same community. Just because it's easier that way for us.
Yeah, I love what you and angel have been doing, you know, providing this content and value to, to audience for years now with your summits as well. So thank you for sharing that. So with that, we're going to move to our next segment. And this is the segment, you know, we think outside the stocks or podcasts, it's not just about multifamily, it's just not about syndication. But I focus on, you know, growing, preserving, protecting and passing your generational wealth because, you know, we got to start doing that somewhere and some point, right. And I would love to go back to your unique kind of situation, a unique story, right? You being a parent of three girls and a boy and you alluded to it that you puts you in a very, you know, peculiar position. So we would love to know for you, what strategy do you apply to diversify? I mean, you, you're not heavily probably into stock market anyway. You're probably heavy in real estate. So how do you diversify in, you know, different buckets and how do you make sure kind of, you know, creating that vault and kind of, you know, planning, you know, after you, that how your next generation is going to get hold of all these Things and still keep it intact and not just, you know, kind of, you know, they're protected enough. So can you share that, that with us?
So my grandparents created a partnership with generation skipping trusts. So it like skipped over my dad and I'm the beneficiary of it. My dad was a trustee. And so we have this template and it's been going on for like 30, 40 years of what it's been doing. So it obviously works. And so we are using that to try and help build our legacy, help create or create wealth for, for my daughters. My son, he special needs, he can't hold anything under his name or else he loses all his services. So we have to plan around that so we have a special needs trust for him. And ultimately what we want to do is we want to remove the financial burden of my son for my daughters when, when angel and I are gone, we don't want them to have to figure out how do we pay for his services if, I mean, how do we pay for his services? I mean, I can get a job and, and hopefully have enough to cover it. Or we are, angel and I are putting this in place so that they don't have to.
I did.
Now, now granted, we are using a special need trust so he doesn't lose services from the state, but he's, he's still expensive above and beyond what the state will pay for. And so that, that's where this comes into play. And then whenever he passes on and assuming my daughters are still alive, then they would sort of absorb all of that special needs trust into them so that they can provide for their family, their kids, they can put their kids through college or whatever. So that our goal right now.
Wow. Wow. Very complex and very thought.
And the thing is, is we don't do it all on our own. I can't imagine trying to figure it all out. So we do have advisors that we work with. They, they, they have legal on their team, they have accountants on their team. So they have everybody all on the same page because it's always hard trying to find a lawyer, an accountant who will work together. So they have all of this in place. We've also worked with a coach on how to navigate the whole state system, how to get on all the lists and, and how much to charge them for rent and food and clothing and all of this, that and the other. Because I mean there, there are so many nuances you don't even know about. And, and if you don't know, then you'll never know even to think about it.
So you don't know what, like you said, when you don't know what you don't know know.
So that's why we hire all these, these advisors and coaches to help us navigate all this because love that, I mean, I, I, I'm in my wheelhouse, I'm out doing great systems for numbers and angels in her wheelhouse with creating relationships. And so we outsource other people. And that's, that's one of the big things also is we preach the who, not how process. It's like, you know, that can help you versus how do I get this done amongst juggling everything else.
So yeah, and it's, it's not about, you know, that, that value and worth proportion because sometimes people go into like analysis paralysis. It's like, hey, if I want to create an estate plan, where is the cheapest source that I can find? Or, you know, what's the easiest way I'm gonna get done? No, you got to go to the experts. You got to go to the things you that they have done hundreds and thousands of times and seen all kind of situations. And us is not in unique situations. They must have seen that with somebody somewhere. Right? And that's when you be an expert in what you do and let them be expert in what they do. That's a very good point that you bring in. Thank you for sharing that. So with that, we have kind of come to our final round. Jason, this was a really great conversation and again, you know, thanks for adding those tidbits. It's really important when it comes to underwriting and everything that you shared today, so valuable. I hope our listeners took the notes down and, you know, have at least some points to ask and check back if they can. But with that, the last round is actually my most favorite round. It's called rapid fire round and it's nothing to do with real estate, but more of the personal stories. But sometimes, you know, there's like a cross or questions too. So are you ready for the rapid fire round?
Sure I am.
I see it down there, Jason. No, it's just going to be some fun little questions and you know, 30 seconds, one minute answers, short answers or whatever you want it to be. Right. So yeah, my first question actually going to be about real estate. That what is the most outrageous, you know, when somebody gave you the underwriting, what's most outrageous assumptions that you have seen that just hugely impacted and kind of made the day and night difference, that they actually didn't go for that deal or didn't Go for that, that investment.
So it was actually one, they were already under contract and they just wanted me to double check the numbers. And what I found is one, they were increasing rents as if they were renovated on day one, like I mentioned earlier. But the way they put it into the model, they didn't know the model very well. And it ended up. They were triple dipping on that rent increase.
Oh, my gosh.
Yeah, but they were already under contract. It's like, do you still have your outs to get out from it? Because, I mean, these numbers don't make sense.
How much money do you have at risk?
I know, it's, it's is scary. And what it comes from these big mentorship groups that you find on Instagram or something, and they put over like work over 20, $40,000 or even more sometimes, and they're just being led astray. And that's, that's scary to me. And I've helped a lot of people in that regard. They spend a lot of money expecting a lot for their return for it, and they're not seeing it. And, and a lot of times they're getting, getting misinformation on how to go about it. And, and that's, that's.
Wow.
Yeah, that, that opens up a whole other can of worms.
That can of worms. I know, it's. It's huge. Thanks for sharing that. My second question is going to be. And this is about, you know, you and me have a couple common thread. It's about mindset, right? And our common thread is Coachti. Coachti has been on my podcast too. Incredible. Incredible to have him. So, you know, there's something with the coaching that inherently shifts, right? There is like a mindset shift that happens and suddenly you are standing at that fork and you just pick another path and there's a lot of growth just by shifting that mindset. It. That, that 2mm shift, right? What is that mindset shift, if you remember and go back and kind of tell us about, has been for you, what is the biggest moment, biggest learning over the period of years that you have that shifted your mindset so significantly that year? You know, it's a completely different daylight for you.
So this is, this goes back to, to my wife also. When Anson was born, we kind of knew something was wrong. He got diagnosed with loop 15q. It's a duplication of the 15th chromosome, similar to down syndrome. Down syndrome is a duplication of the 21st chromosome. So he's autistic. He. He still wears diapers. He's 14 years old. So I mean, he's, he can't help himself. The back where when he was still a baby, angel was sort of freaking out, crying. It's like, what are we supposed to do? Why was he given to us? And, and, and, and I flipped it around on her. It's like, well, what if it wasn't he who was given to us, but what if we were given to him?
Wow. Goosebumps. I'm getting goosebumps.
So now we have to advocate for him because we're his gift. He's not necessarily punishing us. No, we're helping him. And so with that sort of creates a paradigm shift. And now anytime something bad happens, I kind of try to twist it around and say, well, and you've heard this. It's not life happening to me, it's happening for me. And so what can we do to, to change how we look at things? Because it's gonna, he's our son. No matter what, we're gonna love him. There's no return to cinder. So now we, we have to make the best of the situation. And so that's, that's how we do it.
I love that. And you guys have done incredible. And your mindset and, you know, your attitude towards everything has been tremendous. I give it, give it to you for that. But amazing, amazing. You know, sometimes we are looking at a glass from the inside and we feel stuck and there's, you know, a lot of going on because it's just stuck. But if you look at the same glass from the outside, it's suddenly the perspective completely changes. It's just so open and it's just, you know, whole wide world out there, you know, focusing on what challenges you have instead of that, what blessings you have. Right. It's, it's, it's big words, but it really, when you're going through something, something like this, a mind shift, shift changes. I hope.
Yeah, you have to consciously do it because, I mean, when you get into your habits or you fall back onto what you normally do, it's easy to, to get into that mindset where you're only looking at the glass from one direction. So you have to make a conscious effort to twist it. But the more you make that consciousness, conscious effort to look at it, a different perspective, the easier it gets. And, and then eventually you're going to be looking at the glass from all different angles before you even make an assessment of where you are so that you know where, where to go from where you are. So.
Absolutely, absolutely. Thank you so much sharing that. And the last question, Any last thoughts for our passive investors? I mean it's quite scary out there, there, you know, there's a lot of investments going wrong, there's lot of capital cost going on, there's political pressure, there's so much and people are like, am I supposed to hold on to my money? Am I supposed to invest into something? I would just, you know, what's going on. The stock market is doing what it's supposed to do, the real estate is doing, you know, again, going through the cycles. Any last thoughts that you know, you could share with the investors?
What I would say is do your research and don't be afraid to invest. Yeah, it's like times are kind of rough right now and we have the election coming up and we don't know what's going to happen. But if you're anything like me and you have money sitting in a bank account, you're eventually going to spend it away. It's like, oh, I can do this, I got such and such money in my account account. But if you take that out and you invest it into something, whether it's the stocks or it's a, it's a syndication or it's oil and gas or something, just do your research that you're, what you're investing in and then you understand what the risks are and then it's not gonna be so bad. Yeah, you might lose money initially, but if it's a long term play then you're gonna make it back later on. So yeah, and it goes back back. Do research on your operators, try to find out who also invests with whoever you're working with or planning on working with and see what kind of returns they're getting, what kind of returns are getting now that interest rates have, have gone through the roof compared to four years ago. I mean, I mean they're literally what, 2, 1 2% now they're 6%. So I mean that tripled your interest rate, that, that tripled your debt service potentially. So I mean it could you see what kind of trials and tribulations those operators have been through and how they came out at the end. And so you just need to do your research. And people always say, well, what do you think is the riskiest investment? And to me that is investing in something I know nothing about. So if you do your research on your own operators, you do research on oil and gas, you do research on your stocks that you're wanting to invest in you, you can mitigate a lot of those risks. If you just put $10,000 in the stock market and hope it's going to do something. Yeah, that, that's the most risky investment I can think of.
Or absolutely golden.
Yeah.
Golden. Golden nuggets, Jason. I mean, you can't sit on it. The inflation will kill it, you know, if you put it in stock market, market, question yourself how much do you understand of that stock market or the investment vehicle that you're going into. Right. Golden nuggets. Thank you so much for sharing. It has been incredible conversation. So, so grateful to have you on our show. Thank you so much again. And listeners, thank you. Absolutely. And listeners, thank you to you too for listening another episode and with every episode we try to bring in more depth, more content. And today's with incredible guests. It has been one incredible conversation. Thank you for listening.
Thanks for tuning in to the Think Outside the Stocks podcast. If you enjoyed today's episode, please like and subscribe. MADVI is on a mission to change the financial trajectory of one family at a time. With a thousand more to go, we hope you'll be a part of this vision. Please join our growing community and to get your journey journey started, visit thinkoutsidethestocks.com to download your free guide on active income with passive real estate investments. If you learn something new, please share it with one person today. And if you have 60 seconds, please leave us an Apple review to help us reach more people like you. Tune in for the next episode.
More from Madhavi

The "Holy Grail" Real Estate Strategy Most Passive Investors Miss | Featuring Glenn Hanson

Be fearful when others are greedy, and greedy when others are fearful. #shorts

Building Recession-Proof Wealth Through Mobile Home Parks & Self-Storage with Matt Ricardella

The "Holy Grail" Real Estate Strategy Most Passive Investors Miss | Featuring Glenn Hanson
Think Outside the Stocks: Breaking the Financial Fear Barrier with Liz Faircloth
Why Health Is Your Greatest Financial Investment | Chris Orestis with Madhavi Jain
The #1 Retirement Killer That's NOT the Stock Market (Most People Miss This)
EP47: Private Credit Explained: Stratus Financial’s Impact Investment Model | Brandon Interview