Texas and Florida Multifamily Outlook with JT Capital
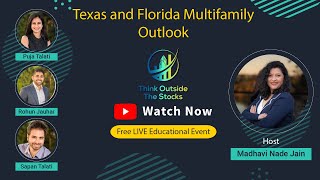
Webinar (May 8, 2021) hosted by Madhavind Jain with JT Capital (Pooja Talati, Rohan Jahar, Sapan Talati) reviewing multifamily investment opportunities and outlooks in Florida (Central Florida: Orlando, Jacksonville, Space Coast, select north Miami submarkets) and Texas (Austin, DFW). JT Capital describes a value-add strategy focused on 100–500 unit properties with below-market rents: interior renovations, deferred maintenance remediation, and institutional property management to lift rents and asset value. The talk covers market metrics (migration, occupancy, cap compression), sample deal economics and investor structures (preferred returns, equity splits), COVID-era performance, and typical hold period (3–5 years).
Questions this video answers
May 8, 2021
About 1,800 new residents per week
Class C ≈ 97% occupied; Class B and A ≈ 96.5% occupied
Approximately 40 basis points cap-rate compression over 120 days
Typically 3–5 years
Chapters
Here then while you check on him. So again welcome, welcome both of you and welcome Sapan as well all of you. I'm just gonna share my screen quickly so thank you everyone for joining in. This is our bi weekly series with think outside the stocks. In this educational webinars I tried to discuss different topics and bring in different guests who can throw some light on their expertise based on their expertise on different topics. So today we're going to talk about Texas and Florida multifamily overview. We're going to talk about a little bit about these markets, why these markets are important and our guests today, JD Capital are very much focused in this market when they purchase their multifamily units. So I'm very curious to find out why you guys focus in this markets. And of course there'll be soon some upcoming opportunities to invest in these markets too but would love to get their perspective on it. I stay in Austin and quite often people ask me about Austin market and how, you know how the investments or deals here are. It's really hard to find the investments here and these days even the real estate at the single families is going through a bidding war. So it's getting more and more tough to make these numbers work. But if you have good connections, if you have that right attitude, you could find some investments in here. So that's what JD Capital team is going to talk about in some time. Before we go ahead, just a little bit disclaimer from our side. This is an information purpose only so just an educational webinar. We are not providing any investment opportunities today. If we do have investment opportunities in future that will be offered through our Investor Inner Circle program which is free to join by the way. And if you are, you know, if you want to do some investments, please perform your own due diligence, consult Your own attorneys, CPAs, etc, your team essentially. So please do that. And also note that there are going to be some numbers, some examples today and this is just for information and presentation purpose only. This could be based on last deals but every deal is different. I hope everyone understands that but just would like to say that so in in terms of general market conditions, economic conditions, these numbers could significantly change. So please, please please understand that. About Me I'm your host Madhavind Jain. Most of you know me by now. For those new faces, welcome, welcome to this journey, this educational journey. I'm the president, I think outside the stocks and also wealth strategies with Paradigm Life I focus on commercial real estate focused education and investments where I education this and more Other investment education as well. And also I bring thoroughly vetted investments to the investors so they can participate in them. I also help investors to understand Infinity banking system to make their savings efficient. So if you want to know about it, just get in touch with me. In my past life I like to say that I worked in Deloitte Consulting for quite a long time and Pooja here actually did work with Deloitte as well in her past life. So that's another thing we have in common. I work mostly in project management and I actually am very glad to use that experience into my journey with think outside the stocks. So apart from all the portfolio I have and active as well as passive, the really true passion for me is the education. I love, love to share the information that I have discovered, share it with the passive investors so they can utilize and implement in their journey. We have our guest today here, Pooja Talati. As I was just talking about a little bit here about her, she has experience about 190 million-plus. She's looking at overseeing these assets in real estate and she is really, her expertise is in marketing, in strategic growth, planning, innovations and operations. She has been a former brand manager at one of the really good companies, Hershey's I wish I would I could be there. And she actually marketed and managed the iconic brands such as Hershey's Kisses. I hope you got a lot of chocolates by the way. Pooja.
Chocolate and candy.
Yeah, that's awesome. So in her prior career in marketing she was a management consultant of course in Deloitte Consulting. Talked about that and where she worked in different industries and different service areas including the merger, strategic planning for Fortune 500 banks. She's also an undergraduate from Carnegie Mellon and MBA from Duke University. So she brings all this experience and all this education to JT Capital. Rohan Jahar, another, you know, one of the strong members of JT Capital, he has 10 years of experience in investing, real estate, finance and operations. He led consulting where he advised hedge funds, investment banks and the future of the tech industry. Also worked into tech companies in setting up their operational, financial and remote work process. He actually earlier in his career he worked as a strategy and finance at Facebook, as a venture capitalist in Silicon Valley. So he brings that experience in. He started his career at GE where he rose through the ranks, through the leadership program, working across the world in every GE business line. So that's incredible. Rohan, by the way, outside of the real estate, he continues to be an advisor in hedge funds, tech companies and high growth startups. So incredible, incredible Experience that he brings to JT Capital. Sapantilati, Pooja and Sapan, they are brothers and sisters so that's you know that's really great. The powerhouse of the siblings here. He also has 10 plus years of real estate experience and multitude of senior and executive level of asset management, acquisition and disposition business development strategy experience. He has about 350 million-plus in portfolio in acquisitions and his experience comes from management consulting in strategy where he championed two international brands valued over 1 billion in US. He also led post merger strategy planning with top five US bank by asset executed 50 million plus in equity into commercial development projects in India. So Sapan is also fun fact is also a guest lecturer at UCSD's Reddy School of Business on strategy and innovation. By the way, Sapanda, no, that was one of the school my daughter was accepted this year. She's recently accepted admission at Kelley. But he also has a undergraduate degree in finance from Villanueva University and MBA from Reddish School of Business. That's ucsd. That's your school. So welcome everyone. Again. Do you want to just say a couple of sentence before I go ahead?
Yeah, we're excited to be here. So Mavi, thanks for you know, letting us be guests. Tonight's webinar. We will just walk you through some of the markets that we're really excited about and then you'll also get to see you know, a sample of how we look at deals, how we analyze it, what we do and kind of step by step lay out that process for you.
That's perfect. Thank you so much Pooja. So before we jump ahead, just a couple of minutes about Think outside the Stocks. What I like about bringing a different perspective to my investors with Think outside the Stocks. The focus is just not laterally looking at saving, saving, saving and investing, investing, investing. But I really like the bird's eye perspective to wealth maximization of course. So that's how I help my clients with growing, preserving, protecting and passing generational wealth. So we think outside the stocks. I help investors in a twofold approach. The first fold is that making the savings really efficient because it's pretty much becoming stagnant and lazy with guaranteed growth and protection, the tax free growth with infinity banking system. And the second fold is that risk managed syndicated real estate investments in various asset classes and on top of it, the education kind of sits on top of it which is I'm really passionate about. We have an upcoming very webinar. It's a three part series also this is a three part series of sample deal review which is the last event in that series today. And we will talk about saving the capital gains in the next series where we will talk about the 1031 exchange, we'll talk about opportunity zones, and we'll also talk about the DSDs. So with that, we are going to talk about Texas and Florida multifamily overview. And it's very important. Just a couple of minutes about today's session. Right. As a passive investor, when you look at different markets, when you see these markets growing, it's really essential to know that as syndicators, what are those different criteria that they're looking at when they're going in this market? Because the market, I mean, if Austin is blooming, it's not just important that you go in the market in Austin, but there are sub markets that you really need to focus on. There are different parameters which indicates that this growth which has been coming in is also sustainable in future. So those are one of few of the important criteria about the market to understand, as well as when the deal hits the door. You don't get too much of time because a lot of people are getting to know about syndication deals. So sometimes when the investment comes in, it gets oversubscribed pretty fast. And at that time, if you are afraid of swimming into the water, this is your time to review that sample deal. Look at their processes, look at what they do, look at how they create their business plan, how they execute and execute that plan and provide that due diligence so that you can feel the confidence about going ahead and investing in these investments. This is that before you jump into the cold water and start swimming, this is just getting your feet wet. So with that, I would love to give it back to you guys. I know one of you is gonna, you know, share the screen, so please go ahead. I think you all have the access to share the screen.
Okay, perfect. And I think Stephan, you might just have to make him host real quick so he can share his video.
Yeah, let me quickly do that. Okay, seven. I have met you host, so please go ahead and share your video. Perfect. Hey, welcome. And if I missed out anything in your introduction, please introduce a little bit about yourself. You know, just going around, I would love to have that. I think.
I think you did a really great job.
Thank you.
And then if you want to make me host, I will. Or actually I can share the screen. Right. So I'll just go ahead and present here. Okay. All right. So Stepan is going to kick it off and start off with our Florida market.
Sure. Thanks, Pooja. So Florida, as everybody knows, has been a hotspot with real estate, tourism, just net migration as a whole. And then we had the pandemic, which put a little bit of a damper on the tourism sector. However, real estate really hasn't taken a backseat at all. In fact, we've seen significant growth in the real estate market. And so what I'll be referring to mostly will be specific to Central Florida markets. So that's inclusive of Orlando, Tampa, as we go out east towards the eastern seaboard like Melbourne, and then upwards towards Jacksonville as well. And these are markets that we look at real estate, specifically multifamily apartments, and then selectively in certain pockets north of Miami. So not Miami specific, but northern Miami. The information that I'll talk about is really based off of our experience there, off of the research that we're actively and currently will be involving ourselves within, and then also just based off of our portfolio and current experience there from that. Some of the things we've seen as just transitions coming out of the pandemic is that cap rates have been compressing significantly a lot quicker than we've probably seen historically. An example I'd give is in Jacksonville. The last 120 days we've seen about 40 basis points cap compression. That type of cap movement is generally unheard of historically, but that just kind of gives you some idea of just the market exuberance that we're seeing there. Just earlier today we saw a report that Jacksonville is also supposed to be the number one destination for remote workers. And so we've seen the number of remote workers in the United States through the pandemic actually double just in quantity. And now Jacksonville being the number one destination for that work from home location just kind of bodes to the type of demand we're seeing from an investor standpoint, but also from a rental standpoint. If we're looking down towards Orlando, we're seeing significant occupancy. So we're at Class C is about 97% occupied, which means it's kind of spilling at the brim. Class B and a are about 96 and a half percent occupied. And so same thing, there's just no inventory. We've got 1800 new residents moving into Orlando every week. And then you got single family homes at a 15 year low. So there's a little less than a month's worth of inventory there. So same thing, there's just no inventory. I want to move to Orlando. Where am I going? And so through these environmental factors or economics, we're seeing increases in Rent year to date, we're about 4.4% higher in rent, whereas during the meat of the pandemic we saw lease trade out. So we're actually experiencing negative rent growth of about 1%. And so it's been quite a different change. And then we're expecting that growth rate to continue this year and into next year. And then keep in mind none of this is specific to the tourism area. So like when people think of Orlando, they think of, you know, we call it the Mickey Mouse Club, but like Disney World, Universal, where if you go north of it, like north of downtown, you're about 45 minutes away from Disney World and you've got white collar jobs, you got strong blue collar, you've got a lot of R and D, government R and D investments just to the east of it. And so you have significant investments from different industries. So when I'm thinking about industries little known but artificial intelligence, I think it's the fourth or fifth largest in terms of development going on there in the country. Just east of it, you have your Lockheed Martin and north of Grubman doing significant R and D into Space Force, which is like the fourth branch of the military. And then just further east is Melbourne, where you've got a little over a billion dollars of pledged money by Jeff Bezos into their space program as well. What we've seen is cap rates come down. So, you know, I think last year we're thinking less than 5, or what we call in the industry sub 5 caps, that's too pricey. Now we're seeing low fours. And what we're seeing is a lot of this is just because like we're talking about the migration of folks moving there, but also just businesses are moving there. And then as a result we've got investment money coming there. Most of it we're seeing coming from the Northeast. So as you know, like in New York, for example, cap rate for maybe a multifamily could be around 2% or even lower. And now if you're looking in Jacksonville or Orlando and it's at say four, four and a quarter, that to them is cheap. But if you've been investing there historically in Florida, you feel like this is expensive. So just to kind of give you an idea, we're seeing a lot of competition. You know, specifically the Florida markets, about 40% of new debt being placed is being placed by out of state investors for the first time. So that's also telling you that there's a lot of new money flowing into Florida. And so we're Very optimistic about the Runway in central Florida and then including Jacksonville. I touched a little bit about northern Miami and why we like that. We're starting to. We're tracking where VC money is going. We're starting to see a lot of the VC funds. I shouldn't say a lot, but we're starting to see a significant number of VC funds allocating to startups in the northern Miami area. And also we're seeing the migration of the human resources. So I'm referring to the folks that are in the startup world going into that submarket as well. And with that puja, if you want to look to the next slide. And so this is some of the metrics I talked about earlier with just the home prices and seeing the home prices increasing, the net new migration of 1800 or so residents on a weekly basis into Orlando and then some other statistics on that in terms of employment trends. So correct. During pandemic we saw a loss of jobs. We're seeing this job growth come back strong and in fact we're seeing it exceedingly the pre pandemic levels. This has more to do with the fact that we've seen businesses migrate to Florida. Some part of that has to do with Florida staying open throughout the pandemic where some business owners had decided that that was a better place for their money and their investment. But we were seeing this migration even prior to the pandemic. Jacksonville, for example, we always said have a longer Runway. It's little known. And so we always felt it was three years behind maybe where Dallas and Austin and Orlando were on the growth cycle. Now we're seeing that come full circle where the cap compression and I think we're seeing more the normalization in pricing. We do anticipate pricing to continue to increase. We think caps are going to stay low for the longer term. Part of that just because there's a lot of upward pressure on inflation and also it's just the demand as a whole. So for example, we've underwritten well over 400 deals this year. Out of the 400, we were only able to make an offer on three or four. I think it was four. And out of the four, all four of them were well below what the sellers had wanted. We've been finding that some of the best route is just through relationships and off market. The reason I share that is just to give you an idea of how competitive the real estate market is in Florida, South Florida and some other places as well in the country. And we can skip through that. This is just the submarkets as a whole. This is specific to Orlando. If you look at 51 and 50 out on the east, that's what we call West Melbourne, Melbourne area. Along there is the Space coast. And that's where we've seen about a trillion dollars pledged government and then about a billion of Jeff Bezos. And I know Elon Musk is also launching his space program. Some offices are out there. That's formerly where Cape Canaveral in terms of NASA was. So a lot of those engineers have been rehired from the private sector and the government. We've seen some significant investments from other tech companies out there. What we haven't seen is a whole lot of new development there. There are a lot of new development in terms of class A in Orlando proper. That's where the numbers cluster, starting with the number 1, 2 and 3. But we haven't seen as much along the coast. So what we're seeing there is a significant shift in the demographics. And we own some assets out there where literally on the block you've got, you've got zero income. And those are mostly retirees. But it doesn't show up on the demographic as retirees, it just shows up as zero income. And then literally down the block you've got $200,000 of average income. If we go more towards Orlando, like I was showing, number one and two, that's downtown. If you go just southwest down towards 10, you're heading down to the tourism area, which I'm referring to as Disney World. If you go north of the number one up towards 17, which is north of downtown. Thanks, Kuja, for that. That's where you start to enter into more of just the job, the blue collar, white collar, and then just the workforce as a whole. And then if you continue going northeast from there, those are your. I would call your resident Orlando residents that are in the other industries such as artificial intelligence, healthcare, finance, and then just east out towards 23 and 38, you're going out towards like the research parks and you're going out towards dcf, which also during the last downturn. So this is during 2007, 2008, the strip malls that were in those areas had about 96% occupancy, while meanwhile Orlando's overall real estate market had dipped down to 85%. Much has changed in the last 15 years. We've seen significant improvement in terms of the number of businesses there. I just alluded to the number of loans that are taking place accounting for out of state capital. What I didn't tell you is that most of this capital is also taking on long term loans. So we're not looking at hard money, we're not looking at two or three year loans. We're looking at long term which tells you that capital is looking to, that's being placed there, is looking to stay there for long term, which is really great. So we're not going to see that same type of volatility. Say if we were experiencing another recession specific to Orlando. We think there'll be much more stability there. And then again there's certain sub markets that can outlast or, or do well through any downturn as well.
So folks, I just want to remind everyone, if you have questions, please go ahead and put it in the Q and A section and we will address as we are going through our towards the end. Thank you. Sapin, please go ahead.
Of course, sure, sure. I'm going to take a minute to talk about one of the submarkets we like Maitland. We own an asset over there as well. This is next to Winter park and Winter park is one of the prestigious neighborhoods. It's also about 10 minutes north of or think of cobblestone streets. You can think of upscale restaurants. It just, it's got a vibrant nightlife. You've got, you've got money there, old money there. Just well to do folks generally who reside in that area. You've got private schools. Maitland downtown is just to the west of it. Downtown Maitland is beautiful as well. It's also very similar to what we feel like from the park in terms of just restaurants. It's very walkable. It's also very non transient. So you see a lot of folks, old money meaning people that were residing there tend to be there. It's not where someone's just kind of moving through. So we tend to see a lot more of that. They just redone their downtown city center. One of the things that they're looking for doing over there is really just try to revitalize it so there's more folks that generally can enjoy and appreciate some of the public activities. And so that's one of the things we're seeing in downtown Maitland Submarket. We also like the demographics, you know, not just the jobs but the average income demographics about 84,000. If we go out towards different parts of Winter park, some of the nicer areas within like a 1 to 3 mile radius of here, you start to see that increase to about 148,000. I share that with you because the types of things we like to look at depends on what kind of an investor you are, you could be more focused on workforce, housing or class C. You're not going to find that here. You're going to go somewhere a little bit further out, either further west of Maitland or you're going to go further south where there's opportunity to get a greater cash on cash. But then you also have. What we're currently seeing is some higher age receivables because of, you know, job losses and other things. The types of assets we like to look for are composed of demographics like this. Where we feel we've got a stronger rent roll, the yield tends to be a little bit lower. But again, that's your risk reward. We like the comfortability of knowing that we're going to be achieving collections within the first week. You know, you tend to have lower bad debt, but also lower age receivables as a whole. So these are the types of sub markets that, you know, we look for when we're looking for deals ourselves. So it's highlighted here just to kind of give you an idea of what's important when we're looking at certain submarkets in terms of not just jobs but demographics and you know, what kind of class A opportunities are there as well.
So a quick question. How many units, how many assets under management do you have in Florida specifically?
Specifically Florida, I want to say we have about maybe 1500, 14 or 1500 doors.
That's awesome. And if you go back to the map before, what general area? So that's, that's total assets.
Yeah. So generally just in this one out east towards 51, we've got one asset, about 200 doors specific to the Orlando area except to see the cities, but it would probably be around like 17 or 13, like, or 31, like around there. We've got 320 doors there. The rest of ours are in Jacksonville, which is further north. And that's not on this map.
That's great. Thank you.
Sure. You can go to the next slide.
Yep. Sorry, let me just stop for a second.
Okay.
My. It just crashed on me. So give me one second here.
Yeah. While you're pulling it up, I would tell people when you're looking at where you want to invest, whether you're a GP or an lp, there's just like a checklist of stuff, you know, first is, do I like this area? Am I comfortable with it? Can I see myself invested in this area? And then the other part to it is if I'm a gp, I just want to know, do I have relationships here with vendors? Am I able to successfully run and manage this or is it just a one off? The one offs always scare me. Part of the reason is resources, right? And so as you go through cyclical times, let's just say and these are all experiences we've come across at various points. But if your lead maintenance guy leaves or maybe both your leasing folks are no longer on site because one's sick and the other one just quit, do you have the ability of pulling resources on there to continue to manage it? Do they know the location, do they know the assets? So these are certain things that you just want to check off but as an investor one I want to make sure my sponsor is active in the area, is also well versed with it and then also what are their projections? Is this comfortable investment for me in terms of the projections? Because some of them are going to be more aggressive than others and some of them are less aggressive. I think that just comes down to your risk tolerance. So as referring to ibu, class B is a little more risky as you move up towards class B plus and A, you have less risk, you have a little bit of a lower yield. But it depends on what type of investor your time horizon as well. So Pujanetta, you got back up if you want to go to the next few slides.
I think that's me. So okay, sure.
Thanks.
Evan7 gave a really good in depth state of the market for Florida and I'm going to talk a little bit about Texas. So you see that there's one common theme. Elon Musk likes the same areas that we do so likes the Orlando Melbourne area in the Space coast. And as I think it was like the buzz and the talk of the town that Tesla is coming to the Austin area. So we have properties in Texas in the DFW area, but we also have one in Austin and then you know Rohan and I are also reside here as well. So one of the reasons that we love the Texas market and specifically I'll focus more mainly on in the Austin area is you know, a lot of the larger companies as you know are continuously relocating to these cities. They say Austin's going to be the next Silicon Valley. Similar to Florida, you have business and landlord friendly climate. The housing costs are increasing. So if you're in the Austin area you probably are hearing this on a daily basis. You know, houses are in demand and there's just not enough housing available. So when you're buying a house here, the house prices have sometimes gone up I think about six figures. Asking price is, let's say if it's 100,000, it can go, you know, way above the asking price. People are paying all cash. You'll probably be seeing about 70 to 90 offers on a house. So very limited. What we like about that is then it pushes people who are coming and relocating to this area. Well, obviously it's very hard to get a house here at a, at a good cost or price because all the prices are increasing. So then they turn to multifamily and they want to rent. What's nice that what we're seeing with multifamily is that the rents are increasing as well, just due to the amount of demand. We also know that construction costs have increased as well. So it is becoming a lot more costly to develop. And, you know, there's also been a delay in supplies. So again, from a multifamily perspective, occupancy is really high. So you're not really seeing any concessions in this market. You really just don't need to. And then cap rates here are about 4% or below. It's actually probably compressed even more. And each month what we're seeing is that the prices are continuously rising in this area. So kind of a snapshot of why we like this is that we're continuously seeing a population increase. Unemployment's been actually really good here. It's been fairly steady in the Austin area. We're seeing a lot of growth. A lot of the bigger companies are coming to relocate here. Apple I think is building campus here. Tesla, Google and I think Samsung also is building an extension here as well. So they all kind of have campuses and headquarters here and then they're continuously expanding. And so this, like I mentioned, it's kind of called like the Silicon Hills and the next Silicon Valley. These are some of the big players that you'll see in this area and I'm sure more will be added to this list as the year goes on. Okay, so that was kind of a quick snapshot of Texas. And then I'm going to hand it off to Rohan. He's going to tell you a little bit about how JT Capital operates from, you know, how do we go about looking at a deal, what some of our criteria is, and then he's going to walk you through kind of a sample deal of, you know, what, what would we typically look at in the deal and kind of give you that end to end process there.
Awesome. And do you mind passing hosts real quick? My video had turned off for some reason.
Oh, sure, that'll be my V.
Okay, there we go. Awesome. Yeah. So as Pooja mentioned, I'll talk a little bit about, you know, how we operate our strategy. We'll walk into a sample deal how to think about returns in our business plan. But let me first start our strategy. So, you know, we've talked about the markets, both Florida and Texas, and where we invest. Our overall strategy is to look at these hundred unit to 500 unit apartment complexes. And what we look for is complexes that have below market rents. The reason for that is we believe that we are able to go in and execute a business plan that focuses on three pillars. The first is that we go in and we renovate units. So for example, we'll upgrade the countertops from laminate countertop to granite countertop. We will, you know, take out the carpeting and we'll put in place vinyl plank flooring and then we may upgrade fixtures and things like that. Second is that we'll fix up any of the deferred maintenance on the property. So some owners haven't done the best job of taking care of their property or it's just slightly outdated. So what we'll do is we will upgrade it, we will paint the exteriors of the buildings, we'll repave the parking lots, so on and so forth. And then lastly we'll put in place really high quality property management. We have a property management firm that we're partnered with that, you know, is a top 25 NMHC property manager. And they do a really good job at, you know, taking care of the assets and managing the day to day operations, which is crucially important to dealing with residents and the success of the property. So we do all of those things. And then ultimately what we do is we're executing on our business plan by renovating the assets, renovating the units, upgrading the condition of the properties. And through that time we're raising rents on each one of the units. And so when someone's lease expires, either they will pay a higher rent or somebody else who's going to fill that unit will pay a higher rent. After a handful of years, you know, anywhere from three to five years, we may do a combination of refinancing the properties because we've increased the value and so the property value has increased because we've raised rents. So in effect, you know, it's not uncommon to raise the value of a property from, you know, $30 million to 35 or $40 million within a handful of years. That whole time investors are getting cash flow because people are paying rent on the property. We're paying our Property expenses, we're paying our mortgage and then there's cash flow left over that is provided to investors. And, you know, again, after a handful of years, we'll do a combination of refinancing and selling the property at this updated valuation. We get deals primarily through relationships with brokers. So we've been doing this for quite some time. So we have, you know, just relationships that have compounded over time with brokers, lenders, our property management companies, so on and so forth. And then our business plan is again, always underpinning this increased cash flow. So as people invest, what they see is rates of return that continue to get higher and higher as the years go on. And in the next slide, I'll kind of talk through a sample deal structure. So when we go to purchase a property.
Can I ask you a question? If you go back to the previous slide and what was very interesting when I was talking to you guys is your PM team and it's easy to just understand that, okay, there is a property management team who's in place and taken care of. But what's very interesting is that this PM team actually, when Rohan says that it's top 25, they have a criteria, extensive criteria to approval, criteria to go through so that they can be your pm. So can you. I was really surprised at that. And that kind of shows that confidence not only on operators as you as operator, but also the investments that are, that you are undertaking. Right. So they kind of, you know, bless this team, bless the investments. Before you go, can you elaborate a little bit on that process, please?
Yeah, for sure. So, you know, Bell Partners is a property management firm. They're an institutional level player. So really most of the clients that they're taking on are people like other institutions or private equity firms or so on and so forth. Right. That have been around for a really long time, decades for us. And to really, to Supin's credit, he led us through the process of going through their due diligence process of vetting us out to make sure that we were the right kind of partner, that we were growing our portfolio, that they could manage our assets, that we knew what we were doing, so on and so forth. And so, you know, when we look at kind of our company structure and we look at what we've done in terms of growing our portfolio and growing our assets, we do look at it is that we're probably one of the only people or one of the only groups that is, you know, in our kind of stage that is being taken on by a property management company like this. And so, you know, that's a huge vote of confidence. The other thing I think that that ultimately does is it provides us a real advantage when you know, investors are looking to place capital. You know, I look at a lot of other kind of like real estate private equity firms at our stage and I haven't really seen anyone that has had the weight of a property management firm like this behind, behind them. So for us this really de risks a lot of the execution plan of our deals.
Thank you for sharing that, Johan.
And so you know, when we go by these deals, typically it's financed with a combination of debt and equ. Right. So a sample deal structure looks a little bit like this. On the left hand side in that chart you'll see there's a general partner. The general partner are the people that are managing the hands on acquisition and management of the deal. So that's myself, Pooja and Supin. Then there's limited partners. Limited partners are effectively the passive investors. These are people that are providing the cash to go finance a portion of the purchase of the asset. And in return they say I want to get a return on my money. So typically we'll have two to three different classes of limited partners. In this example there's limited partners A, B and C. And you'll see down below in the descriptions it'll say limited partner comes in with an investment of below a couple hundred thousand dollars and they receive a 7% preferred return and a 7030 split thereafter. What this means is that when the property is generating the cash flow, the first 7% goes back to the investor, the limited partner before we, as the general partners are paid from the cash flow of the property. This is, you know, aligns incentives to a certain extent, but really it's just better for the LP because they're getting the, they're preferred in the capital stack, meaning they're getting paid first. The second is limited partner B where it's a higher investment amount of a couple hundred grand up to $500,000. A slightly higher preferred return of 8% and again that 7030 split thereafter. And that 7030 is, you know, anything that is generated incrementally over and above that 7 or 8% is split, 70% goes to the limited partner and then 30% goes to us. And let me just make you host real quick. There you go. And then lastly it's limited partner C. So this is people with, again in this example deal that we had done, people who bring an investment of half a million or greater. Again a Slightly higher preferred return and another split there. And then the general partner gets the 30% from up to 13%. Right. So over and above that preferred rate of return is the baseline up to 13% IRR. Once the 13 IRR is hit, then there's a 50, 50 split effectively to incentivize the GP and reward the GP for getting above market returns. Then the last piece on that chart on the left hand side is debt. And so, you know, we work with loan brokers to be able to source advantageous debt. Right now we're in a pretty low interest rate environment. So we see interest rates anywhere from, you know, maybe 2.75%, maybe up to a little bit below 4%. And you know, it's advantageous fixed rate debt, especially for properties that are generating over and above that, because then you have that incremental margin. And then on the right hand and.
Being in business for such a long time. Right. Could you speak to some of the broker relationships that you have?
Yeah, broker relationships are everything really, you know, getting. Let's break it up into two parts. One is the real estate brokers and two is, you know, primarily loan brokers. On the real estate broker side, you know, competition for deals is really high, as Suppin had mentioned in the very beginning. And so, you know, if there's one deal that gets distributed to a lot of people on an email list, there's hundreds of people that are competitive that are coming in with offers. And really that's not a position that you want to be in because you're competing with a lot of other buyers for just supply of one asset. And what happens at the price continues to get bid up and bid up, as I'm sure many of you see, you know, just in the single family home market. And so having these relationships with real estate brokers allows you the opportunity to get the first look sometimes at deals that ideally are off market. And so that's kind of, you know, our current strategy mostly is to get off market deals of which, you know, has seemed to work out and will work out this year and shortly. And so that's super important. And it just takes a lot of time to establish the relationships because you execute on the deals, you're good to work with, you close on time, you never have any issues, all of those kinds of things. So it's just a competitive advantage that we've built up over time by virtue of doing, you know, deals. Second is loan brokers. These are the people that are going to source. We really only work with one person because she's been an amazing asset and partner to our company and she really helps us source advantageous debt. And we've been able to just get fantastic terms to purchase these assets.
Thank you.
On the right side of the page is just a return summary. So, you know, you'll see again the classes limited partner A, B, C. The equity multiple is just a way to think about what happens to your money. Right? What is the multiple that you're getting on your money? Example, limited Partner A is 1.84. B is 1.89. A very simple way to think about that is if you have a hundred grand, what is a hundred grand times 1.89, right? And that is your return that you will get. You can turn 100 grand, excuse me, in this example, into 184 grand, 100 grand for limited partner B into 189 grand, limited partner C, 100 grand into 194 grand, effectively almost doubling your money within this, you know, time frame of this prior deal that we had done. CoC is the average cash on cash return. Cash on cash is just a formula to say what is the cash flow return that you're getting? If you invest a million dollars and you get 70 grand in distributions, that's 7% cash on cash return. And then annualized just includes the sale of the asset. So while we're holding the asset, everybody's getting cash flow throughout that time from the rent that people are paying. It's increasing because we're increasing rents. But at some point we go sell that property. When we go sell that property at a higher valuation, then, you know, investors get a large equity gain from that. And then your return has increased, in this case, you know, going from an average cash on cash of 7 to 17 and so on and so forth. And then in the next one. Yeah, so this is just again, kind of like a better visual representation of an individual's a particular investment, again, if they were a class A in the prior slide. So you can see in the first line, it shows the initial investment of $100,000. In the second line, it shows the annual preferred return that that person gets of 7% every year. And the third line you'll see that equates to $7,000 because it's simply 7% of 100 grand. That happens for the five years. And then down below, you'll see the equity gain from the sale. This is what we estimate, estimate that when we go sell the property, we will get this gain on that property. And then lastly, the investors Principal investment is returned. So what they invested, they get back as well. So that's where you can see, you know, you invest 100 grand and then you see the total returns on the right hand side. You get 35 grand from the cash flow of the property. You get 48, 9:50 from the sale of the property. You get your principal back of 100 grand and that results in a total investment return of roughly $184,000.
And I just like to add a little bit here, Rohan, if you don't mind. So just to compare with the real estate, the rental real estate, right, if you have that 100k as a down payment towards a rental house, say in Austin area, which is about $350,000, having that 7,000 divided over 12 months is about 580 in cash flow. So we all know that in Austin it's so hard to have that cash flow. So if you are, you know, thinking about buying a rental in the market, this is a good way of going into the, the real estate market that you want and still have that cash flow. So you know, just, just keep that in mind. Thank you, Rohan.
Yeah, that's a great point. And then not to mention that, you know, two things actually. One, this is completely passive from an investor standpoint, right. Versus a single family house. You know, they maybe need to be a little bit actively involved with the managing of the resident. And then two, what we haven't discussed here, and I'll try not to go into too much detail because it, you know, we can go down a rabbit hole, but we also get great tax advantages. So in these large multifamily apartment complexes, we get, we take depreciation and then on top of that depreciation we do something called cost segregation, which we apply depreciation to every item on the property. The windows on the buildings, the computers in the leasing office, the granite countertops in the units, all of those things which results in a much higher depreciation amount. And then using bonus depreciation, we apply all of that to the early years. In effect, what that means is, is someone invest a hundred thousand dollars into a deal year one, you know, you can see here, they might get seven grand in cash flow, but from for tax purposes, they ultimately end up being able to write off like 40 or $50,000, which you know, is very advantageous from tax benefits. And you can really only do that for, you know, larger apartment complexes and other commercial real estate because it costs a lot of money to go get that, that cost segregation study done for the Depreciation.
A quick question, Rohan. Do you have only accredited investors participating in your deals or do you have sophisticated as well as accredited investors?
We take both sophisticated and accredited. Just on any given deal we can only take up to 35 sophisticated investors, I believe is the number 35 out of, you know, the, the investor pool.
Thank you. Thank you, Johan.
Great. And then on the next page, I'll just go into a little bit of detail on our business plan. So as I mentioned, you know, a couple, one of the three pillars that we have as we execute our business plan on properties is to do interior renovations, upgrade the interior, and then, you know, focus on other revenue generating items on the interiors. What we do is, you know, on this prior deal that we had done, we rent, renovate over 100 units. We have an assumption of what we can increase rents on. In this example, you know, we assumed $150 rent bumps. In our model. We like to be conservative. You know, what we're seeing right now is like, you know, 400 rent bumps versus what we had estimated. So, you know, usually we're, we don't want to hedge so much, but you know, sometimes the market kind of works out for you two is then the renovations that we actually include. So like I said, things like faux wood flooring, upgraded appliances, lighting, ceiling fan, so on and so forth. Exterior renovations, again, this will be things like, you know, painting the exteriors of the buildings, converting particular areas on a property that might generate more value than it had previously, like a tennis court conversion, upgrading the amenity spaces and, you know, making sure the landscaping is nice. And then lastly, we just look for other revenue generating opportunities. Valet, trash, laundry, income, covered parking, so on and so forth. So yeah, just to wrap it up, I guess, you know, that's a little bit about us. You know, we are really focused on these markets both in Texas and Florida, their major metros. We like both states and cities equally. You know, I would probably argue actually right now the pricing is much better in Florida than it is in Texas. And I don't believe you're actually taking on as much risk. And you know, our business plan and our execution plan is things that we felt pretty confident in historically and we feel what we continue to feel confident in and, you know, generate good returns for investors and everything like that. So, yeah, thanks for allowing us to be here and explain all of this to everybody and happy to answer any questions or anything like that.
Thank you so much, everyone. And for those who are listening and watching, I've launched a poll. If you are interested in investing on the upcoming investments with JT Capital or any other partners we think outside the stocks. Please go ahead and you know, complete that poll. Like Rohan mentioned, they do take sophisticated and accredited investors. So as per the SEC guideline, before they have the investment, we need to get connected. We need to, you know, learn about each other. I need to learn about you as an investor so that we could offer that. Otherwise I won't be able to send this investment opportunity to you. So please go ahead and provide that information and if you would just like to get connected with us, just, just let us know. Any questions, please put it into QA Q&A box. You know, Sapan, Pooja and Rohan did excellent job about talking about the markets. The overview, their strategy and few of the great points about them is when, you know, when they are, you know, approaching these properties, they have this broker relationships, they have these insights into the market. The brokers and the sellers also have that confidence that they are going to be one that they are able to close these deals. Most of the times even if there is a bidding war, it typically doesn't just goes to the higher bidder in terms of the price of the property. But they also look at the strong track record of the sponsor team, that is the syndication team. So when they see that, okay, they are going to be most likely without any hiccups, going to be able to close on time. That's what seller is really interested in. So with their track record with lenders, with broker, with the units, the portfolio that they have under management, that is what builds the confidence. And when they were talking about the investors, the class A, B and Cs, you notice that there are investors who are putting half a million dollars in their investment. So they, that also kind of indicates another level of confidence. And you know, it's very important to understand that the numbers, anybody can show that numbers. But truly if you can, you know, come up to that numbers, if you can meet that numbers, that's one of the important thing as an investor that you should note. Any more questions, please, please go ahead and put it in there. I think we do have a question. Why not San Antonio?
Yeah, I can take that. You know, we haven't been able to really wrap our heads around San Antonio yet. Like when I look at places like Austin and Dallas, you know, I've seen a significant amount of, you know, what I would classify both as like technology, finance and venture capital investment. San Antonio, there's been, you know, some job growth and things like that. But we haven't yet seen the kind of like one, diversity of job growth that we want to, that we would want to see. And then two, in San Antonio, there's been a lot of new development. And so one, you know, really important aspect to look at in, as you like, think about these multifamily apartment complexes is that if there's oversupply versus the demand, you're going to be in a tough spot because you're not going to be able to, one, raise rents as you want, and then two, you're going to have occupancy issues. And so that's one thing to always look at is, you know, what is the development pipeline look like in a particular market and submarket and will that demand meet that supply in a place like Austin? There's also a lot of development. But what's been shown, you know, for the prior couple years and at least like how we forecast it, is that demand will continue to meet supply. And in Austin, we're just not entirely sure about that yet.
Thank you so much. Dohan. We have another question of about Houston markets. Why not Houston? Are their houses mostly flooded?
Yeah, there's certainly some, you know, like, higher risks as it relates to flooding in Houston versus some of the other cities in Texas. You know, for Houston, it's mostly the reliance on the oil and gas industry. And so, you know, what we've just seen is like, higher unemployment rates during levels of like, you know, macro oil fluctuations. I like Houston. Like, actually my dad lives in Houston, so I really like the city. I think it's great. But from a investment perspective, we just haven't been able to kind of get comfortable with the risks there yet. And that's one of our biggest things is, like, we are looking at the landscape of risks and how do we mitigate all those risks.
Thank you. And another question about the market. Why not? What about the secondary tertiary markets like College Station, for example?
Yeah, good question. You know, a little bit similar in terms of my last answer about the risk and how we think about it. Like, new College Station is good, I believe Texas A and M is right in there. But we are looking at major metros that have high population growth, one, high job growth two. But then most importantly, like within those two buckets is diversity of job growth. And so, you know, we want to be in places where if one industry gets hit, it's okay because there's a bunch of other industries there that will still support the residents that are, you know, living in our property or are just in that general market. And you know, we look at actually like these major metros that we're investing in. We believe they're secondary markets. And then some of the smaller cities, those are really the tertiary markets. They do well in these kind of like times of macroeconomic expansion. But at the first point there, there is a downturn. That's where those tertiary markets kind of get hit. And so we just haven't been comfortable kind of, you know, putting our own capital, investors, capital at risk in the tertiary markets.
I love, love that perspective. I think one of the things, notable things I had noticed when I was talking to you guys for the first time is your focus on capital preservation. So can you elaborate a little bit and share with our viewers today that how, how you focus on capital preservation?
Sure. So I can start off and then I know Sapin also likes to, you know, talk about how we think about this. But yeah, you know, so Warren Buffett has this rule like number one rule of investing is don't lose money. And then the second rule is, you know, don't forget rule number one. And so that's how we think about it too. And especially in real estate, right? So if you think about something like venture capital, you're going to lose a lot, you're going to lose money, right? Like if you're in venture capital, you make, you know, 10 investments, one investment or. Yeah, so if you do that, like six investments are going to zero. You know, one investment is going to generate a 10x return, two investments are going to generate a 5x return and then one investment is going to generate a thousand extra turn. Right. Like that's the good portfolio construction of a venture capitalist for a real estate investor. There's absolutely no reason in like the, the what we invest in these stabilized assets and everything like that and these major metros and in good states and high growth places that we should ever lose money because we're buying properties that have 90% plus occupancy already. So there's already cash flow coming in from day one. We're investing in markets that have this population growth, job growth, you know, diversity of jobs, all of that stuff. A lot of things would need to go wrong for us to put investor capital at risk in that way, you know, even if we perform poorly, that poor performance should still result in at least like, you know, 1% return. And so, you know, the way we think about it is like you never want to put capital investor capital at risk. And then we just do that through our actions. And it's primarily focused on the asset class that we're investing in and the areas that, that we're investing in something. I don't know if you'd add anything, you know, additional to that.
No, you covered the basis and that's right. That's exactly how we see it.
That's perfect. And I think another question is just related, going back to your Florida market, I mean, Florida saw that drop in employment. How do you see that? Your investments, they sustained through that. I know there was a lot of people whose jobs got impacted, they couldn't pay the rent. So the economic vacancy, what we call it, that went down throughout the US and what it means to viewers is, you know, essentially you have still the occupancy tenants are still staying in this house, these homes, these apartments, but they're just not being able to pay the rent. And due to eviction memorandum, you know, there is no evictions because of the COVID impacted tenants. So how did your properties perform during that? And that's kind of a good, you know, speaks to what you just shared.
Sure.
From the capital preservation point of view.
Yes. I could touch upon it and then Pooja, if you want to talk a little bit about it, just from that asset management side. But if we look at, you know, and then we talked about the employment and we saw that dip, a large portion of that dip was really attributed to just like the tourism sector. So it was the tourist destinations. Right. That type of stuff, that's really where the job losses happened. But if you look at the other industries, they had remained strong, you know. So for example, like on a macroscopic level, we can say the economic output to recover in Orlando probably happened a lot sooner than, you know, in maybe healthcare technology, financial services, say manufacturing, construction, like those are all parts of different areas in Orlando that didn't really have that same impact. Whereas on the tourism level, so that's where we're talking about like the Disney World, you're going to see that. So like the national reports that we look at, like the one that was even on here, you're not going to see what we call like the secular sectors where the tourism corridor, which is that south part of downtown we talked about, it's often just lumped together with like these professional, skilled oriented jobs where now it's in a way skewing the numbers, if that makes sense. The way we're looking at the assets. And then Covid is very similar. Even before COVID you know, we never really looked at assets that were predominantly supported by employment related to, you know, tourism or cyclical businesses. So when I say cyclical, that's also related to in downturns, these businesses tend to also suffer as well. Ron alluded to earlier, I'm going to use oil and gas for example. So Houston's a great market, but let's just move further east out towards Louisiana or Mobile, Alabama, some of those places where they're largely driven by oil and gas. And maybe there's one strip mall that's just not too far from getting onto that platform. And then you got this multifamily. Basically the outcome of that industry is really going to be the outcome of your performance on that specific, specific asset. You're not in really a city. And so the way we've looked at it is when we're in, I mean central Florida, because the question was on that, you know, we want to even within there be in these sub markets specific to like the metro, where we do have exposure to, you know, these secular white collars like the healthcare, those professional services, you know, other things are the fintech, video game development, animation, all of that is happening east of downtown and north. And so you got that space program even further east. And so through the pandemic as an example, we were at one point raising rents and then we stayed flat on an asset further east about an hour east of Orlando. Our bad debt and age receivables never really exceeded, I think it was like 1 1/2 or 2% at the most and maybe even less than that. Collections were very strong still well within eight days, the first eight days of the month. So they slid just a little bit. But they're very comfortable. Where I think the national average for collections to peak in the course of a month at one point was between day 13, 14 and day 16 or 17. And even then collections had dipped just south of 90%. And then I think around mid year last year, people were thrilled when we were at 91% average collections, whereas on our assets we were still north in the high 90s, like 98, 99%. So I think it kind of, if we look at national reports, it tells you one story. I think if you're well vested in a specific area, then you can start looking at the secular reports and that starts to tell you the true story of based on like where you are within that metro, you know, how comfortable are you with your investment as an investor, how comfortable are you as an owner operator with your asset? And then what types of measures do you have to take? Either remediate any issues or address any issues as you start to see them. So that's the other thing, right. Is you should be looking at forward looking metrics. And so one of the things I alluded to earlier, we saw a negative 1% rent growth like in Orlando during the meat of that pandemic. If I'm an operator that's experiencing that on my own asset, I go into preservation mode versus rent growth mode. Right. And so it's just you change the way you operate so you can still achieve what you're trying to achieve in the long term. Because these things are just ebbs and flows. It's not a permanent thing. But then just kind of going back to, at the end of the day, it's just the data points, right. Of where you're invested, where your location, asset location is. And then I'm, you know, I think the three of us are big believers in jobs, jobs, jobs. Because that's what's ultimately going to drive like the revenue on your asset.
Yeah.
And I'll just touch base a little bit about COVID the eviction process. So obviously some assets were hit harder than others.
Some.
It wasn't really a difference. Right. It was kind of status quo, same as usual for those that we had a little bit of a higher delinquency. You know, one thing that was really challenging, not just for us, but I think just across the nation is the moratoriums and the CDC declarations and the it either keeps getting extended or the stipulations kept changing. And so you just had to be very flexible and work with the new guidelines that were coming out every month, every other month, and then just constantly changing. And then also there's the national guidelines, but then there's also city guidelines or county guidelines. Right. Which may be a little bit different. So what we were dealing with in Texas, we may not be dealing with in Florida and vice versa. So you had all these different things to play with. One thing that's really interesting is on some of the assets where there is still delinquency and people who won't leave, you know, we are still able to evict and you just had to do it the right way. You know, whether it's giving a 30 day notice, a 60 day notice, a three day notice. So there's all these guidelines that you had to do, but you said still were able to evict. The other thing we're seeing is even though we have that our rents are actually increasing. So that's really interesting. And it just kind of shows you because of the demand of the area, you're still able to start now you're starting to see these rent bumps. And so in some of our properties we're seeing like $20 rent bumps or $50 rent bumps. And that's just within a week. So when you do that week over week over week, you know, we went from one one was at 1145. Now the base price is $1200. So we are constantly looking at that metric and we're actually looking at it on a weekly basis. And there's a pricing team that evaluates what's going on in the market. They look at your occupancy, they look at how much availability you have, how much traffic you've had to the site. So there's a lot that goes through, goes into those numbers. So while you still may be in the process of evicting, you're still able to increase your income from the raising the rental prices. And then they're actually, I think the federal judge just yesterday announced that they don't think that the CDC mandate was done correctly and they shouldn't have been able to do that. So it'll be interesting to see, you know, what more comes out of that and if that helps multifamily in general.
Yeah, I love that perspective. And to me it looks like almost like a three prong approach. The first, you know, decision making is about selecting that market. What you guys have been sharing is about, you know, not being dependent on just one particular service area. And that's why you're not going to those markets where it's just, you know, very specific to one or two industries. You are just looking at to be in the market where there's multiple job opportunities, multiple service areas are being focused. Right. So that's why that's really important. And the second is with the amount of experience you guys have 3,000 plus units and I think it's over $300 million portfolio now. Right. With that, I think Covid kind of put all these skills and experience to test those who are the season operators, the season syndicators, they survived and, or they could react to this kind of things being thrown their way. There are always risk and issues happen throughout any project. It's just about how you can react. And the third aspect of it, like all three of you coming from that consulting background, that Fortune 500 background, that kind of helps to put that together whenever there is any risk. So today is Covid, tomorrow there could be anything else. But it's about putting that strategic plan together and executing it to the success. I think that what to me Looks like that has helped you guys to sustain this Covid times.
Yeah, absolutely. Definitely. Having a strong team and the right partners is very important in in executing the business plan or if there's a challenge coming up with that solution.
Thank you. And we had a question from Gurdre Rohan. Thanks for answering that. What is the typical timeline about the acquisition to the sale of these assets? And it's typically three to five years. Again I really like to go back and relate to the single family world because when you purchase and you move into rental real estate, right, even if it's appreciating, it's not like that you're going to turn around and sell it to the second year even if you do have that control that you could sell it within a couple of years. The whole appreciation and realization of that equity minus the expense at the sale, which is typically 6 to 8% expense at the sale, it's wise to stay even the single family home rental that you purchase and you have complete control typically three to five years. And at times people even go 10 years to hold that asset. So I love to compare that again that, you know it's a three to five years in this indication as well. Just like single family home, this does provide that cash flow. Just like single family home, the mortgages does, you know, do end up paying the principal down and at the end of it you do get that equity that you paid down into the mortgages as well as the appreciation that has happened. And appreciation, as Rohan was explaining, based on the net operating income in multifamily environment is different than what the market or relative appreciation of a single family market is. So that's really important to notice. And you get all these advantages by being completely, completely passive. This is the team who is experienced. This is the team who can take care of all the nuisance away of finding that deal, implementing that business plan and executing that sell while your money just essentially starts showing up once you invest in your bank account or if it's called mailbox money if you want the checks, right. So that's really important to note. So I really appreciate everyone you hanging in over 20 minutes late. This is a weekday so it becomes crucial and I cannot thank you enough. JT Capital Team, thank you so much for your patience. Thank you for going through systematically as well as answering all these questions patiently and very diligently. It is great to have you. If you guys have any questions please this is your last chance. Just put it in your questions otherwise we are just wrapping it up. Again, thank you so much for joining today. Any parting thoughts? Teddy Capital Puja Sapan, Rohan, just thank.
You for, for having us on. We're really happy and excited to be here and hopefully you guys learned a little bit more about what we do as well as a little bit more about multifamily and the markets that we look at.
Thank you so much. You have a great weekend.
Thanks.
Bye, everyone.
Thanks, everybody.
Everybody saying thank you in the chat window. Thanks for being here. Bye.
More from Madhavi

The "Holy Grail" Real Estate Strategy Most Passive Investors Miss | Featuring Glenn Hanson

Be fearful when others are greedy, and greedy when others are fearful. #shorts

Building Recession-Proof Wealth Through Mobile Home Parks & Self-Storage with Matt Ricardella

The "Holy Grail" Real Estate Strategy Most Passive Investors Miss | Featuring Glenn Hanson
Think Outside the Stocks: Breaking the Financial Fear Barrier with Liz Faircloth
Why Health Is Your Greatest Financial Investment | Chris Orestis with Madhavi Jain
The #1 Retirement Killer That's NOT the Stock Market (Most People Miss This)
EP47: Private Credit Explained: Stratus Financial’s Impact Investment Model | Brandon Interview