The 7 Levels of Wealth: Which One Are You Stuck In?
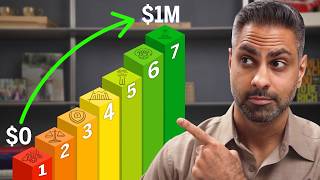
Ramit Sethi presents a seven-level framework for personal finance (Survival → Stability → Security → Growth → Freedom → Abundance → Legacy), explains how to recognize which level you’re in, and gives concrete actions and numeric targets to advance (e.g., emergency fund 3–6 months, save/invest 5–10%+ of take-home pay, negotiate advisor fees). The video mixes behavioral advice (automation, identify "money dials", change beliefs) with strategic moves (increase income, raise investment rate progressively) and ends with sponsor and next-video calls-to-action.
Chapters
There are seven levels to personal finance, but most people never make it past level three. They get stuck in survival or stability, and then they spend years treading water, never knowing why money feels hard. And here's the problem. Most people don't even know these levels exist. They don't know where they are, what they're doing wrong, or how to move forward. So in this video, I'm going to show you the seven levels of personal finance and what you should be doing in each one to build wealth and live your rich life. Let's get started with level one, survival. Now, if you are in survival mode, money feels like it's controlling you. You're constantly on edge, and one unexpected expense can throw your whole life into chaos. So how do you know if you're here? You probably don't know how much you make. You don't know how much you owe. You constantly feel behind or genuinely are behind on on rent, credit card bills, utilities, and any emergency feels catastrophic. Here's what to focus on at this level. Start by getting brutally honest about your numbers. First, figure out how much you actually make. I say that because I'm shocked by how many people can't answer this. 50% of the guests on my podcast don't even know their gross income. If you don't know how much you make, everything else in your finances is a guess. And if that's you, that's okay, because today's the day you're going to stop guessing and start leading. If you are paid hourly, I'm going to give you a quick little tip. Double your hourly wage and add three zeros. That's a good approximate way to figure out how much you make per year. So $20 an hour is about $40,000 a year. Next, open up every account. Write down every bill, every debt, every expense. You can use a debt calculator to see when your debt will actually be paid off. And I'll link our free calculator in the description below. Get answers to these questions. How much are you saving every month? How much are you investing every month? And how much are you spending on housing? You need to know these numbers cold and then start small. Save $20 a month just to prove to yourself that you can then save 50. Then take a second to reflect. What are your invisible scripts or deeply held beliefs about money? These are thoughts like credit cards are evil or you're throwing money away on rent or rich people are a holes. Some might help you. Some of these invisible scripts might be holding you back. Decide what beliefs serve you Let go of the rest. And one final tip that's really important at this level. Increase your income. Sometimes there's only so much you can save for. Sometimes you just need to focus on increasing that income level. 2. Stability. If you're at this level, good news. You're no longer drowning. You're paying your bills. You still might have some debt, but that debt is probably not growing dramatically. You can finally take a breath, but it's still tight. You want to save, but often people at this level cannot consistently do so. And here's how you know you're here. You can cover your basic needs. You're making at least minimum payments on debt. You're not overdrafting at the bank. But saving and planning ahead still feel hard. So what do you do? The answer? You start building systems. This is where you implement a conscious spending plan, which you can get for free in the description below. You automate your bills, you automate your debt payments, and you automate your savings. You're not doing any of those things manually anymore. Don't rely on willpower. That's the key to getting out of this level and moving up. Aim to save and invest at least 5% of your take home pay. If you don't know how to start, try a basic investment calculator and plug in $100, $200, $500 a month with a 7% return. You can use the calculator that I link below. You'll see the difference between I'll do it someday and I started now. That difference can be worth hundreds of thousands of dollars over your lifetime. And when people see these numbers which take like 10 seconds to plug in, it lights a fire under their. Also, if you have high interest debt, call and negotiate that rate down. Sometimes this works and it can save you thousands. That way you can reallocate money from interest payments to building your savings and growing your investments in the next level. After taking care of the necessities, take some time to identify your money dials. Here's the question I want to ask you. If I give you $25,000 right now and told you to spend it on one category of your life. Travel, food, wellness, whatever you love, no guilt, no questions asked, what would it be? That answer is your number one money dial and let's build your spending plan around that. The key here is consistency. You are laying the foundation for everything that comes next. Stability gets you out of this crisis mode, but security? That's when you finally start building wealth with confidence. Level 3 Security. Security is the first level where you can finally look forward instead of constantly looking back. And that is a huge feeling. At this level, you're feeling much calmer. You're saving, you're. You're investing. You're not waking up in the middle of the night panicking about your account balance. You know you're here. If you know how much you make and spend, you have a small emergency fund, your debt is gone or it's under control and you have started investing consistently. What should you be doing now? My answer, Focus on growing your emergency fund and increasing your investments. Make sure your emergency fund covers at least three to six months of expenses. And also increase your investments to at least 10% of your take home pay. If you have a 401k, great. Include that. Don't overthink the whole pre tax versus post tax thing in the grand scheme. It's not that meaningful of a difference. Start learning about your crossover point. This is the moment when your investments make you more money. You need to know that number. It could take you 15 years or 20 years from now, but when you know that target, it shows you how quickly you are moving towards your goals. Now you're making smart money decisions. You're saving, you're investing, you're thinking about the future, including your crossover point. But there's one money decision a lot of people don't rethink. That's their financial advisor. If you are working with someone who charges you 1% AUM, that's 1% of your assets under management, I strongly recommend you take a second look. Do you even know how much you're paying your financial advisor? Most people don't. And then they tell me, ramit, I can't get rid of this guy. He sends me a birthday card. He helped my parents. He, he took a mini golf one time. He's so nice. Okay, I'm sure Chet is nice. But a nice Advisor Charging you 1% could cost you literally hundreds of thousands of dollars over your lifetime. Now if you want a financial advisor to look over your plan, look over your investments, that's okay. I've hired one myself to review my asset allocation. But I would pay flat fee, not on a percentage basis. That is what you call a flat rate financial planner. Like our friends at Facet, the sponsor of this video, Facet will help you understand and expand your financial opportunities by providing you flexible access to a team of financial planners, CFP professionals, and a team of professionals providing guidance across retirement planning, tax strategy, estate planning and more. Facet charges an affordable flat membership fee so you can get the advice and support you want without spending tens or even hundreds of thousands of dollars on fees. I've used them to help couples on my podcast understand specific scenarios. Can they retire early? Can they pay for their kids college? Can they take nicer vacations every year? Head over to facet.com ramit or click the link below to learn more and find the membership option that fits your financial goals. Once you've stopped overpaying for advice, you can free up thousands of dollars to invest smarter. And that's exactly what Level 4 is about. Turning momentum into serious growth. Welcome to the level where wealth starts building upon itself. At this stage, you're no longer reacting to money. You are being highly intentional with it. You know you're in growth mode. If your investments are growing and they are consistent, you know when you'll hit $100,000 or even a million dollars. You think in terms of percentages and strategy. And finally, you've made trade offs to grow your wealth at this stage. Here's what to focus on now. I want you to consider increasing your investment rate by 1% per year. So if you're at 10%, increase it to 11 and then 12 and then 13. Use compound interest calculators to visualize what your money will look like in 10, 20, 30 years. Ask yourself, when do I want to become work optional next? Audit your money dials. Reallocate your money and spend it where it really matters. And most importantly, start reflecting. Ask yourself, what money beliefs have I changed my mind about in the last five years? 10 years? This reflection is one of the clearest signs that you are financially maturing. Real quick hit. Subscribe. You're not here for generic advice from some 19 year old crypto bro who still lives with his parents and uses one of those little freaking polyester blankets every night. You're here to think bigger. To build real wealth. To design your rich life. All right, let's move into level five, Freedom. Now we are truly entering one of the most exciting stages. It's not just that you're secure. You have options if you want. You can quit your job. You can take a sabbatical. You can start a business, spend more time with your family. How do you know you're here? Well, you could stop working tomorrow and be fine. You can say no to work you don't want to do. And you are now planning ahead in years, not in paychecks or months. What should you do at this level? I really want you to define your rich life. What is it all for? Put your hand Out. Yes. You put your hand out, palms up. What do I get? That's a question you should be asking yourself. And if you're in a relationship, you both should be asking, hey, we work hard, we spend a lot of time doing this. What do we get? What are you gonna do with all this freedom that you have earned? Maybe it's working less, maybe not. Maybe it's traveling. Maybe it's traveling in a nicer way or a more adventurous way. Maybe it's being more charitable. The point is you have to be intentional. Nobody ever trips and falls their way into a rich life. Next up, I want you to set a worry free number. That's a dollar amount under which you don't even think about it. You don't worry about it. What? When we were kids, it was 99 cents. That little pack of gum, maybe. Now as an adult, most people, they start at $20. Anything below $20 I'm not going to worry about. But as your income and net worth grows, you should adjust that number upwards. For example, I know people who have worry free numbers of $2,000, even $10,000. Choose the number that's right for you and the point is to consciously shift your mindset from scarcity to freedom. Level six, abundance. At this level, your systems are dialed in, your income is solid, your investments are growing. But the real difference, you know how to enjoy your money. You are here. If you've maxed out your financial systems, if you spend freely on the things you love, if you've built a financial team as required, including an accountant, perhaps an attorney, perhaps an advisor, whatever team you need to run smoothly. And finally, you give generously. Now, what should you focus on at this level? My suggestion is you create certain areas of your life that are no budget zones. For example, you might say, I never question anything spent on health or anything for our kids education. We're not going to question on what are the no budget zones that you might have in your life. For me, it's books. I am never going to question the price of a book. If I see something that looks good, boom, I'm going to buy it. Refine your team. Find new ways to give back. You are fortunate to have made it to this level. You probably benefited from lots of people around you and you can give back not just with money, but with time and wisdom too. At this level, money is no longer purely about roi, it's actually about impact and joy. Level seven, legacy. This is the highest level and for the first time, it is not purely about you. You're here to create an impact for your family, your community, future generations. You know you're here if you've achieved true financial independence, if you are thinking bigger than yourself, even generationally. And in fact, if you are building something bigger than yourself, here's where to focus. Get clear on your legacy goals. What do you want to be remembered for besides money? What do you want your kids or your community to say about your legacy? Were there specific organizations that had a huge impact on you growing up that now you can sustain? Perhaps the public library where you read books, learned to read in your case. You can set up trusts. You can create an estate plan. You can think succession. It's not just a TV show, it's actually what you do with your money that can sustain beyond your life alone. Teach others what you've learned. Generational wealth is not just about writing people a big fat check. It can be spending time mentoring them, teaching them, sharing and surround yourself with people thinking on this level. This is where money becomes a highly influential tool to build something truly meaningful. If you made it this far, you are already operating at a higher level with money than the vast majority of people. You're not just managing money, you're actually learning the skills to master it. And now you know where you are, what to do and how to level up. But mastering money is just the beginning. Now it's about using that mastery to design a life you are proud of. So here's your next move. Watch this next video. Money mistakes that can cost you millions. It'll show you exactly what smart earners still get wrong and how to avoid them. Click here to watch it next.









