Self Managed Super Fund
31 Jul 2015 · 2 min
2:00
A guide to using a self-managed super fund for property investment. Learn how to roll over funds, leverage property deals, and use tax benefits to maximize returns on your superannuation.
A guide to using a self-managed super fund for property investment. Learn how to roll over funds, leverage property deals, and use tax benefits to maximize returns on your superannuation.
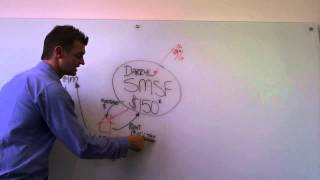
Okay, Darrell, now what I want to talk to you about is your self managed super funding. So what we do is we'd roll 150 grand from Rio Tinto into the Daryl self managed super fund and with that your employer is going to be putting their 9% or whatever they're putting through for your contributions on that monthly basis into the self managed super fund. So it's just think of it as a company in your name and it's got a bank account. That bank account has got 150 grand in cash in it. What would you do with $150,000 cash? Well, no doubt you'd probably look at property A with that the bank will lend you a self managed super fund, 80% of the value of the property. So if you want to buy a 500 grand property, they'll lend you 400 grand. What that means is you're going to put down 100 grand deposit, which you've got, you've got 150 grand cash. You use 100 grand of that to put down as the deposit. The rent for the investment property gets paid into your self owned super fund and it's got a 15% tax bracket on it, which is fantastic, a lot lower than what you're currently paying. And you've then also got the mortgage being paid by the self owned super fund. So the there's no money actually out of your pocket. It's all being paid by the super fund and all the rent comes in and all the mortgage expenses go out. Two ways to create wealth I discussed with you was leverage and other people's money. We're using other people's money here because you're only putting down 100 grand. But what you're doing is you're getting a $500,000 asset and that's leveraging it up. And what I mean by that is you're going to get a 10% gain, for example, on an investment property. That means you're going to get 10% on 500 grand, which will be a $50,000 return. Whereas if you've got a 10% gain on your current super, that's a 15 grand return. 50 grand versus 15 grand, huge difference there. The best part about this is with that self managed super fund and the property it actually owns is there's no capital gains tax on that property. If you sell it at retirement, for example, you buy it for 500 grand today, by the time you retire, it's worth a million dollars. With that million dollars, you made $500,000 in gain. The capital gain section at 500 grand is 0%, 0% capital gains tax on that investment property if you sell out of retirement. A really good strategy. Something where you can utilize your superannuation a lot better. I can help set that all up for you and get that up and running.