This is a YouTube video titled "The Power of Financial Coaching" containing a detailed monologue by Adam from Crown Money, addressing Daniel Morris. The content, created in October 2023, focuses on reviewing Daniel's financial progress over the past year, highlighting debt reduction, equity growth, savings rates, and the benefits of their financial coaching approach. The speaker explains the impact of compound interest, compares loan structures, and outlines steps toward financial security, aiming to motivate and inform the client about their financial achievements and future outlook.
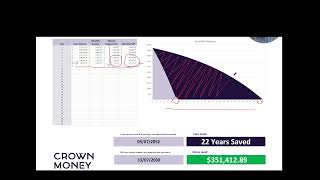
Hey Daniel Morris, Adam here from Crown Money. Hope you're well. I just wanted to touch base and run through your very first annual review with up here at 540,000 you've pushed that down to 471,447.63 at the end of June and that shows you still reduced by $61,969.54 in your very first year. Now that's a huge result especially when compared to what you've done previously. I mean look at this figure on the right hand side. That's how much you're reducing with your old lender. But look at this. Every time you're reducing your debt yout create equity in your properties, you've gone from creating $9,400 worth of equity to 61,000. It's mind blowing. You should be extremely proud of your efforts. And as mentioned, we just want this to continue so you guys can become debt free as quickly as possible. Now you can also see that your savings rate is tracked and measured every single month. This is such an important financial figure in all their lives. Look, a lot of people are simply focused on how much income they can bring into the household. Now that's definitely important. What's also important is how much we hold on to. And that's exactly what this is tracking. As you can see managers say 41% of your take home income. Did you know the average Australian these days are actually saving around 7% of their take home income? Now the average Crown client we're hovering around 20%. So you're more than double what the average Crown client's doing in your very first year. And and at this pace you are done and dusted by 13 July 2030 pretty much every single month which is reflected with your loan balance just trending straight down which is exactly what we want to see. Now the exciting stuff is this page out of debt rejections for you shows that you are done and dusted within basically six and a half years. Because you can see in year seven your balance is 29k. You're actually on track to pay 92 off that year. But let's call it seven years for argument's sakes. In seven years time you can own this property outright. And remember what we're doing here is taking advantage of compound interest. Now as you can see here, as your debt reduces the interest going to the bank reduces at a really rapid pace which means over the years the lender gets less and less interest off you and that means you're Actually paying more and more off the principal because that compound interest effect. So you're doing all you can. Your money's working for you now, not the banks. And this graph on the right hand side shows another story altogether. As you can see, you're going to be done before year eight kicks in versus what would have happened if you actually jumped on board a so called cheap interest rate lender instead of taking that leap of faith with ground. Well, guess what, that new lender, they would have given you that cheap 30 year interest loan, structure things incorrectly to keep you in debt for as long as possible to make money for their shareholders and you literally have 29 years left spinning the wheels on their terms because look how much reward you're getting out of it. You're actually on track to save yourself all this time. 22 years of interest versus that traditional 30 year mortgage, 22 years of loan repayments 22 years earlier, where all your income can go to yourself and you can do as you please with that loans, whether it be putting towards capping out your super, or putting towards investments, or helping out family, friends, or just enjoying your life a little bit more and doing what makes you happy. But not only on track to save 22 years, you're also on track to save $351,412.89 with the loan repayments interest you won't have to make to anybody. So instead of being done by 2052 exactly how the banks would have structured things, you're now on track to be done by 13th July 2030. Where do you sit on our 12 steps to financial security? Well, you've ticked off so many along the way in your very first year, you've got a 2K buffer tucked away. Step two is about having one month's expenses. Now one month's expenses for yourself is averaging out to be 8170, which you've well and surely got tucked away. From what I can tell, there's no external debts, which is a huge win. Let's keep it that way. So all your money is going towards the number one asset, which is your home. Step three or step four, I should say is all about having three months expenses tucked away at all times. Now as you can see, three months expenses for yourself is basically $25,000 there. And I'm very pleased to see well and surely got that tucked away. Which gives you some financial peace of mind because no matter what happens now, if your income is affected due to injury, illness, whatever it might be, you're always going to have at least three months expenses to fall back on so you can cover any financial crisis life throws away without the added financial stress. So huge win there.