Ask Chad | How To Become Debt FREE! | Live Call In Show to Answer All Your Questions!
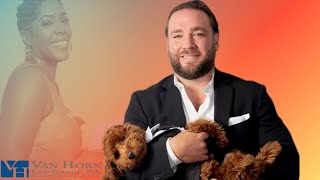
Bankruptcy attorney Chad Van Horn takes live calls from people asking how to get out of debt. He covers Chapter 7 bankruptcy, student loan discharge, credit card negotiation, and when to rent instead of own. He stresses that a clear plan, even if it involves bankruptcy, brings real relief.
Chapters
Dad, we going to answer all y'all questions on how to become debt-free. Everything okay, family? All right, listen, moderators, remember, no blocking. And if anybody ask you— uh-oh— if anybody ask you what What's going on up over here? Let them know. Everything's allegedly. Even my name's allegedly, but we ain't gonna have no issues today because, you know, we are doing a financial course today, okay? I do see the people here. So I do see YouTube and Facebook streaming live. Hi guys, hi, we're back for part 2. How you guys doing? We're good? Everything good, Jazzy Faye? You sure? Okay. We were having some technical issues, but that's okay. Jasmine's first day officially back in studio using our regular software. We had to reconnect everything, so just give us some time. You know, we did good for the live earlier today, and we're going to do just as great for the second live today. I told you guys that we would be back at 4 PM Eastern Standard Time, but it is 4:15, so forgive me, uh, with Chad, my bankruptcy attorney. Okay, he helps people to start over. Now.org. Okay, and so listen, without further ado, we're not gonna waste no more time. He's been waiting patiently backstage while we figure out all this technical stuff. Chad Van Horn, my Van Horn Law Group. What's up, brother?
I've been waiting all day for Tasha K. You know, Cinco de Mayo, normally people are drinking tequila, but I'm having wine tonight with you.
Listen, you gonna be drinking tequila later on today. I already know. I, I already know Fort Lauderdale is going to be lit.
Man, I, I went to lunch at the Mexican spot near me and they were already doing tequila shots. So, you know, Fort Liquordale is living up to its name today and we gotta work.
That sucks. That sucks. So listen, I'm excited that you are now trying to, um, move a lot of these fake financial gurus out of the way, like Dave Ramsey.
Oh, shots fired early. Did you know he filed bankruptcy?
He won't tell nobody that because he speaks against bankruptcy.
Yeah, he said nobody should file bankruptcy, but, but he filed bankruptcy, and that, that actually helped propel him into everything that he has today. So it's, it's, it's incredible that it's good for him but not good for everybody else out there, I guess.
So the debt snowball that he preaches about, I know it like the back of my hand. Start with the smallest debt first, get those out of the way, and then work your way up to the big debt.
That's right.
Right. He writes a book about it. He answers questions about it all day. But then to hear, because he's like, I just don't believe in bankruptcy. I don't like bankruptcy. But he wouldn't be able to do what he was doing if his debt wasn't forgiven. And I heard he was millions of dollars in debt.
He was. And the empire that he built today would have never happened without the bankruptcy code because he would have had millions of dollars worth of debt and judgments and everything that all the money that he would made to build this empire would have gone toward that debt instead of building the empire that he has today. So it is somewhat ironic.
Do you think he's being endorsed to not promote bankruptcy? Do you think he has some, I don't know, some endorsements from credit card companies?
And oh, I have, I have no doubt that he works with, uh, different companies out there. And, and I know at one point it was funny, his company was actually trying to sell bankruptcy leads to me. And one of their sales guys called me and I said, hold on, this is interesting. So the team that doesn't believe in bankruptcy is going to start selling bankruptcy leads. I don't know if that lasted long. I didn't agree to take those leads, but I know that they do generate leads and historically they have sold leads to different debt companies, debt consolidators and whatnot like that.
And through their email capture lists and things like that.
Correct. They have a huge following. Obviously they have the live radio. I believe his daughter actually has like a millennial version that they're doing. So they truly have an empire and it's worth millions, tens of millions, maybe hundreds of millions of dollars, uh, that he's made. And he does give some good advice. There's a lot of sound advice in there, but, but it— I don't really like hypocrites. So if something worked for you and then you're going to preach to everybody that, you know, it's the devil if they do it, That's not really for me.
And see, that's what I don't like. I don't like when people cheat the system and then don't tell how they got there. I hate that. And that's why I'm coming up with this show, a new show that's going to follow. It's going to be more so I want to gear it towards female entrepreneurs because I don't think we get enough shine, or just women that are just kind of doing their own thing, you know, working for self. Whether they have small companies or big companies, so they could kind of show us behind the scenes of everything that they struggle with or struggle with to get to where they are, or even going through what they're going through. I hate when people do not give us the blueprint to how they became millionaires and billionaires. I don't know, like, that, that rubs me the wrong way.
Me too. I hate the incomplete stories, the people that are like you know, I was— I, I built this all myself. I didn't need any help. First off, we all need help, right? And when you look into the, the background of really where people get to where they are, of course there's a lot of hard work that goes into this. I see how hard you work. I see you're grinding. So a lot of that goes into it. You got to get some breaks too. You got to have— you got to have a little bit of luck. Got to have a little bit of luck. And you just got to keep grinding and fighting and building and growing. And of course it helps when people that have made it share those secrets with you, like, hey, here are some little tips and tricks so that you might not have to grind as hard, or you may be able to avoid some pitfalls. But the people that just say, man, everything just worked out if you just put your head down and work hard— unfortunately, it doesn't always work out. And that's okay, as long as you just learn and keep growing and keep following through, then eventually you should hit that success.
Okay, so listen, me and Chad are going to be chit-chatting throughout the hour. I know this is a, is a different segment. It's a new segment. And so the phone lines are open, the StreamYard link is open. You do not have to show your face. You can just use your voice and you could ask Chad, the professional here, anything that you want to ask him. Okay. And so while we're waiting on you guys to get in here, I know people are, you know, Dave Ramsey, he does have it where people are used to calling in now, but over here You know, they be, they be afraid they're going to get exposed to something. It's like, no, I'm broke too. Okay, listen, we all, we all in debt. We're all in this together.
We've all been there, including me.
Listen, it's just, yeah, let me ask you something, Chad. So if you get in debt, do you file your own bankruptcy personally or do you have to hire another attorney?
So I've actually represented other bankruptcy attorneys. Um, they, they always say, uh, if, if, uh, you represent yourself, basically you have a fool for a client because there's too many pitfalls that you can get in if you're fighting your own battles. I, uh, I remember one case, uh, Judge Ray, he's retired now, great judge. Somebody represented themselves and it was an evidentiary hearing and they actually got on the stand and would answer a question and then got off the stand to ask the question and would run back and forth. To answer the questions. And the judge is like, all right, this needs to stop. You need an attorney. This, this is a mess. So generally speaking, uh, the smart attorneys are going to hire attorneys, and I certainly do that, uh, for if I ever need an attorney, I'm going to hire an attorney. I'm never going to represent myself. It's just a bad strategy.
All right, so here's the thing. I don't know if you heard, uh, today the, uh, I guess the Trump administration, uh, they are starting to garnish people who owe on federal student loans. It starts today.
Yep.
Have you been getting some calls on that?
I've already gotten calls on it. Uh, the garnishments have started to hit. And the, the problem with these federal garnishments too, it's not like a state court garnishment. I mean, they just take it directly out of the check, so they don't have to go to a judge, they don't have to do any of that. If you're in default for these federal student loans and you're getting some sort of, uh, government paycheck, Social Security, or, or a regular paycheck, they could just go to your job and start garnishing your check. And of course they know where you work because you're filing tax returns, so they have all the information. That's why they're one of the most dangerous, dangerous creditors you can have.
Let me ask you a question about college. Let's talk about it. I got a child right now that's about to go to school And I know I'm probably going to get dragged for this, but I said I'm not paying for it. I'm not paying for it. I just— I, I guess, you know, I went to college and I feel like if you're not becoming a lawyer, which they say in 10 years there won't be any lawyers because of AI. Do you believe that?
I, I think there still will be, uh, high-level lawyers. Um, for the lawyers that practice what we call door law, anything that walks in, they'll try to figure it out. I think they'll be replaced. But as far, as far as the problem solvers, the higher-end lawyers, they're, they're always going to be there, and they're, they're going to utilize AI as we started utilizing AI recently. And, um, but yeah, lawyers are still going to be around.
Okay. And the same in the medical field. They said that in the medical field, like You know, in 10 years you won't need an actual doctor. It'll be AI that's, that's doing surgeries and all of the complicated stuff.
You're, you're still going to have doctors, doctors there overseeing it, just from a liability standpoint. They're going to need that as well. So I believe that it's going to make things much better, much more efficient. Obviously, uh, AI is going to learn over the next 10 years I can't even imagine where it's gonna end up, but I, I don't think that it's, it's gonna completely replace, uh, the certain service, uh, industries for certain legal assistance. It, it probably will as far as document prep, getting documents, th— those type of basic things that you'll need to elevate your skillset from there and be able to utilize AI. Um, but I don't think it's gonna replace, uh, completely replace lawyers and doctors. I think it's just gonna make the, The good ones more efficient and better.
So with AI replacing a lot of jobs that people spent hundreds of thousands of dollars to get degrees on and they have interest, should the government offer some type of leniency for that, like a refund on the degree if the job is no longer available but they paid for this?
Well, what's crazy is if you think about it, the, the government and the schools are always behind, right? What I, I remember probably about 5 years ago, they were trying to retrain everybody to be coders, right? If you learn how to code, you're guaranteed a job. You learn how to code, you're going to be set for life. And guess what? AI is now replacing those coders. So people that spent money to go to school for coding are, are being replaced, especially again at the entry level. They're just being replaced by AI. And we've seen that time and time again. Should the schools or should the government step in? It's difficult because people are making choices. And I know these are 17, 18-year-olds that are making choices that are very expensive and can really have a very positive or negative impact on their life, but they are making the choice to go there and study this. So I think it's really encouraging more parents and students to look into really what is the future because we thought that the schools and the government historically had our backs, and they would say, okay, yeah, these are the right things to do. And just everything has changed in the last 20, 20-plus years.
Okay, okay. So we do have a few questions in the chat and things like that. I think, uh, YouTube has been having an issue today with all of the live streams, like, because we went live earlier today and they said that YouTube— a lot of the other streamers that they were in, their lives were getting disconnected. So we're being told here that this live keeps disconnecting, but it comes back. And it picks up, but it will process. Okay. Um, and so hold on for a second. Um, because we got a lot of questions in the chat. Oh my gosh. Oh my gosh. Okay.
Hopefully all appropriate. My wife's watching, so I hope they're all appropriate.
They're appropriate. They're appropriate.
No chatty daddy questions this time.
They, they are appropriate. So they said, I heard student loans can't be included in bankruptcy. Is that still true?
That actually has really shifted over the last few years. Uh, the Department of Justice and, and the Department of Education have worked together to make it easier to discharge student loans in bankruptcy. So if you've been out of school for a while, if you tried to pay back your student loans and you're still struggling and you don't really have the income and you're not going to have the future income to pay it back, it might be a good time to revisit whether those student loans are dischargeable. They're called SLAPs, or Student Loan Adversary Proceedings. There's a lot of information— we put a lot of information out there as well, because historically they have been non-dischargeable and don't even try to discharge it. But now that's really changing.
Okay. Um, okay. So that's— I'm glad you covered that. Somebody asked, what about over $25K credit card debt? Any suggestions to you, Chad? Remember, the link is open, guys, so you guys can come on and ask questions yourself, or you could put them in the chat and I'll read them. Okay. So he's here to ask— answer any questions you got about becoming debt-free. So what about $25K credit? Card debt. Any suggestions?
Yeah, so $25,000 in credit card debt, obviously it's all relative. It's going to be high interest, so it really depends on what your income is. So I always say that the— my— one of my rules is if your income is less than your debt, so if your, if your annual income was $25,000 or less, you definitely should seek, uh, for a Chapter 7 bankruptcy. And then it, it's relative, uh, the more income you have that you could put towards that debt. For about $25,000, you're going to need to be able to at least put together about $1,800 per month toward the debt alone. If you can do that, there might be a way to negotiate or settle the debt, and that would just be contacting all of your creditors, asking them if you can get on a payment plan where they'll reduce the interest rate to 0%. It may close the card, but at least you won't be paying that 29% interest Obviously, if you can't make those payments, then debt negotiation comes into play where you can just stop paying the credit cards altogether and then try to renegotiate terms that way. And then finally, then bankruptcy could be an option for that amount as well.
Okay. If you want to talk to Chad personally, visit startovernow.org. We had a banner, but with the new software, we got to put that banner in. Do you have the banner? The startovernow.org?
Look at that.
Yeah, there we go. There we go. Now we're in business. Wow. Producer Productions on my news. We do have somebody waiting backstage to ask you a question. We also have questions in the chat that I'm going to continue to read. We're here to ask Chad, not chat, Chad, on how to become debt-free. Okay. What's the name? What's it? Monique. All right, Monique, how you doing? Hi. Hi. Can you hear me? Yes.
Hi.
Hey, can you turn us down in the background? Sure. Thank you. Remember guys, the link is open for you guys to ask Chad anything. We'll just bring your voices up so your faces don't have to be shown, and you can ask any question that you want to ask without being judged. Okay, so Chad is here and he done seen it all. Okay, um, you're welcome, Fearless Love. She says thanks, TK, for caring about our people. This is awesome. Anytime. Yes, anytime. You should be going to Chad. He do all the work, you know. Monique?
Yes?
What's your question for Chad? Where you calling from, first off?
Um, I'm calling from Cleveland, Ohio.
Okay, shout out to Cleveland. Which— you have a question for Chad?
Yes. Um, I'm starting up my LLC, and I do have a bankruptcy from 2016, and I would like to know when would that come off? It's a Chapter 7.
That's a great question. Shout out to Cleveland. I have some family friends there. I'm from Pittsburgh, so I can't shout them out that much. But, um, the good news is you're, you're about 1 year away from it falling off. So a Chapter 7 is on your credit for 10 years, so you're only 1 year away. You, you've made it. Chapter 13's on your credit for 7 years. So, uh, congratulations on your new LLC. I hope it's successful. And at this point, it really should not be impacting your credit that much other than just showing up on your credit report. Your credit should already be back by now.
Okay, Monique, did you get that? I don't think— I mean, I filed bankruptcy, this is my second time. It just never stopped me from starting a business. Is there a particular reason why you're asking him when it will fall off?
Yes, I— it is coming up on my hard credit report.
Okay. It's hard to hear you, Monique. I think you got the background on and we're hearing us talk to you.
Oh yes, yes, just for a moment.
Thank you.
Thank you.
I am so sorry.
It's okay, it's okay, Chad. You got a lot of questions. People are saying they're trying to get on but it won't let them get on the link. Are we dropping the link, guys? The link is pinned in the chat. Also put your questions in the chat as well, okay? We're here to ask Chad how to become debt-free, okay? Don't be scared, don't be scared. I had to ask him How to become debt-free. It's a lot of debt.
That's right, there's a lot of, a lot of debt out there. But yeah, Monique, you, you, it should be falling off, uh, next year. But, but as Tasha said, it really shouldn't impact you in any way in your business and opening the business, any, even in getting credit at this point. If you needed secured credit, mortgages, all of that, that all should be available to you as long as your financial profile and everything is reporting correctly.
Thank you, Chad. Thank you, Tasha.
You're welcome.
Good luck with your business.
Thank you.
Anytime. Dang, I should have kept Monique here to ask her some more questions about her bankruptcy and how was that, her experience. Is Monique still there? Bring Monique. Yes, you know, people be afraid to file bankruptcy. How was your bankruptcy experience? Did you file a Chapter 7?
Um, yes, Tasha, 3 times.
Oh damn. Okay. And I guess each experience was amazing.
Um, yes, it was. Um, I really never had a problem getting anything after any of my bankruptcies, but I'm older and mature now and I know how important credit is now. So, um, um, I should have learned when I was younger, but you know, it is what it is, and I have a chance to correct and catch up with 2025.
Do you own a house and a car? Do you own a house?
I do not own a house or a car. I have a 2008 Ford Focus.
Okay, okay, I like her. She's at the— because I was like, where are we going with this? Okay, cool. But your experience though Would anybody with any type of debt, would you recommend that they file bankruptcy to start over? Because sometimes, you know, it's too much to pay back. And so was it a big relief for you when you filed?
Yes, it was a big, I would say, gorilla off of my back, you know, Tasha. And, um, as of now, I'm trying to coerce a family member to do it, but they're like apprehensive. And I think it's because of the credit. Um, you know, it being on the credit for so long, so, and, and they're in there, you know, between 25 and 35. So it's just, you know, um, teaching the, the millennials or whatever you call them, children. And I have one, and, uh, you know, how to utilize So you won't be stressed out trying to, you know, if you make a mistake or anything, it's fine. Pay, get a lawyer, and have your debt forgiven.
Okay. Yeah. Okay.
And real, real quick, Monique, uh, I'd be happy to speak to that family member, but we're seeing our clients 12 to 18 months after filing get back into a 700 credit score. So, uh, I would ask that family member, what is your credit score right now? And unfortunately, most of the, most of the people that are calling me, their credit score is already 400, 500. I even had one client that came in, it's— their credit was so bad it said N/A. They wouldn't even give them a score. So if your credit is already struggling, sometimes the best thing you could do for your credit is file Chapter 7 and then start to rebuild.
All right, so did you hear that, Mona?
Thank you.
You're welcome.
Thank you. Thank you. Um, anytime you need any questions.
Anytime. Thank you. Thank you, Monique. I appreciate it, guys. Uh, please, uh, visit startovernow.org if you want to, uh, become debt-free. Like, as simple as that. You get to talk to Chad personally. Um, I'm gonna be honest with you. I never had a 700 credit score until after I filed my first bankruptcy.
And that's—
I unfortunately was the victim of, you know, parents using credit credit scores. And then, you know, your original credit score doesn't start at 700. I think everybody starts at around a 500, if I'm not mistaken, when you turn— if I'm not mistaken, when you turn 18, correct?
Yep. And, and then, and then there are some tips that, uh, if you get put on as authorized users, you can have that whole credit history of the authorized user. My mom actually did that for me, and it helped me build credit faster, which was great. Until I abused it and then got hit with all that interest, and I had to figure out a way to pay it off. Um, but luckily, you became a bankruptcy lawyer, man. And then this is way before I knew anything about bankruptcy. This is when I was like 19, 20, and I just thought that credit card, just— I never had to pay it, just keep going. Um, but, but luckily I got, got another job, was able to pay it off. But, uh, yeah, I remember those days for sure.
My mom made me an authorized user too, on the light bill, on the water bill, on the, on the phone phone bill, and all of that was on my credit report. And, um, I remember when I tried to go get lights on my first apartment turned on in my apartment, they told me that I had to pay the $700 bill, okay, um, or I had to file a police report on my mom.
So what'd you do?
I put it in bankruptcy. There you go. I put it in. I, I, me having to file bankruptcy so early is crazy. It wasn't mostly my debt, it was debt that was occurring but from my mom. Like, you know, the only debt that I ever paid was like a, I think it was like a $15,000 student loan. That's the only thing I paid. And then after that I filed bankruptcy. And I remember my bankruptcy lawyer was like, we can go get that payment back. And I was just like, don't even worry about it, like for real. Because it was like if I paid anything off within the last 90 days, they could, um I guess the creditor has to refund me the money or something.
I, I had a client recently come to me. Her dad is suing her. Uh, she's, she just graduated from NYU, and he wanted to get off the loans because he co-signed for all the loans. And he's co— he is suing her for fraud, saying that he didn't sign for those loans, because that's the only way that he could get off those loans, if he says it's fraud. And So I had to explain, I'm like, you know, this at this amount, because NYU is not cheap, I mean, this is six figures of debt. I mean, this is criminal if this is proven one way or the other. Either the daughter committed fraud by forging the signature, or the dad's committing fraud by suing her for fraud to get off these student loans. So this is a complete mess. So I'm hopeful I can talk down the dad because I think he got some really bad advice, uh, probably from the lenders actually, that said Well, if you didn't sign these loans, you can get off them, but you know, you have to sue your daughter for fraud.
That's, that's, that's a shame. So is the daughter filing bankruptcy so he can't sue shit?
Potentially. We're working, we're working, we're working on our options.
Uh, I try to tell people, like, there's a blogger friend of mine out here— well, she no friend, she's a colleague— but, um, getting sued by Megan Thee Stallion, and I was just like, file bankruptcy, she can't sue you. Like, the litigation stops. And she's like, well, I don't have any debt. I'm like, the debt incurred from the lawsuit, it literally does— like, what this is gonna cost, it will stop it. You ain't got to worry about fighting her. There's a mosquito in this room that's eating good. I'm sorry, but yes.
No, it's, it's a powerful thing. A lot of people don't realize that to file bankruptcy, you don't have to have a judgment against you. You just have to have a claim, somebody that, that could sue you or is suing you. and that'll stop the litigation altogether. Bring it into the bankruptcy court, and that's where it can get resolved, right?
Exactly. That's what I said. File bankruptcy on Megan Thee Stallion, include the claim, lawsuit is done. She can't come do nothing.
Oh man, you should— you should have got your law degree.
I am. Shayna. Shayna's here to ask you a question, uh, Chad. Shayna, where you calling from? Shayna, unmute yourself. Shayna, go to the next person. William, where you calling from?
South side of Atlanta.
The south side of Atlanta?
Orlando.
Orlando. Okay, it's hard to hear you. Can you speak up a little bit?
South side of Atlanta.
Oh, he said south side of Atlanta. Oh, my bad. Okay. Yeah, I thought he's— I was like, wait a minute. Okay. I heard the accent too. So that was the thing, you know, he's Atlanta. Uh, what's your question? Uh, William?
Um, just got a lot of debt, school debt, unsubsidized, and I'm just, you know, unsure how to go about, you know, trying to figure this situation out because like the previous lady said, you know, a little bit apprehensive. But I'm just trying to get things right because I clearly made a mistake and just want to get the stress off my back, you know.
Yes, sir. Do you mind if I ask you a couple questions?
Yeah, go ahead.
All right, so as far as the federal student loan debt, that unsubsidized debt, how much do you have?
Unsubsidized is about $15,000. $16,000 and subsidized. Yeah, the, um, the, um, regular student loan is like $60,000.
Okay, so about $75,000 combined. Do you have any other debt?
Yes, it's probably about, uh, $35,000.
Okay, that totals up, so we're probably over $100,000 now. And as far, as far as income, what, what, what's your annual income approximately?
Uh, I would say about close to $70,000.
All right, $70,000. And, uh, household size, you have any kids? Married?
Not married. One kid. Yeah, one kid.
Yeah. So with those numbers, man, I'm talking to a bankruptcy attorney in Atlanta. You're surrounded by a lot of good ones up there, um, because that debt is just too much. When did you attend school? What year did you graduate?
Uh, 2017.
Okay, so about 8 years ago. So I would talk to a bankruptcy attorney, um, because that unsecured debt most likely can go. And I would also talk to them about a potential, uh, student loan adversary proceeding to see if, uh, you can discharge the student loans. And the good thing about the student loan adversary proceeding is sometimes you don't discharge all of it, but sometimes you get a partial discharge. They'll do 50%, 75%. So I think it's at least worth a phone call. I'm not telling you 100% should do it because obviously you need somebody to go through all the details, but it's definitely worth doing a free consultation. And the good thing is our bankruptcy attorneys, we all do free consultations for people, and usually 15-20 minutes, you'll, you'll have a good feel for whether that's the best option for you or not.
StartOverNow.org, William. StartOverNow.org. Uh, they will set you up with a bankruptcy attorney. You don't have to leave your house and they'll do everything from your house. So go to startovernow.org. Uh, within Chad's network, you'll be pointed to a bankruptcy attorney that'll give you a free consultation and they'll get you set up. You don't sound too happy. I wouldn't be happy either with that type of debt. That's why I'm not paying for my daughter's school.
Yeah, I'm definitely not happy.
No, man, life's too short. Life's too short to be stressed over this stuff, man. There are definitely options out there. So, uh, let's just get it fixed now. Let's, let's not let that hold you up any, any longer.
All right, so listen, call us back when you file that initial filing to start your process to becoming debt-free. Okay?
Okay, I will.
Thank you.
All right, startovernow.org, and you'll be connected to one of Chad's lawyers in his network.
All right, good luck, brother.
All right, thanks, Chad.
We got to get you trained up so you could just run this by yourself.
I know, I gotta get the training wheels off. I think, I think we'll get there though.
Okay, we're gonna give you 60 days.
60 days, done.
60 days, Jazzy Faye will be running the live and you'll be here answering questions from the winos.
That's all I need.
Yeah, you wrote a book too.
Two books now, I'm working on my third.
I need to get those books. I got one, I believe it's at, it's at my house.
I think so.
I need to get the other two books from you. I'll see you this weekend if I can. If you're going to be in the office on Saturday, I'll stop by the office. I'll grab those books so that we can talk about those books and people can order those books because you put— it's a lot of knowledge you dropped in those books.
Absolutely.
Yeah.
And, and, uh, especially my favorite's The Debt Life, where we talk about different success stories of people that have gone through bankruptcy or debt issues and have come out the other side. I'm actually working on your chapter for my updated book now, Tasha.
So, uh-uh, not— I get my own chapter. Hey, they're teaching, they're teaching about my lawsuit in law schools. Oh, I've been asked to come speak.
Oh, trust me, I've heard. I've had, I've had some interns and law clerks come up to me, and, uh, because it's that, that season now, and they have so many questions because, uh, their bankruptcy professors were following the case as, as we went through it. Um, which, hey, I, I, I had— when we first met, I had no idea it was gonna end up here, but here we are.
No, it was funny because when we first met, you was like, you know you don't got to do this, right? You can go to Africa.
That is always a backup plan that I tell people, especially when they're stressed out, because, you know, I said, listen, they already set up in Africa, like, for real. Like, you was like, you know, you ain't got to pay this I think I said Jamaica too. I usually say Jamaica because Africa is a long way, but I got family in Africa.
Like, that's the thing, like, we— I'm over there, uh, 2, 3 times a year, so it's all good. We got Shayna next. Shayna, where you calling from?
Hey guys, sorry about that before.
Um, what's up?
I'm in Fort Lauderdale.
Oh my God, okay, Shayna, my neighbor. Broward County.
Yeah, so like, Tasha, I watch you just because, like, you know, when I want to be a little messy, but you drop gems too, like about law or even about health. So I know you're tapped in, you know, obviously your lawsuit, we know you beat that against some powerful people.
Yes.
Um, I don't really—
what's your question?
Yeah, I don't have student loans or anything. So I hope it's okay if I can ask some questions.
Anytime, any type of debt. Okay.
Okay. So basically, I study equity law. So I study like filing my own petitions and notices. And, um, you know what you might call it.
Let's see.
I wanted to know what, like, if you go into detail a little bit more about what roadblocks, Chad, you would encounter if you did take on your own case.
Oh, so we're going back to that represent yourself.
So you talking about for a bankruptcy? You trying to— or just represent yourself?
I mean, yeah, because it's pretty much the process of law, like, is more so what I'm asking him about. But yeah, he can touch on bankruptcy.
Okay. I just want to make sure it's got to do with becoming debt-free, like bankruptcy, because he does have an internship program and you are in Florida, and I'm sure he wouldn't mind, like, giving you information on that.
That's—
yes, just go to— go to— go check me out. If you Google Chad Van Horn, call the office. We'll set aside 30 minutes and, and I'll go through whatever you're working on and I'll give you whatever advice I can. How's that sound?
I mean, yeah, I was really just coming on here more so to like talk about law because that's like— the channel is not really about that. So I just popped on, I saw you guys, and I said, hey, let me just I don't know what things you don't want to touch on, you know. I'm kind of like just being careful with what I say, but you're good.
We just— today we're talking about becoming debt-free, and so maybe we can have another live stream about that. And so, but right now we just don't want to get off topic, that's all.
Okay, so let me—
we don't think that your question is a bad question or anything, it's just we're just trying to stay on topic, that's all.
Yeah, not like flagged. I don't want to get you guys flagged or anything.
No, no, you know, we'll get us flagged. It's all good. But listen, um, email me unwindwithtashak@gmail.com. I'll put you in contact with Chad, or you could just call the office directly, Chad Van Horn, and they'll set up a time for you. Okay.
Yeah. Can I ask you guys one other thing?
Sure.
So I'm pretty sure within the past few months You know, Trump had mentioned something about removing or kind of like revamping administrative court. So, you know, that's where we go to pay fees that keep us in debt, like traffic, parking, um, what other— like taxes, liens, all that stuff. So what are your thoughts on that?
So as far as administrative court, I mean, all of that is state-run. And, and, you know, we see the issues at the DMV where, um, people are scalping tickets to DMV. Did you see that, Tasha K?
I didn't see that. What happened?
So, so people were making reservations for the DMV and then selling them because it was impossible to get an appointment.
I lost my license 6 months ago. I still have yet to get into the office. Wow. To get a new license.
So, so the, the cities and the municipalities, uh, in the state are cracking down on that and making that a crime where you can't sell your DMV slots. So, so I, you know, obviously, uh, President Trump says a lot of things, um, but as far as the action, the action that's been happening locally, uh, is going to be your, your city, county, and state officials. Um, yeah, the, the administrative fees eventually hopefully will start coming down, but I'm not seeing that happen, uh, right now. So Um, hopefully in the future, but right now everything's just becoming more expensive, it seems like.
True. It would be a drastic change.
Okay, well, listen, we're gonna have that chat. I don't know if you like to talk politics, but maybe we can do like a dual show with you.
Yes, thank you guys.
I'll talk about anything. Thank you.
Thank you, Shayna. Okay, cool. Remember, guys, where chat is here to take all of your questions. Um, on whether or not you qualify to do bankruptcy, or he can offer you some solutions on how to become, uh, debt-free without having to file bankruptcy, because he does a lot of that as well too. He's written, uh, 3 books, um, on, uh, financial stability and things like that. And so yeah, I'm glad that we have him here, and we got to get him trained up so he could just run the live by himself on the channel and just, you know, drink some wine with y'all. Okay, so who Shay, we got another, uh, wino backstage. Shay, how you doing? Where you calling from? Hey, Miss Tasha and Mr. Chad, I'm calling from South Carolina. Shout out to South Carolina. What is your question for Mr. Chad today?
I just got a quick question about a car loan and bankruptcy.
I actually just officially sent all my paperwork to my lawyer, so I am filing a Chapter 7. Um, but I've heard that, um, you can get a car once you file bankruptcy, but you have to ask for permission from the court. I'm just wondering what kind of pushback would you potentially get from the court with that situation?
So believe it or not, it's a very easy, straightforward process, and there are companies that specialize in helping you get cars while you're going through bankruptcy. The only pushback that I've seen are when people are getting cars that are, let's just say, out of a normal price range. Like if you're going out there getting that Bugatti or Lamborghini or whatever that is, then you're going to get a little pushback. And we see a lot of that, unfortunately, in South Florida, where, you know, people become debt-free and all of a sudden they want to, um, you know, get a brand new, very expensive car. That's when you'll see the pushback. But if you're talking you need a car to get back and forth to work, a reliable vehicle, yeah, there won't be any issue, uh, getting that together as long as obviously you qualify financially, you have the income, um, because that's what, what they base it off of is your income. Because obviously your credit score is going to be recovering still.
Okay, gotcha, gotcha. That's it.
Thank you.
Yeah, good. Hey, good luck to you.
Thank you. All righty, she probably feeling good already, right? I know, the weight lifted on my shoulders.
The hardest thing for my clients, and they say it time and time again, is just making the phone call to come meet with me and then, and then making that happen. And then after that, you know, getting the documents together, getting filed get your discharge. That's all easy compared to that, just making that first phone call, man.
Let me tell you, did you know— you did know because you were over the bankruptcy— that I didn't make a car payment on my Chevy truck for 9 months?
I did not know that. How was it not repoed?
They did. They put an adversary in asking the court, could they come get in the truck? Susan had told me only pay secured. Debt, right? So the truck, in my— to my recollection, fell under unsecured, right? So I didn't pay it for 9 months, and they sent me a bill, but they couldn't add no interest. And so it was only for the $9,000 because the truck was $1,000 a month. So yes, and people was asking, how you get a truck payment for $1,000 a month? Well, I signed a 7-year loan on the truck and it was $70,000 and I pay $1,000 a month for 7 years.
That's, that's wild.
But we ended up paying it. I regretted making that, that $9,000 payment. It should have just let them come take it.
Sometimes that's, sometimes that's the best thing if you, especially if you're in a bad deal. I'm, I had a client today, they owed $50,000 on a 2014 Honda Civic.
Oh, what?
A Honda Civic, 2014, 11-year-old car. I said, how do you owe $50,000? And they just rolled bad loans into bad loans. I was like, we're getting rid of this car. So we're getting rid of that on a Chapter 7 real quick.
And a lot of people be upside down like that.
Oh, it's— the numbers are insane. That I see. Insane. I don't even know how the funding gets approved, honestly.
What I never understood— we got people waiting back— say, what I, what I never understood is that how you buy a car, they repo it, give it to somebody else, but you still owe money on that when they're charging somebody else on that car as well too.
Yeah, because what they do is they take it to auction and they, and they, they, they crush you in fees. They auction it off. Whatever they get from the auction, they apply towards that balance, and you still owe the remaining. So yeah, you— and then, and then the dealer, whoever sells the car again, it, it, it's, it's a racket.
They probably got about 15 people paying on that one car.
Yep. And that's what they want.
That's crazy. That's crazy to me. Crazy. Who, who's Zanetta? Zanetta, how you doing? Where you calling from, Zanetta? Hello, can y'all hear me? Yes, how you doing? I'm good, how y'all doing? Good. Where you calling from? I just relocated to Tennessee. Shout out to Tennessee. Yeah, what's your question for Chad? Were you asking Chad? He's Daddy today. Chad, so I got a question. I have a credit card I'm trying to— the payment's just killing me right now, and it's like about, what, $13,000? And I was wondering, should I just let it go to just stop paying it, or what you think? Because I'm not making enough for it right now. I just started a new job, so I'm trying to see what should I do.
Yeah, so, so the first step would be to call the credit card company and let them know, hey, what do you always say, Tasha? I don't have it.
I ain't got it.
I ain't got it. I ain't got it.
Yeah, call the credit—
call the credit card company first and let them know, like, Hey, I just don't have the money. I just started a new job. Um, is there some sort of forbearance program, or is there some program that I can get on? Um, and then they may try to put you through to some different, um, agencies to help, help you with that. If you truly just can't pay it and you know you can't pay it, then, then you— yeah, you can't pay it, then don't pay it. And then once you get your money together and your, and your, and your money, money right, then reach out to whoever the creditor is. It could be a collection agency, could be a lawyer at that point, and then negotiate a settlement with them. Um, we do it every day. Individuals, uh, can do it as well. And the good, the good part about this is whenever you default and you renegotiate the payment, there's going to be a beginning and an end to it with no interest. So the negotiated payment plans don't have interest, which a lot of people don't realize. and then once you settle that account, it'll take about 12 to 18 months to rebuild your credit. And, and that is possible. But again, if you're struggling— and I see people all the time that are struggling to pay, pay rent, but they're still paying their credit card bill, struggling to eat, still paying their credit card bill, um, you know, prioritize your expenses. And if you can't afford to pay the credit card, it will be okay. I promise you, it'll, it'll still work out.
The girl, let that damn credit card go. Well, look, I hear you talking. Um, so what if— okay, so I'm trying to get another place within like another year. How bad would that affect my credit, or would you— what would you think about that? I'm at like a 700-something right now. Just a higher deposit. Okay.
Yeah, it's going to be a hard— you're going to fall into— you're going to fall into the 6s. Um, but, but as long as you don't have an eviction on the record and you show that you have the income to make the payments, it'll still be relatively easy to, uh, to get another place.
Thank you so much. Okay, appreciate it. You can even get a house too, girl. Ain't nobody gonna be sending that credit card. All right, thank y'all. All right, no problem. Visit startovernow.org to talk to a bankruptcy attorney that is connected to Chad's network. Um, if you're in Florida or Pennsylvania, you will be routed to his office personally. Um, if you're anywhere else, you're going to be routed to one of his colleagues in his network. And so, Chad, they're waiting backstage for you. Elaine, where you calling from? Elaine, don't get tired now, Chad. Uh-uh.
Uh-uh.
I'm ready.
I'm ready. Elaine, where you calling from?
Uh, Delaware.
Delaware. Shout out to Delaware. Okay, so what's your question for Chad?
Um, I called your company when Tasha first put it out there, and I was denied automatically. Um, didn't even give me suggestions or anything. And I'm not downing anybody, I'm just— I've been— I'm, I'm desperate right now.
Okay, so, um, I was going through a book real quick and I want to answer your question, and I apologize for that. Um, they should be referring everybody to startovernow.org, but, but I'm certainly happy to—
No, no, that's, that's, that's where I went. That's where I went. I got the appointment and everything. And I spoke to a lawyer, and I told him I was desperate. I was getting ready to lose my home. So the deal is, it's me and my ex-husband's home. He lives there. I live in Delaware. They're not getting us for nonpayment of mortgage because he pays the mortgage. They said we took a credit line. You know when a mortgage company keeps changing mortgage companies all the time? So this last mortgage company said, oh, y'all guys took a line of credit like 20 years ago, and they said we want this money now.
Wow.
So, and how much is it?
They said $115,000. And we have no clue. We can't find no paperwork, no nothing. So the house went to foreclosure. He filed for a bankruptcy to stop it. And hopefully they— it's like they're not trying to make an agreement with us to keep the home. So we're trying to keep the home for our kids. They're grown, but, you know, something for them to fall back on. So he— your lawyer said he didn't want to deal with it because I, I didn't live in the home.
Well, and you're in Delaware. Oh, oh, you mean some— a Delaware attorney?
Okay. But then I said I had, I had a whole lot of stuff going on. Like, my credit score is good because I pride myself on that. It's 720, but I pay minimum. I'm, I'm paying minimum of everything. I had to take loans out I care for my mother, so I had to take loans out to get a house done over because it had to be homebound accessible and she didn't have it. So it's like my money, I have— I owe like $35,000 in taxes and that's because they said I get a pension and I just started getting Social Security. So they said that I had to take out $800 a month in order for me not to be able to pay taxes in Delaware. But I can't live if I give them $800 for taxes, right? So I owe taxes, then I take loan out to pay this and pay that, but the loans have become so overbearing that I have no money to live off of, basically. I have money just to pay the basic necessary needs. And my credit card debt is like about $35,000, $40,000. That's including loans. My school loan— I have a bachelor's in human services and a master's in public administration. And I've never had a job that paid that kind of money. So I owe $98,000 in school loans and I'm just like—
I can hear it in your voice for sure. And there are options.
I've tried everything to try to, but doing minimum payment, you know, I can't never get a credit card. And because I don't have cash, I have to keep using the credit card.
No, it's—
and I'm—
it, it's a, it's a, it's a downward cycle spiral for sure. Uh, it sounds like actually you may be a Chapter 13 candidate. So if the original attorney, uh, didn't find you a place, maybe email Tasha directly, and then, um, what we can do is we can find somebody else that maybe specializes in Chapter 13 because you definitely have a unique situation, especially with the property. And everything else you have going on. Um, but there, there is an answer, so keep fighting. And I know you got a family that's relying on you to do it. There are options, and it does sound like a Chapter 13 may fix it. Um, but we want to make sure that we match you up with the right person to, to help you through it. I wish I was up in Delaware because I definitely would, would do it. Never been to Delaware, um, but maybe one day.
Yeah, yeah. So what we'll, what we'll do, um, is if you email me personally on whywithtashk@gmail.com, I'm gonna get on on the phone with our colleague, our mutual colleague Phil, and we're going to personally find an attorney that's going to take on your unique case. A lot of them are lazy. Now, I'm going to be honest with you. They'll see a case like this and they'll be like, oh, this is too much. And then with a case like yours, it will cost just a little bit of money for you to be able to put a Chapter 13 in place. So you will have to make a payment plan, but everything will be based off of what your income is and what you can afford. Does that make sense?
Yeah.
Some of it you may be able to, you know, I don't know, your situation is definitely unique. So just go ahead and email me and I promise you I'm going to get you with Phil, our colleague, and he's going to find you an attorney that's going to take on your case. That's what they do at startovernow.org. So I'm sorry that you were transferred to a lawyer in our network that did that because that shouldn't have happened. And please give me that lawyer's number and name. So that we can make sure he doesn't get any more, uh, of the clients that we have over here. Okay?
Yes.
Thank you. Okay. All right, we're gonna report back on her case. That's bullshit, child. Like, what— why do people—
you know, and lawyers are humans too. I know we don't act— act it sometimes, but yeah, you know, if you catch a lawyer on the wrong day or after court, after like after some of the hearings I was in with you, if I was doing a consultation, maybe I wasn't the nicest person. And I try because I realize that everybody that's calling me is usually in a desperate situation. So I try to really just shake it off completely. And sometimes we just don't know the answer. And I'm really good at telling people, look, I don't know. I'm going to go find out though, and then we'll work through it together. But some lawyers, when they don't know, they get nervous and they just say like, there's no options, but there's always an option.
Yeah. Well, they shouldn't even be getting to any of our leads. And so I'm going to make sure that lawyer comes off the list. I'm not playing about the winos, like for real. We do this for real. This is something that I believe in, that I personally have done. I will do it again if I have to and won't lose no damn sleep. I promise you. I promise you that on everything, okay? And so don't you worry. We'll get those tears dried up soon. And I'm sorry that you went through that. So, and thank you. StartOverNow.org, okay? So if you have a bad experience, please let us know. Okay, please. All right, who's next? Jasmine? Faye? Faye, where you calling from? Faye?
Hi, um, can you hear me?
Yes.
Oh, okay, great. Um, I'm calling from New Jersey.
Okay, shout out to Jersey. What's your question for Chad?
Um, okay, so, um, I'm happy— I'm actually happy that you're doing this, um, because I've had so much anxiety over this, so I almost clicked off, but I forced myself to come back on. So Latasha is looking out for the people. So yeah, so in my situation, I do need to file some type of bankruptcy, but I'm more concerned because I'm in over my head, but I'm more concerned about the 3 properties that I own. How does that work with bankruptcy?
Yeah, absolutely. So each state has their own exemptions in bankruptcy, meaning meaning things that you can keep while you're going through a Chapter 7 bankruptcy. If you're above those exemptions, you either have to pay it back or they'll sell those assets. It sounds like your situation would be a Chapter 13 as well, where in a Chapter 13 you get to keep all of your assets and then you renegotiate a payment plan over a 3 to 5 year period, and at the end, whatever's left over is discharged. So, um, make sure whatever attorney you end up speaking with You obviously let them know about all the properties. It would really help if you had an appraisal or a true valuation of the properties and obviously how much is owed, and then they could figure out what the best plan and what the monthly payment plan would be in the Chapter 13.
Okay, that's great advice and I appreciate it. And this was just like confirmation that I got to stop playing and like handle my business. So thank you, Latasha.
Yes, you do. You gotta look at the bank account every day.
That's hard.
Look at it, examine it, go through it. That's the only way you're gonna get over this mountain, okay? I tell everybody that all the time. And visit startovernow.org if you are in the Florida and Pennsylvania area. You will be automatically transferred to Chad, or if you're out of that area, you will be transferred to a lawyer within his network. And like I said, if you have a bad experience, you please let us know who that lawyer is and they get kicked out of the network.
Okay, I'll do that. Thank you so much.
And when you have a good experience, come in here and tell us about it too. Okay, come on, come on, we got a lot of good lawyers out here.
We do, we do. But the lazy ones, we need to know because they ain't gonna give all lawyers a bad name.
Like, for real, I'm here for it.
Like, I got good, good defamation attorneys now. Great defamation attorneys. They wear all the shit. Okay. Yes.
All right, that's good to know. And I like how you stood up for the young lady that called back, that you actually really care about us.
Yes.
So I like that. So thank you guys. Bye.
Oh, anytime, anytime. Thank you. Come on up in here. You got a lot of people waiting backstage, Chad. So I'm gonna come train you and I'm gonna walk you through this, and you're gonna—
we're gonna make it happen.
Okay, we can even bring one of your other lawyer buddies on if you want. And y'all can chit chat and take questions. Okay.
All right. I love it.
The chat is yours. That's what it's here for. Okay. All right. Who's next, Jasmine? Renee, how you doing, Renee? Where you calling from?
I'm well.
I'm calling from Houston, Texas.
Shout out to Houston. What's your question, baby, for chat?
Uh, I've got a couple, so stop me when I, when I take up my, my 5 minutes. Uh, my first question is, can you keep your home in, uh, bankruptcy?
Great question. And actually, Texas has one of the best exemptions. Like Florida, you have an unlimited homestead. So, uh, the general answer is absolutely, you can keep your home.
Okay. And next, can I include IRS tax debt in a bankruptcy?
So IRS tax debt, if it's generally speaking older than 3 tax years, you can discharge IRS tax debt. And I know some people that have done that recently.
Okay, awesome. And for, uh, is charged-off debt—
that's our—
the account has already closed—
is—
can you also include that in a bankruptcy?
You're actually required to, to include charged-off debt. So charged-off is just an accounting term that the banks use basically to take that loss in this, uh, calendar year. So it really doesn't impact the status of the debt. Toward you. I know that shows up on your credit report, but it really doesn't impact it at all. And yes, it is, it should be, and it must be included in the bankruptcy.
Okay. And is my 401(k) considered disposable income or accessible?
So your 401(k) is exempt. If you've taken out of your 401(k) in the last few months, though, that is considered income. So they can look at that. If it's just sitting in your 401(k), it will not be touched by creditors.
All right, and this is my last question. Do banks close your checking account for filing bankruptcy?
That's a great question as well. In general, no, they do not. But be careful, if you owe a bank money and you bank with them, they have the right to offset, meaning they can freeze your bank account, take the money out without you, without you, uh, agreeing to it. So If you are going to default on a credit card with a bank that you keep your money, take your money out before you default on that credit card. But they will not, generally speaking, shut down your bank account.
So if I have a Chase credit card that I'm defaulting on and I also bank with Chase, you're saying maybe I need to switch banks?
Well, at least while you're going through this, take the money out of Chase. You can leave that account open, maybe leave $5 in there. But just take the money out until— and put it into another bank account until you get through it. And then once you're through the bankruptcy, if you want to start banking with Chase again, you absolutely can.
Okay. All right. Thank you guys so much for this. I already did the inquiry and never responded back. So this is exactly what I needed. I'll be responding back to the company who reached out to me. Many thanks to you guys for doing this.
StartOverNow.org. Let's go, girl. Let's get that. Let's get that debt gone.
I am.
Bye, guys. That's funny. That's funny because like I had my IRS debt included in my bankruptcy and, you know, I took my money out of the bank. That's why I was only showing that I had $92 in my account when I filed, man. I reported it, but I was just like, they was trying to garnish me.
Yeah, you got— I mean, you got to look out for yourself, especially if you got to pay rent, you got to pay your car, you got to pay all these things. And then if you're Once your money's frozen, it takes forever to get it unfrozen.
So, man, they was on The Breakfast Club talking about Tasha K filed bankruptcy, said she only had $92 for her name. Now I was like, now y'all know that's some fucking lie, but it's cool. Look, we gotta do what we gotta do, and we here now. All right, cool, cool. Cheryl, Cheryl, where you calling from? Cheryl, I'm gonna have you do the next thing. Where you calling from, Cheryl? I'm gonna have you do it, Chad. Shout out from Atlanta. What's your question for Chad today?
Chad, listening to the other callers, mine might not be as urgent, but, um, um, senior citizen, 66 years old. I have my biggest, uh, expense is my mortgage. And I want to know, how can I get rid of my mortgage?
Yeah, that, that's— I'm, I'm seeing a, a lot of, uh, senior citizens, especially people on fixed incomes, that are struggling recently because every— everything costs more, right? Everything.
Yes.
And here's the thing, my, my house, I have a lot of equity. When I bought the house, it was about $140,000, and now it's valued at $350,000. So I want to know, should I sell since the craziness is happening in the market, you know, that, that, that the, you know, it may go down in value. I'm just trying to figure out what my move should be with all of the uncertainty that we facing right now with that, that man in office.
So no, I get it. How much, how much do you owe on those?
I need to know if there's something I owe on the mortgage. I think about $139,000. You know, after you— I've been in my house since 2016, and you know, uh, when you first starting, you paying most of it to, uh, interest. I try to make at least one additional payment each year, so that has helped me. But, uh, that mortgage is kicking my butt.
And what's up?
And it's a very affordable mortgage, so I'm thankful to God about that.
Yeah, so if it's affordable and it's still kicking your butt, what I would do if I were you is I'd cash out. I mean, the, the market is still relatively hot right now. You have a lot of equity, and then you've owned the property long enough where you're not going to get hit with income tax on the $250,000 as well. So I think it might be time to— let's cash out. And then if you're retired, that's your retirement there. And just have that money in a passive investment that's safe, because obviously there's a lot of unknowns right now. So the safer the better, and that way you won't have to worry about struggling to make that payment every month.
Okay. Well, thank you for that. That's what I've been debating on. But the thing of selling, I still will have to— I'll have to purchase somewhere to stay, you know, so I don't know, but I just thought I'd ask. And thank—
go ahead.
Yeah, you either, either purchase if you could find a place, uh, that you can maybe buy cash and it's paid off so you don't have the monthly payment, or maybe you just have the money in the bank account and you pay rent, and, and then you don't have to worry about all the things that come with home ownership, which I love home ownership, it's great, but you know, the roof needs done, the, the washer breaks you know, all that stuff that comes with it. Sometimes it's better to just have cash in the bank and rent, and it's a simpler life.
Tell me about it. Just had a roof put on. Uh, well, okay. Well, thank you all.
Thank you. No problem.
Thank you for your suggestion.
You're welcome. Good luck to you.
All right, Chad, you got the next one. You're gonna do the introduction. So who's backstage, Jasmine? You gonna say Rachel? Go ahead, Chad, do your thing.
Hey, Rachel, you there? And she's not gonna show up for me, Tasha. She's only gonna show up for you.
No, do it again. Do it again.
Rachel, are you with us?
Tell her to unmute herself.
Oh, you gotta unmute yourself, Rachel.
Rachel, answer the damn phone! Can she hear me?
Tasha, you set me up.
Unmute yourself. No, I'm saying Jasmine's like, she looking at her. Who's next after Rachel? Michaela, go ahead, Chad. Do Michaela.
I love the name Michaela. Michaela, you're with me, right?
Yes.
Hi.
And see, Michaela, where are you from?
Boston, Massachusetts.
Boston, Beantown.
You guys— hi, Latasha!
You guys gonna win the NBA championship again?
Ah, we'll see. I don't really follow sports, I'm not gonna hold you.
Okay, all right, well, well, that— oh, Rachel couldn't find her button, so we'll get back to her in a second. But Michaela, what's going on with you?
So long story short, over the past, uh, in 2025, so I'd say in the past, uh, 2 years, I've had some health issues and I also had, um, lost my job. So basically I was dealing with, uh, like unemployment, recovering from having surgery and then back on the prowl to, you know, finding a job. So I've had a lot of debt that has accrued. Um, I do have a bachelor's degree in psychology. I graduated in 2013, so that debt alone, I think I'm around $60,000. And then for my just personal debt with like credit cards and all that included, I'm at around $9,500. So I'm just, I'm overwhelmed, kind of like all the callers. I keep trying to figure out ways. I've been trying to do it for even before I lost my job. I'm just trying to find out what's the best thing for me to do in regard paying down my debt. And I know bankruptcy keeps being thrown around. That makes me nervous because it seems like it has a negative connotation to it. But for my particular case, I just don't know what to do.
Yeah, well, we'll walk you through that. First off, are you feeling better? Health's better? We're past that?
Yes. And I just found another job, so— and it's higher pay. So I guess good things come to those who wait. Yeah, that's great.
That's fantastic. And as far as income, what are we showing as income right now?
Zero.
I shouldn't laugh. It's not funny, but like zero, because I'm— I know it's not funny.
When you're starting the new job, how much are you going to make?
So about that, it's a process. This new job that I'm starting, I'll be working, doing events like weddings, doing venues, cooking. I switched careers too. So that's a big difference.
I was teaching.
Now I'm doing culinary, so I have to take kind of a pay difference. So I'm starting out in a whole new field. This job is seasonal, so it's starting in May, goes to October. 6 months on, 6 months off. But I'm still obviously going to look for a full-time job I can have all year round. So I can't give an accurate number yet.
Gotcha. So actually, I think you should do a bankruptcy consultation and not specifically for the $9,500. Obviously, that would be included. But I think you may be eligible for a student loan adversary proceeding, um, where you could potentially discharge or, or, or eliminate the student loan debt. And obviously, if, if that's possible, then I, I 100% would recommend a Chapter 7 bankruptcy on what you're telling me. Um, and it's good you're calling now because, um, when you file, if your, if your income is higher, then you're less likely to, uh, get that discharge, uh, of the student loans. So you What I recommend is there's a lot of good attorneys in Boston. Obviously, there's a ton of attorneys in Boston, so reach out. We got startovernow.org. We'll connect you with one that, that understands student loan adversary proceedings, and that may be the best option. If you can't get the discharge of the student loans with $9,500, I'd recommend doing a debt negotiation or working with the creditors to work out payment plans once you have steady income.
And because I have multiple credit cards, so would it look like me calling up each credit card, you know, bank, whatever lender, and saying, hey, I only have this amount, or, you know, like you said, negotiating-wise?
That's exactly it. You call each one and you say, look, I can't pay it. What options do you have for me? And then they'll go through a couple options. And if those still don't work, say, I still can't pay. Do you have any others? And if they say no, then you just stop paying and then wait a few months and then call back again and say, guys, I told you I couldn't pay, uh, what other options can we do? And, and then you just negotiate and don't over-promise. I mean, you only have so much money at the end of the day, and credit cards don't go to the front of the line. Um, you know, obviously your living expenses, your rent, your food, your basic needs have to be paid before the credit cards get paid.
I know, I'm always worried about my credit. Everybody seems like credit's hovered over your head, you know what I mean? So I try to always pay, put money towards my, you know, to what I owe.
I, I promise your credit will come back. Uh, unfortunately, people put their credit scores ahead of their health. I see it all the time. People are stressed out, they end up in the hospital with heart attacks. All because they have this debt that they're, that they're concerned about. And then, you know, if you don't have your health, who cares about your credit? So, um, so definitely, folks, just focus on, uh, focus on getting everything organized. Redo your budget. And if you have the money, definitely pay your credit cards. If you don't have it, don't pay. And then either look at that bankruptcy, which again, the bankruptcy is a quick process. Generally speaking, it's 3 to 4 months. Months, and then you rebuild your credit over that 12 to 18 month period, and you're rebuilding debt-free instead of trying to rebuild with, with this debt following you around.
Okay, I will look into that. I'll check out your website. Thank you guys so much for holding the space.
All right, no problem. Anytime. Thank you for calling. Chad, you got a lot of people waiting backstage, but you gotta go, don't you?
I, you know, I, I do have— we're running overtime. I do have, uh, more appointments that I, I got to get to, and I, I see people in my door like looking in. You want to take one more? We could do one more, I think.
But all right, let's do one more. But Chad will be here, uh, next Monday, uh, same time. You ready? You ready for your segment? You think maybe two more shows you're gonna be ready to unleash on your own? Absolutely.
Well, I'm learning from the best, so absolutely.
All right, cool, cool. Who's next, Jasmine? We'll let him do the honors. Who? Rachel is back. Go ahead, let's see if she can talk.
Rachel, are you there now?
I'm here, I'm here. Can you all hear me?
We can hear you perfectly. Thank you so much for calling in, Rachel. Where are you calling in from?
I'm calling you from Texas.
Oh, Texas. Okay, so what's going on, Rachel?
So I had a few questions, and you just can stop me if it's too much. The first one, you mentioned with this a particular caller about a student loan adversary. What does that entail?
So you got to file the bankruptcy first, and then once you file bankruptcy, you actually file a lawsuit against whoever, uh, whoever the credit card company or student loan company is. So if it's the Department of Education, it's Sallie Mae, whoever has a loan, you file a lawsuit against them basically saying this is causing an undue hardship on me and I, I can't pay it. And it's like any other lawsuit where you have to put on evidence on why you can't pay it. And then at the end of the day, uh, either agreement happens or you go in front of a judge and then the judge makes the decision.
Okay, my situation is this. I was laid off, um, about 2 years ago and haven't been able to find sustainable employment to take care of basic living expenses. I've blown through all of my savings, um, some of my, um, IRA as well. I took, I took money out of there, um, as well. It's still a little bit left in there, but with the two, two credit cards that I have, of course, one is American Express and I am in Texas, so there is, I guess, something about 3 years with cards here in Texas or something of that effect with them trying to force your hand with payment or whatever. But the other, again, like you said about the living expenses, having to do those first before paying the creditors. So I'm just wondering here in Texas, what other legal remedies are there?
Um, so I'm not licensed in Texas, so I can't give you exact details on Texas law. Uh, bankruptcy is federal law, so it's pretty much the same state to state. The only difference are with the exemptions. Um, so it sounds, it sounds to me like it'd be worth having a phone call with a Texas bankruptcy attorney just so you'll understand whether that is an option or whether that is is the best option. And most bankruptcy attorneys like me, we don't just do bankruptcy. So if it's, uh, litigating with American Express, if it's negotiating with them, whatever the options are, usually the bankruptcy attorneys will know the other options as well. So I would, uh, I would set up a free consult just so you can get a customized, um, and you can, you can have somebody that actually knows Texas law, uh, give you the details about about what American Express can or can't do in Texas.
Okay, but the website that Tasha had given, you all do have lawyers in Texas using that website, yes?
Yep, startovernow.org. Okay, you know, Texas, but we got, we got a lot of attorneys there.
It's service, it services everybody statewide. But if you're in Florida or Pennsylvania, you can directly call Chad. But if you do happen to hit, uh, the startovernow.org link, it will direct you to Chad. So you're gonna get his office, you're not going to get any other Florida or Pennsylvania office at all.
Okay, thank you. You all have a good day.
Thank you, no problem. All right, chat, before they come beat you down, end the live yourself. Thank you. How did that— we warming you up for this?
Yeah, I love it, man. I talk to people for a living, so this is, this is great. And okay, my favorite part about what I do is you could just hear it in their voice. Once there's a plan, they're like, you know, I'm gonna sleep better tonight. Yeah, I'm gonna take care of this debt. I'm not gonna let this rule me anymore. It's so much fun. I appreciate everybody that called in.
Anytime. So next Monday, same time?
You know it. I can't wait.
Ask Chad. Okay, this is a debt-free live stream. If you are not trying to become debt-free, go somewhere else, okay? But if you're trying to become debt-free, have your ass up on this live next Monday, same time. Um, that is 4 PM East— uh, actually, 4— 5 PM Eastern Standard Time, okay? Uh, for Chad, uh, 4 PM for us. And, uh, but you know, it doesn't matter. Uh, also, guys, anything that I'm missing besides going to startovernow.org, or you can contact Chad's office personally at the Van Horn Law Group. And I'll make sure I have his details, uh, at the, uh, bottom of the screen next time too. So if you live directly in Florida, it doesn't matter if you're in Jacksonville, Panama city, it doesn't matter. You can still call his office and he can, uh, he can get a bankruptcy going for you or, you know, litigate for you if you have problems with, uh, with, um, you know, creditors. Free consultations. Oh, we got it! There you go. See how I just envision things and then it comes up, man.
You guys are so good.
We're behind today. Monday has just been kind of— it's like Mercury retrograde going on or something.
I don't know, like Man, today has been a crazy day, but man, this was so much fun. I'm glad. This, this was definitely the highlight of my day.
I'm glad, I'm glad. Thank you so, so much. Um, guys, uh, we're here to help. Visit startovernow.org, or you can contact Chad, uh, Van Horn directly at Van Horn Law Group in, uh, Fort Lauderdale, Florida. Don't get too drunk tonight, uh, for Cinco de Mayo, because I know what's about to happen. I done ran and tell you now. I done ran and tell you. I'm like, Chad, they said I'm going to jail. You like— you remember when they were saying I was going to jail for filing bankruptcy with you?
I do. Unbelievable, man. I— yeah, that tequila is gonna hit tonight, I can tell you that.
Okay, cool, cool. Thank you so much, Chad. We'll go ahead and drop you off. I'm gonna stay right here with the winos for a second. Love you. See you next Monday, 5 PM Eastern Standard Time.
Okay, have a great week. I appreciate you.
Thank you. Bye-bye. All right guys, thank you so much for being vulnerable with Chad. I like that. So here's the thing, why knows, you know the winos are always right. Okay, let's get that straight. We don't do these shows even though, yes, uh, we're advertising a product or a service. That still doesn't mean that the people who are selling that service get to treat you any kind of way. Okay, period. So if you have a bad experience, whether it's with shoptkdeals.com and any of the products, or, you know, with startovernow.org or any of the lawyers, please email me and we will rectify it. Trust me, even with tashaklive.com, the winos are always right. I do not take your money for granted. Y'all work just as hard as we do here. And if there's something wrong, we're going to fix it, even if that means giving you your money back and still letting you keep the product. So just know how serious we are about that. So I appreciate the wino that came on here to say, and there's one that wrote in as well. Trust me, I already got a team meeting being set up with Philip. He is our bankruptcy liaison attorney that connects us with partners. Within Chad's network, and we will be rectifying that. I don't give a damn who it is. If you treat a wino or any of our viewers wrong, you will not get any leads from us. You're off the list. They can go find leads somewhere else. Okay, I love you guys. We'll see you next Monday with Chad, uh, for Ask Chad. Any questions that you have, we are going to be kind of training him up so he could do this live stream by himself with you guys, and Jasmine will be his producer, um, and he can answer some questions for y'all, okay? And y'all have a whole hour with him every Monday, okay? I love you guys, and with that being said, now we gotta go. Bye!
More from Latasha
Ray J Debt EXPLODES? | Tasha K & Chad Van Horn Talk Financial Secrets They Don’t Tell You!
LATE POST‼️ Winos PLEASE don’t run my team off! I need them for these events!😩😳