Papoose, Remy Ma, Dame Dash & the Money Crisis | Tasha K x Chad Van Horn
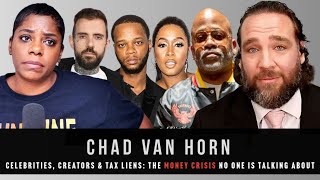
In this 2026 YouTube interview, host Latasha "Tasha K" Transrina Kebe talks with seasoned bankruptcy attorney Chad Van Horn about the widening financial crisis affecting everyday Americans, content creators, and high‑profile celebrities. They discuss the surge in Chapter 11 and Chapter 7 filings, the impact of rising living costs, medical and student‑loan debt, gender‑based income disparities, and the role of AI in government garnishment efforts. The conversation weaves personal anecdotes (e.g., Tasha’s own bankruptcy rumors, Chad’s recent court win), case studies of celebrities like Papoose, Remy Ma, Dame Dash, and Adam22, and client testimonials illustrating successful restructurings. They also critique the U.S. healthcare system, compare it to European models, and explore how artists can monetize their work without falling into debt. The episode ends with a call‑to‑action, promoting Chad’s firm (Let’sFixDebts.com) and encouraging listeners to seek bankruptcy relief before garnishments or credit‑card spirals become unmanageable.
Chapters
You look fancy today. Yeah, I just got out of court.
When am I going to get a t-shirt? When am I going to get a t-shirt?
When am I going to get a t-shirt?
All right, we'll do a t-shirt.
I should have had a t-shirt where you got my case confirmed.
Yeah, so we got to do like the NBA players that— the swap. We gotta do the swap.
We're gonna swap jerseys. That's what we're gonna do.
We'll make that happen. We'll make that happen.
Did you look good today? You was in court?
Yep, I was in court for a few hours.
Did you win? What had happened?
We dominated, actually. So it was fantastic. We were in front of Judge Russin, who's one of our favorite judges. Okay. You didn't have Judge Russin. He's great. And I took a new associate with me, and we were extremely successful. Extremely successful in the Chapter 11. So very happy.
Another Chapter 11? How long did it take to confirm this Chapter 11?
Not as long as somebody else that's on camera right now, I can tell you that. But, but it, it, it took a little while. And, uh, luckily I think these creditors are, are, are getting a little tired because so many people are filing Chapter 11 right now that, uh, they're, they're quicker to make deals, which makes things a lot easier from my standpoint, for sure.
Yeah. I mean, everybody's taking a hit right now. It reminds me of that last depression we had when Obama was in office. It was like 2008. Everybody, especially with the housing market. I think it was the housing market that saw the biggest collapse along with the stock market.
For sure. And I just saw a headline, and I think it was in the Wall Street Journal, that the new poverty line, if you take into consideration every— the price increase of everything is $130,000.
That is insane. We need to be living like 10 to a house to make bills so we can save up. And we need to be going— you know how they used to do back in the day? You buy like 2, 3 acres of land and all your family live on that land. Y'all build y'all houses just so y'all can make ends meet because it's ridiculous.
It is insane. And like, people that make good money are struggling like paycheck to paycheck. If they're sick for a week and miss a paycheck, they're missing rent. It's unbelievable. And it's really not being reported on. So thank goodness by traditional media, what do you call it? Legacy media.
Legacy. Legacy in the past. I just saw a story. I don't talk about death, but very unfortunate story. So I'm not going to name his name or anything like that. But there was a story that came across my a feed. It wasn't AI because I have to verify all my stories now to make sure I'm not taking in no fake news. But like, uh, the guy's inhaler— he had asthma, I don't know if you heard about it— and his asthma went from $6 a month to $532 a month, and his rent was due. So he paid his rent and thought that he can get his asthma the next check. He ended up dying is what I was like, no way, that's horrible.
Yeah, it's the reality in America today, unfortunately. And I don't know what's going to fix it.
Who's to blame for this? Do you know? Without teetering the line, but—
Honestly, this has gone on for so long. I was in court talking to another attorney about it. I mean, this is centuries of buildup. So I blame the system, to be honest with you, because the system has just— and the corruption, the greed, and it doesn't come down, unfortunately, to just one person, one party. They all have blood on their hands, if you ask me.
So do you think that's why everything is so aggressively happening right now, to try to wipe everything out and start over, to avoid the inevitable of everybody not being able to afford nothing?
I honestly— this is a different recession that we're going into than, than previous recessions, because the previous ones were focused on the housing market. The dot-com bubble. I mean, there was a specific— and now we have this AI bubble. I honestly don't know what's going to happen because I've never seen this many people stressed out at the same time. I've seen, I've seen middle class stressed, I've seen lower class stressed, I've seen even wealthy people get stressed. But now it's truly everybody, unless you're a billionaire, I guess everybody is stressed right now, including, uh, business owners.
I'm noticing a lot of content creators are really going through it. A lot that I personally feel like didn't have a plan for a rainy day. You know, they splurged, they got the really nice apartment, the really nice car. You know, they're living this lifestyle to be content creators. And now I'm hearing that this is probably the biggest content creator apocalypse ever, along with the hip-hop artists who are tax liens up to their neck. We just debuted yesterday Papoose and Remy. I don't know if you're familiar with the hip-hop, you know, couple. And Papoose has about $400,000 in tax liens. Remy has $700,000. Like, this is it. And people think, well, they're not broke. And I'm like, when you haven't paid taxes since 2012 or you got some— that— what do you call that?
And you got to be careful because you remember Wesley Snipes went to jail, actually. So yeah, there is a time where it goes from civil to criminal. So you definitely want to have that addressed, addressed as quickly as possible. We have so many people coming in right now that have old taxes that we're clearing out through bankruptcy. And a lot of them are content creators that were making a ton of money, especially during COVID times.
Yeah.
and, and they didn't necessarily have their taxes lined up and they never paid it. But fortunately, there are ways to discharge or get on payment plans through bankruptcy and negotiating with the IRS.
Can we clear up something real quick? Because there's this rumor going around that I never paid my taxes and I was seriously behind on my taxes. Did you find any facts of that in my bankruptcy when you did my bankruptcy? I just, I just Because people thought I was going to jail for tax evasion, tax fraud.
I just, you know, I normally don't talk about my clients' cases, but I'll make an exception. I'll make an exception here. I can tell you, out of all of the issues that we had to deal with in your case, the IRS was one of the least concerning because there wasn't a real issue there.
Thank you. Thank you. Yeah, thank you. Okay, I just had to, you know, put that in there because there's this rumor floating around that it's not a rumor. It was said as a direct fact that I'm behind on taxes, that I haven't paid tax. I'm like, what? Who said that? Like, yeah, I don't know what information they got, but I just wanted my lawyer to clear that up. So yeah, nobody looking for me.
You're good there. Yeah, you're good there.
As far as the content creators, what content creator did I see recently? Adam22. He's a really He's a colleague of mine. Are you familiar with him? No Jumper?
I am.
Adam22?
I am.
We got to get you on his podcast so you can talk bankruptcy. He'd love that. But like he, during the COVID time, said he was making, you know, millions of dollars and had went and bought this nice studio downtown LA. You know, LA is freaking expensive. And, you know, he had to put it up for sale and he had to downsize. He had to let a lot of employees go. And so right now he says that his Plug Talk podcast, which is his podcast, is carrying his, his regular media-based content. Uh, yeah.
Yeah. And I was, I was on a podcast yesterday and one of the guys was talking about California. He said he ordered kids' cheese sticks in California for $20. I was like, I'm never moving to California because I love cheese sticks. I'm not paying $20.
You can go down to the Aldi's and get them for a dollar. I think, you know, that's a whole nother conversation I want to have with you on the next— I'm gonna write that down for our next show. The laziness of Americans, how we don't want to go to the grocery store no more. We want everything delivered, and it is costing us triple to live where if we cut some of those things.
Yeah, no, it's, it's crazy. My, my wife, who's 8 months pregnant, you know, she wants certain food. I hop on my Vespa and I drive and get that because I look, man, I look at these prices. I go to a whole enchilada right by my house. It's $20 if I go pick it up. If it's through Uber, it's $50.
See? And the fact that it's $20 for enchilada.
That's already expensive. No, there's two.
That's two. That should be a $6 meal.
That's two enchiladas. So that's $20 for two. But still, yeah.
That should be a $6 meal. We got to get Chipotle to serve enchiladas. But I want to talk about this. Um, you— single women are carrying larger financial loads now. Yeah, let's talk about that. Apparently, single women are the largest demographic group filing for bankruptcy in the U.S., okay? And this reflects financial responsibility, falling on one income, not being irresponsible. Talk about that right now. You know, we got a lot of single women that watch our show and that love you, by the way. They're trying to be like a second wife or a third wife or a fourth wife.
What's my nickname again?
Chatty Zaddy. That's what they call you. That's what they call you. They want you to be a polygamist around here, Chad. They said there's enough of you to go around. Listen, and you good with money. They like, oh yeah, please.
That's funny. That's funny.
Yeah.
So the single women out there, and I was raised by a single woman. My dad died when I was 1. So I certainly understand. I remember my mom. Getting a second job working at Casual Corner back in the day so she can afford the clothes actually with a discount so she, she can get to work. So I certainly get it. And now it's, it's a weird— it's a weird world out there where people aren't like living together, dating, getting married. So if you're living in South Florida or you're living in any of the expensive places where a lot of people want to live, especially single women, it's hard without roommates to be able to afford all this. So that's why you're seeing these credit cards get used and they're getting used for basic expenses and they're just growing, growing, growing. 30% interest rates. And then all of a sudden you lose your job. Something happens. You got to file bankruptcy.
So it used to be 19%. What? How did we get to 30%? That's why I'm not getting no more credit cards. You got mine wiped out in the bankruptcy. I'm not getting no more. I don't need them, man.
A cash existence is not a bad existence at all. And And I really, part of it is the social media part where you see everybody. It looks like everybody's partying, going to these islands, spending all this money. So you want to do it as well. But if you, like you always say, if you don't got it, don't do it. But you can't, you need to have a plan to pay off those credit cards or it's going to kill it. It's going to kill your credit and you're going to end up filing bankruptcy.
I tell them, baby, it's due in 30 days. So if you ain't got the money now, are you going to have the money in 30 days? Because if you can't pay off the full balance that you use, there's no use of you getting the credit card at all.
Absolutely not. It's just a downward spiral. If you can't afford to pay it today and you're using Klarna or whatever those companies are that, that are going to delay payments and you're still not going to have the money, then you're going to end up still— I talk about that story where somebody's paying $700 for Jordans from Rent-A-Center, um, because they're, they're renting their Jordans. Blows my mind, the decisions that are being made. And it's for vanity. I mean, it's not— I get for the people that are trying to feed their kids or do whatever you can to do that, but I just don't understand for vanity purposes, uh, going in, causing all that stress, going into debt and not having a plan to get out of it.
Yeah, that, that's insane. I'm, I'm glad that was, you know, even though I filed bankruptcy twice, it's due to business issues, not my personal. You know, because I always make sure at the end of the day, I have a roof over my head. I'm gonna, I'm gonna be able to, to move on. So, you know, that, that's, that's really hard. Now, you did say something I want to talk to you about, about on average, they say women earn about 85 cents for every dollar earned by men. Now, I was told, and I don't know if this is just statistics within our community, primarily the African community, which is women make more than the men. So, but if you, if you look at it overall, men are still dominating 15%, making 15% more than women, even though we have to sacrifice more when we have kids and we're wives or we're single to go into work. And it could be the same position.
Yeah, there certainly still seems to be that glass ceiling. I'm glad that a lot of it's broken and there's opportunities for women to grow. And my firm is actually led by strong women, which, which it makes sense because I was raised by a strong woman. That's, that's your mom.
She's sweet.
Yeah, she's great. She's great. So, so, so most of my leadership, strong women. I like being surrounded, surrounded by them. They're great. But yeah, they're still out there that, you know, there's areas where women are getting paid less than men and That means that they're unable to pay their credit cards or unable to pay their bills because they're working just as hard. They're working 100%, but getting paid 85%. So it, it's, it's just difficult out there across the board. And again, I'm glad that you're talking about it. We're talking about it because if you, if you look at, uh, the national news, it seems like everything's great, everything's working out, the, the stock market's hitting records. But guess what? These broke people are not investing in the stock market because they don't have any money to invest in the stock market.
Oh, this is it. Yeah, yeah, yeah. I typically don't believe in the stock market because I'm like, I've seen it crash too many times in my lifetime. And they're like, always, don't worry about it. When it crashes, it's going to pick back up. I'm like, but what about my money? What if the company goes out of business and goes into bankruptcy? What am I going to do?
Yeah, I'm kind of on board with you with that. I like investing in things that can't be taken away. And things that are tangible. I like investing in myself, my education, my business, real estate. Stock market definitely scares me.
It's too scary. I have a heart attack before I even get the returns on the cash. Help me, Lord, like Red Fox. Oh God, oh God, help me, help me. Now you're also saying job type matters is what I'm hearing. Okay, so A higher percentage of women work in service and care-related fields, which tend to offer like lower wages now, less flexibility, and fewer employer-provided benefits. What do you mean? What's that all about?
Like, yeah, so depending on what industry you're in, obviously there's certain industries. Speaking of stock market, like if you're in that stock industry, you're going to get paid more. There's going to be more benefits. But if you're a service worker, if you will, so working in restaurants, elderly care. They're not going to be those opportunities first to get bonuses, to get those 401(k) matches, all the health benefits, all those other wraparound benefits that are extremely beneficial. And in some, in some cases, like the healthcare, you need it, uh, and, and they're just not getting that support that they need. So it's, it's an extreme issue, especially for 2026. We're going to see with the healthcare costs go up that there's going to be a lot more healthcare medical-related bankruptcies.
So, and so for that reason, I mean, these are all, I would say, good reasons for anyone in any of these fields, or if you're a single mom or whatnot, to call you.
And, and sooner than later, because, you know, that stress just builds up and it's going to lead to more health issues. More sleepless nights. So the sooner you make the phone call, the faster that you're going to get your life back and get in control of your finances.
Oh man. Let me ask you a question. I don't know, maybe this is off the charts. I don't really kind of deal with this, but I saw a very sad story online of a girl who was working, and I guess something happened with her insurance. She was on chemotherapy. They cut her insurance, and she ended up passing away because they cut her insurance. If she were to file bankruptcy, like, could that have helped her anyway? I don't know why I'm asking this question. I guess no question is a dumb question, but like, how can bankruptcy help people who are in situations like that?
So when, when everybody talks about universal healthcare, we technically do have universal healthcare and it's called the emergency room. So if you go to the emergency room and you really need healthcare, they're going to take care of you. And then bankruptcy can clear out that medical debt.
Okay.
And medical debt is the number one reason for filing bankruptcy. So if you really are in a life or death situation, go to the hospital. They will take care of you. We can either negotiate the bills or file bankruptcy on the bills afterwards. Now, in a situation where you need long-term care, that can be problematic because bankruptcy can wipe out the debt after you get the care. But if there, if nobody's willing to give you that care, then, then unfortunately, you know, you may have to revert to leaving the country, um, going find somewhere that the care is affordable for you or where you'll be taken care of. So that's a, that's a terrible situation.
And I literally, I argue with my friends about this all the time because they're like, the United States has the best, best healthcare. And I'm like, do they? Do they?
Well, It might be the best if you could afford it.
Yeah. Like, I'm looking at how the EU takes care of their citizens. They give them universal healthcare. They're all healthy. Their food isn't tainted with all these chemicals. So there's a lot of preventative care put into them. And then when they do get to the hospital, it's easier to heal them because they're not like 400 pounds obese or they got metabolic syndrome and stuff like that. And Italy, people are living longer in Italy and in some parts of Africa than anywhere else in the world. Why is that?
And every time I go to Italy, and that's my favorite, favorite country in the world, I go there and I lose weight. And I eat more, but I lose weight. Why is that?
We have to ask. We got to get some scientists. So listen, did you hear? Now let's get into the celebrities. Did you hear? Because I know we talked a little about Papoose and Remy, who need to call you. They need to call you. Okay.
And I'm, and I'm, and I'm actually a big fan too. So, you know, I'm going to cut them a deal if they call me.
I'm going to make sure we tag them in this clip. I'm gonna put their picture up, make sure exactly when it was them, so I'm gonna call you and help them write about that stuff. Um, uh, Damon Dash's company, his production company, just auctioned— was auctioned off in this Chapter 7 for $100. Somebody bought it for $100. Did you hear about that, Chad?
Yeah, I did. That, that— I mean, talk about a fall from glory. It hurts to hear this happening, and it's happening in Florida as well. Um, so the trustee auctioned it off, $100. Didn't— wasn't Mason Cameron gonna give them like $100,000 or what? Yeah, right.
Yes, man.
Ego and pride just get in the way of things. Like, come on, that's such a shame.
How did the trustee value it at $100 is the question. Like, how do they come up with these, these valuations?
Well, well, you, you auction it off actually. So it actually, it's a public auction and if nobody bids and somebody will take it for a de minimis amount, which is $100. I assume the reason it went for that as well, if you remember, there, there were lawsuits not only against Dame Dash but his company as well. So that, that would obviously deplete the value because you're going to buy the company and you'll have to defend these lawsuits to, to actually be able to use any of the assets the company has.
Oh, I wouldn't touch that. Oh no, oh no, no, no, no, no. Somebody probably just trying to be petty saying, oh no, $100 cost you hundreds of thousands of dollars in, in possible lawsuits and judgments. I did hear a little bit about— we did have some filmmakers, because BET got in trouble for doing this, and their, their team got fired. Uh, we're gonna say allegedly just in case it gets thick, but you know, the CEOs were walked out for brokering deals from independent filmmakers, which means they would say, hey, you give me $25,000, $100,000 up front, I'll get your movie played on You know, like BET or BET+. Wow. Yeah. So they had to clean house. That's why there was no BET Awards or anything like that. But when it comes to Dame Dash, the filmmakers told me personally that he would basically take their films, give them, charge them fees to get their films brokered, put them under his quote unquote production company, and then broker them to like Tubi and Amazon and all that and keep the money. He wouldn't give him nothing.
Wow, that's terrible.
Yeah. Now this is somebody that claims that they're for the culture.
Yeah. And, and artists, you know, artists always think about the artistry, and that's why they get taken advantage of so much, right? They're worried about the movie, the painting. Even athletes are worried about their athleticism, whatever sport that they're playing, that they, they try to focus on that, and then people around them just always, always target them. And then you see, you see things like that happen. That's, that's terrible. That really is terrible.
I try to educate artists so much, like, yo, I know that you love your art, but art is only used to sell ads. That is it. That is all. Yes, people will be inspired. They're going to love it. But if an advertiser, if they can't slide no ads in there, That's where their revenue is coming from.
100%. 100%.
Other than that, your art is— I'm not going to say it doesn't have any value, but it doesn't have any value to mainstream media because that's how they get paid. The foundation of their platforms are ads.
Yeah, for anything that you do, it's how do you monetize it, right? How do you monetize the art that you're creating, whatever you're creating. I mean, obviously you're creating, we're creating art right now. This should be in the Louvre actually, what we're doing. But yes, how do you monetize that? And you're right. When it's podcasts, you got to be able to have people come in and monetize it through advertising.
Man, I may need to start having some podcast seminars and stuff like that because I be seeing people, they spend, oh, I just built a $50,000 studio. What? Wow.
Yeah, that's, that's crazy.
I started with my phone. Hey guys, what's going on? Y'all saw that new Princess Ray J? He pushed her in the pool. And I let that check build that check, that check build that check. They go right in with these nice lavish studios and then they don't have anybody to edit the video.
The most important part.
Wow.
Now that's— and I actually see that with a lot of businesses. I have people that come in that are starting businesses and they want to have structure. They want to sell. They want to do this and the other. I said, have you made any revenue yet? Have you sold anything? And the answer is no. And they're spending all this time, money, effort getting things set up so everything's going to be perfect. I said, but what if nobody cares about your product? Like, go sell a few and then we'll work on the admin costs of the structure and all that other things. I've seen it thousands of times.
So you do this instructions for people?
I do.
Okay, I didn't even know that. See, I learned something new every day. I—
because I've seen so many businesses fail for simple reasons that I'm trying to get ahead of it as much as I can. So I try to help them structure themselves in a way where they're not wasting money, they're focused. And again, focus on the revenue side. How, how are you going to make money? And then once you start making money, use that money to build the structure, build everything around it. But don't, don't come in wasting money from the beginning because you need that, that seed money to really get your business going.
Yeah, that's like people using credit to start a business and you're already broke. I said before, the only way I'm using credit to start a business is if I buy a house and I put a renter in that house. That's it. They're gonna pay for that. I'm not paying for that. So no, like, uh-uh. Now, um, we got some, uh, client testimonials.
I love these. My favorite part too. I love this.
I'm serious. So we got one client testimonial. Your team sent this over. It's a small business— a small business Chapter 11 plan of reorganization filed in the United States Bankruptcy Court in the Middle District of Florida. So that's around like Gainesville, that area.
Tampa. This, this was actually Tampa.
This was Tampa. And so the situation was the debtor faced, um, like liabilities exceeding like $5 million.
Oh my God.
Yeah.
And defaulted on all of them.
He what?
Defaulted on all of them, and all the accounts were frozen when he came and saw me.
So who he came and saw you so you could get a stay and all the accounts are unfrozen so he could do business? And save his company. Yep.
And it was a compression sock business and it was unbelievable the results that we got. We ended up suing one of the creditors. The judge, and this judge is fantastic, she actually ended up buying two pairs of the socks, the compression socks, and she loves them. She said she's a lifetime customer.
Compression socks, that's a business because I fly all the time and then people eat obscene amount of carbs and it just— salt retention, sugar, water retention in the body. You need compression socks because that's going to help your blood flow better to your legs.
Yeah. And I might, I might bring him on, his company on as a sponsor as well for you. I'm going to make an introduction to see if we can make that happen.
Our audience will eat that up. For real. I do compression pants, but I really want compression socks. So I'm going to make sure I get some. Now, So I guess you ended up getting a stay put on so he was able to do business again. Partly one of the reasons why I came to you, they was trying to freeze my accounts. So you got them unfrozen. Shout out to Chad. He said, we got our money and we went to work. How long did it take you to, to get this confirmed?
So the judge actually was surprised with a case like this that was highly contested. We got it done in about 6 months.
No way.
About 6 months beginning to end. And we actually had a value. It was funny. We had a value, tens of thousands of pairs of these socks because there was a secured claim on them. So we wanted to bring that secured claim down to what the value of the socks were. And it saved this business millions and millions of dollars. And we worked out a payment plan over years. This business and the CEO of this business is fantastic. It would have never gone this way, but they had issues with, with Facebook advertising. There's a different longer story that we can talk about there, but he really got screwed by his advertising partners. So this business is definitely going to be successful.
Okay. No, because it says I'm looking at your outcome results and this is the confirmation of the plan achieved. Mass, like you just said, massive debt discharge, eliminating 80% of the general unsecured claims. That is insane. Okay. Now, I guess it says you guys, Chad, successfully, successfully structured Um, the discharge, I guess it was like over $2 million in general unsecured debt, but he had $5 million in debt. So that's over half.
Absolutely. And we reduced the secured claim from over $2 million down to $500,000.
So that's secured claim, maintaining 100% ownership of the debtor's present. What?
Yep. It was a, it was a huge success. And all of these Chapter 11s, and you know this very well, it really is a part, it's a partnership. Like I can only do so much, right? I need, I need the client or the client's management to step up. And this is a case where the management stepped up, crushing it. And I'm telling you, 2026 is going to be the best year ever for this company. And I just can't wait to see it grow.
Oh my God. Oh my God. Now we got another one. Jonathan and Natalie. So these are your clients. Case type Chapter 7. This is everybody's favorite because when you hit a Chapter 7, You owe nobody. You say, fuck you, I ain't paying shit. Come get it. Judge said no. Listen, so starting situation, they filed a Chapter 7 with you. You were able to discharge. Listen, why knows? Chad was able to discharge in a Chapter 7 for her. This is husband and wife, I take it. They were $324,178 in unsecured debt. For— oh, my husband. And yeah, so I guess this was for the husband. Did the husband accumulate all this and Natalie had to file?
Wouldn't go to her. Yeah, they, they actually both co-signed for, for business loans, so they were on the hook for a bunch of business debt. Their, their personal credit cards were maxed out, everything, and they were losing the business, so they were losing their income. And, and they, they just wanted a fresh start. They wanted to move on with their career, get this behind them. And when I told them, I said, all right, give me 3 to 4 months and we'll be able to discharge all of this and all this will be behind you. They literally were crying in my office. Um, they thought, they thought they were gonna be stuck with this forever. It's gonna be years to rebuild. And, uh, they couldn't be happier. So, uh, really nice people.
Y'all need to stop stressing over that you can't pay. Let Chad just 3, 4 months You starting over. And if you already own a house, great. They can keep their house, right?
Absolutely. Homes are protected in Florida.
Okay. The first thing I get hit with, well, if Chad files, Tasha, can I keep my house? Can I keep my car? And it's like, yes.
Yeah, 100%. And when people come in, they have all these misconceptions about bankruptcy. It's bad. I'm going to lose everything. Somebody thought that like their picture gets put up on a website or something. That was, that was a new one to me, which that certainly doesn't happen. Over 9— we have a 99% discharge rate in Chapter 7, and I would say 95% of those don't pay anything back to the creditors because they're what's called no asset cases. And that means no non-exempt assets to pay creditors. So you get to keep your house as long as you keep paying on your car, you keep your car. You keep paying your rent, uh, and you just get rid of the debt.
I like how you make it easy for everybody because you come in there, we'd be like stressed out, and you'd be like, it's all right, just, just give me paperwork, we're good, go on about your business. Like, you make it so easy. It's like, really, that's all it is? And then when you get the job done, it's like, that's it? You sure? Are you, are you serious? You ain't gonna come back? You playing? Yeah.
And, and we're— I think I'm 10,000 cases into my career almost. I've been doing this for almost 20 years. So it's, it really is amazing. The, when people come into the office, they're stressed out, they think that life is over, they're going to lose everything. And really, 7 minutes into the conversation, we're laughing, we're joking. They're like, how did this happen? I was going from crying to laughing. Now I'm like, that, that's the magic of bankruptcy and dealing with professionals.
One more Chapter 7. We just gotta, we gotta give you, you know, we gotta give you flowers, Chad. Okay, so Chapter 2017. This is by Nicholas D. Okay, and he only had $24,000 in debt, in unsecured debt, to be discharged. $24,000. People think with $20,000 debt they can't come see you, huh?
Yeah, and, and, and he, he was on Social Security, so he was paying this credit card debt from his Social Security. Oh, and, and I— yeah, and first off, Social Security is exempt, so they can't garnish Social Security. They can't touch it anyway. And second, I mean, these Social Security checks are not big checks, and he needed it for his medicine, he needed it for his rent, he needed it for everything else, and he didn't want to be harassed by these creditors. So I said, we'll make it easy, and we discharged that. That case went quick too. Got us the documents, we were done again in about 3 months beginning to end.
That is amazing. Shout out to Nicholas D. How much unsecured debt do you need in order to qualify for a bankruptcy?
There's actually no number. There's no set number. What I always say is I base it based on your disposable income. So how much can you throw towards the debt versus the monthly debt payments that you would need? So if, if you're, if your income is $20,000 and you have $20,000 worth of debt, you should be considering, you should be considering bankruptcy. Because you're never going to be able to pay that $20,000 off. Now, if you have $20,000 worth of debt and you have $200,000 income, that maybe is manageable for you depending on what your other expenses are. So it really depends on how quickly you can pay that debt off. If you can't put a plan together where you're going to pay the debt off within a 12 to 24 month period, you should be speaking to a bankruptcy attorney.
You hear that? If you cannot pay your debt In 12 to 24 months, call Chad.
100%.
We need to change your name to Call Chaddy Zaddy.
I'll, I'll, I'll see if the website's available.
ChaddyZaddy.com. He say you ain't got it, he got it.
Look, we're, we're turning this into a commercial. No, for real.
It is like, I, you know, I get so many like DMs and emails and like, Tasha, thank you so much for like introducing me to Chad, even though I can't use him. Some may not be able to use you. They'd be like, but you helped me to just get that push to, to be able to call you, maybe get a referral with a law firm that you have a connection with. Because, you know, people love referrals. It's like you said Chad, Chad's the best. So Chad got to tell me where to go. You know what I'm saying? Or they call you personally and they're doing it. They're not afraid. They're not ashamed. What I feel like is that people live in these, you know, I don't know, they feel like they have to prove something.
And yeah, and a lot of it is fear and ego. Those are the top 2 reasons that are stopping people from moving forward with their lives. And it really is a shame because the other side is so much brighter.
Mm. I'm telling you, that's why I love to publicize my bankruptcy all the time. I said I'd do it. I'd do it again. And I remember hearing from another legal team who says that they would stay in bankruptcy forever. Who says that? You work for the creditor. Of course you're going to be upset. I know the law, sir. Catch me if you can.
I love it. I love it. I actually have a client that they've been in Chapter 13 for like 15 years. They just keep filing. They get out, they keep filing. Because creditors, it's legal. And they don't want to be harassed by these creditors. And these creditors are non-dischargeable. And they're like, well, what are you going to do? Keep filing Chapter 13?
And that's my plan. If I have to do it, I'm going to do it. And ain't nobody can do about it.
It's your constitutional right.
A constitutional right. Like I exercise my freedom of speech and all that other shit. Who cares? You don't like it, go eat beans and rice. Listen, hold on for a second. I just want to make sure we cover everything. Chad, we did cover— we did cover the shame, the guilt. And I think sometimes, like, there's still that, like, they need that extra nudge, that extra push. And I think you had said somewhere one time when I did see like an interview of yours, around like 3 million or so people— hold on, let me make sure I get it because I wrote it down. So let me, let me make sure I get this right because I'm— I don't want no misinformation on here, you know what I'm saying? Ain't nobody trying to get sued again. Why people still aren't filing— out of 3+ million borrowers who filed bankruptcy, only 7,000 even tried to discharge. Like, okay, that's a student loan thing, but like I think, you know, especially with the Trump administration now coming after the student loan borrowers and now they're starting to garnish. They said this month they're going to start garnishing. So which means if they're filing taxes, you know, and they get a tax return back, because normally if people are owing student loans, they're probably going to get some type of money back. The Trump administration is coming after to collect that money. Why do you think, even if If you know that he's going to come or the government is going to come and take money from you, people are still scared to file. Why? Why?
Yeah. You know, people don't act until they have to act. And once that garnishment hits your tax refund, hits your wages, which they can take 15% of your wages, they don't even have to file court documents. It's called an administrative wage garnishment. They can take 15% of your wages. That's when people act. And unfortunately, bankruptcy is helping with student loans. It does stop the garnishment and you can discharge student loans through bankruptcies through filing an adversary proceeding, which we've been extremely successful with that. You do have to qualify. So it's a special, special case that you have to qualify for, but it's worth taking a look, especially if you're in default. If you're in default now, those garnishments are coming. AI is helping them figure out who they can garnish, where they can get the money. The government is—
what you talking about? What you mean AI is helping them?
They have artificial intelligence that is helping them figure out who they can garnish, how they can garnish, and how quickly and efficiently they can do it. It's going to be like something you've never seen before in your life. There are going to be millions, millions of garnishments this year. By the Department of Education. It's, it's going to be unbelievable. So we're gearing up. We actually hired 5 new people this week that are just working on student loans. And it's going to be a crazy year in the student loan world.
So they need to get their ass up in your office.
Do it before the garnishment hits. We have more options. If the garnishment hits, you can definitely call, but call us before. If you're in default, you need to get out of default. Or we need to discharge student loans through bankruptcy.
Bro, I literally just logged into like my FAFSA student— I think it's studentloan.gov or something like that. And because my daughter is going to school and so I was looking at mine and said zero balance. I was like, oh my God, I only owe like $10,000, but I still paid it, you know? And it took what? Well, my husband paid it for me. Took 10 years to pay it. But I'm just saying like that, that was a good feeling. So that's the site that they're going to be going in to, to check. So they hooking this supercomputer up to see, and then they going out to see where your bank accounts is at, and then they just gonna send in a garnishment and just take it.
Like, think about it, they, they have the data because you're filing your taxes, so they know where you work, right? And all you have to do is connect the IRS account with the student loan account, and they could garnish your wages like that. That's all they have to do. And it, it is going to be bad. And most employers, they, they use 3 or 4 processors. So you just have to hook, hook up with ADP or any of these processors that give labor data to the Labor Department. They have all the information. And, uh, you want to know how the government's planning on paying its own debt? This coming out of your pocket, 100%. There's a plan in place.
I don't know why they just won't sell green cards. Everybody want to come to this country. They'll pay it.
It's not a bad idea. It is not a bad idea.
Pay us to work in our country. Every year you got to pay this green card to stay here, and you get to make money for your family and send it back to wherever you from. I don't understand what the big deal is about. They see— that's why we need women running shit.
I don't disagree. You know, I disagree.
Yeah, this is, this is insane. Chad, what do you want to leave the viewers with today?
If you are stressing with debt, stop it. Give me a call. Let's get you out of debt. It is stupid. Year after year, you're going to say, I'm getting out of debt. Well, let's make this the year that you actually get out of debt. Call today. Let'sFixDebt.com.
Let'sfixdebts.com. Let's fix that.com. Okay, stop playing around. I'm gonna call my sister again and tell her, now you owe about $280,000. That's not with interest and stuff like that. You probably need to get down there to check. I'm good. No, when they start garnishing and you only make about $80 grand a year, uh, that's not a lot. 80 grand is like making 20 grand now. Half of that go to the IRS.
100%. It's, it's, it's, it's a tough time, but I'm glad we are here for the people.
Yes.
And we are giving them their options and we're giving them the strength to make that call, to go to the website, whatever little step you got to do to get out of debt. We are doing the people's work right here, Miss Tasha.
That is Daddy. He came through with a suit on for y'all. A suit. Suit. The man got some money, y'all. He got money because he know, he know the law. He know the bankruptcy law. So listen, y'all call Jed, or better yet, let'sfixdebts.com. Um, you have locations in Florida as well as, uh, Pennsylvania. Um, and you have reps on standby. Are you guys answering calls 24/7?
24/7 at this point. And, and we have referrals all throughout the country, so we'll make sure people get taken care of. We take care of the winos. You know we take care of the winos.
I know. Happy New Happy New Year, chat!
Happy New Year!
Thank you. Now we gotta go. You'll be back. Bye! Yes, sir! Yes, sir! Yes, sir! Yes, sir! Yes, sir! Yes, sir! Yes, sir! Yes, sir! Yes, sir!
More from Latasha
Ray J Debt EXPLODES? | Tasha K & Chad Van Horn Talk Financial Secrets They Don’t Tell You!
LATE POST‼️ Winos PLEASE don’t run my team off! I need them for these events!😩😳