Unlocking Fintech Success: Strategic Trends for Profitable Growth: Webinar Leadership Series
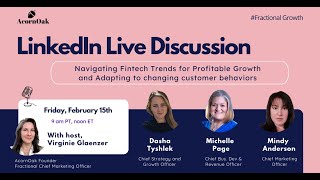
Michelle Page, Dasha Tichlik, and Mindy Anderson discuss five trends reshaping fintech: a rural-urban banking gap, $70 billion in gig-economy revenue, cooling venture capital demanding profitability, tension between automation and personal service, and growing cybersecurity risk. They outline concrete opportunities for small firms: co-branding with trusted institutions, biometric authentication, and targeting underserved regional markets.
Chapters
Let's, let's begin. First of all, welcome everyone. Happy Thursday, February 15th. I hope you had a sweet day yesterday. Hello everyone and welcome to the Aikon Oak Leadership Series. My name is Virginie Glaenzer. I'm the founder of Aikon Oak and fractional Chief Marketing Officer And for today, your host. So for those who are not yet familiar with Econook, we are a community of fractional executive women who present an incredible opportunity, especially to founders and CEOs of small and mid-sized companies, because they can tap into executive leadership expertise at a fraction of the traditional cost. This is huge. And if you, of course, if you want to learn more about our community of executive advisors and coaches in all areas of expertise, I will invite you to go to econoc.net and check us out. So today I am joined by 3 of our executive members to discuss unlocking fintech success, strategic trends for profitable growth. But before we begin this amazing conversation, let me briefly introduce you to each our speakers. The first one, Michelle Page, is a fractional Chief Revenue Growth and Business Development Officer. She has 30+ years experience growing companies of all sizes in diverse industries such as SaaS, fintech, health tech, healthcare, professional services, and manufacturing. She combines a passion for growing startups, and she has personally trained, coached, and managed over 150 sales leaders while developing over 700 people in her chain of responsibility. Michelle's impact on the revenue ecosystem is truly remarkable. Welcome, Michelle.
Thank you, Virginie Glaenzer.
I'm excited to hear your expertise. Dasha Tichlik is a fractional Chief Strategy and Growth Officer. Having worked closely with many founders and CEOs, Dasha has been instrumental in Lindy leading their highest priority project and bringing their vision for company growth and transformation to life. Her extensive expertise ranges from strategy design, program management, marketing strategy, executive coaching, and she's applied her skills across many industries, more than 10 actually, including biomedical, healthcare, space and satellite, and advanced manufacturing. Welcome, Dasha. Thank you. Glad to have you with us. And then Mindy Anderson is a fractional chief marketing officer with over 20 years of brand and digital marketing leadership experience with worldwide iconic brands. Mindy has a passion for working on big challenging problems, and there's a lot, as well as finding creative solutions that reach people in an authentic and personal way. Her impressive track record includes scaling businesses into best-in-class brands and achieving measurable impact for clients, having done so across 5 times their initial potential. She has applied her skills across a diverse range of industry, including SaaS, e-commerce, commercial real estate, and holistic care and wellness. Welcome, Mindy.
Thank you.
So today's conversation is going to be focused on fintech organization. And when we talk about fintech organization, we are talking about those who provide financial services to customers, either business or consumer, but they all rely primarily on technology and cloud services rather than physical location. So to kick off our discussion on the current state of fintech, let me start with you, Dasha. I would love for you to share what you see as the key influences and trends in the fintech industry today.
Excellent. Thank you so much. So in preparation for this workshop, we had quite a few exciting debates because, you know, every industry has multiple influencing factors and they're all happening simultaneously. And in today's sort of hypergrowth, hyperchange world where everything is moving very quickly, it, it just diluting what exactly the main factors that we see took a lot of research and discussion between our groups. So we boiled it down to kind of 5 trends that we think are really important and significant and provide opportunities for growth as well as addressing new problems. The first that we articulated is something like a gradient, the disparity between technology and accessibility to banking, to capital, and to the quality of services and the variety of services in urban versus rural centers. We have a statistic around 13 to 15% of banking is still done, you know, is in rural areas. That's significant amount of the population, but there's a really big difference in the kinds of services that are available to both consumers, as well as businesses in a large urban center versus a medium-sized city in America, kind of outskirts of the cities where there's still a lot of reliance on technologies that are more than 20 years old and a slower change of pace to the technology landscape. So it's a lot of opportunity there, but also a lot of challenge. The second one that we thought was really significant is the growth of both the gig economy as well as the microbusiness. Microbusiness being defined as a business with less than $1 million of revenue. And these microbusinesses account for about $70 billion of revenue in the United States right now. And that, that's about half of the small businesses that exist. So these are typically businesses with just one or a couple of employees. Another interesting trend is the gig economy. They're kind of related. The flow between freelancer and being a microbusiness, you know, it's, it's, it's not fully defined, but more than 30%, more than a third of Americans participated in gig or freelance work in the United States in the last 12 months. There's been a steady continuous growth of freelance work, gig work, and independent consulting work. And this is not just a trend in the United States. It's actually global. Brazil is actually leading the way in gig economy, but also the United Kingdom and other countries in Europe as well are right there at the top of the list as having significant portions of their populations participating in this kind of contract independent work. The third trend we thought was very meaningful is the difference in the investing into fintech that we're seeing in today's economy. So we've been living through kind of a decade of hypergrowth where there's been a lot of investment into fintech startups. And now that, that investment is still heavy, but it's not nearly as aggressive. And there's a lot more focus now on showing sustainability and profitability. And so this is, this is a time when there's probably going to be a little bit more consolidation and a lot more prove that you can actually deliver revenue through your technology. And that's important to keep in mind as you're thinking about your product development that The, the proof that you need to be bringing to your investors is now higher. The fourth is kind of a tension being created by automation. So on one hand, we have, of course, this disruptive AI trend. But on the other hand, especially for small businesses, banking, you, you still have a strong desire for customer relationship and banking type relationships. So tackling this challenge of, yes, bringing in automation so that you can stay competitive, but at the same time being personable. That's another trend we thought was very important to be thinking about. And last, but absolutely not least, is the continuous growth of cloud infrastructure and the desire for having integration of various apps and services across the business needs and business operations. But with that, a heightened awareness of the need also for really tight cybersecurity, both based on real things that have been happening in the world with cybersecurity attacks, as well as a continuous movement towards cloud security, just creating more risk. So those are kind of the 5 trends. And Mindy and Michelle are going to start diving into their personal experience in terms of seeing this through their clients, through their work, how this is being realized in the industry.
Thank you so much, Sasha. That was really interesting, and I love to— I think it's, it's really interesting to see how technology is empowering a new breed of financial organization. You mentioned one of the trends as this explosion of the gig economy, and so I think there's that particular type of customer who don't seem to get a lot of attention from banks: independent consultants, freelancers, or even micro entrepreneurs, but also small business owners are not the typical client that banks are trying to, to get. Mindy, as a fractional CMO and a business owner living in a smaller community and, and also working with clients in the SMB category with really different needs than enterprise clients, can you share your experience?
Absolutely. So What I have seen, and I've moved out of New York as well. So now we're in a small country town where there's credit unions and there's small banks. But what I still see that's missing across the United States specifically is almost like imagine businesses in motion. You know, it doesn't really matter today what if you're a small business, medium business, or an enterprise, everything is in motion. And the fintechs have an opportunity to keep up with that. The problem with a lot of gig workers, freelancers, small business owners is that we also need that in motion after 5 PM, meaning we need our transactions to go through. We need— if you have an e-commerce store, if something happens at 5:05 and everybody has left from that small bank or that, that credit union and you need assistance, what will that look like? And so there is these digitization issues and operational issues that have not been modernized and upgraded to accommodate this movement of, you know, people working across the United States in different locations even. There's the issue that if they need to rectify why is my transaction with my client not going through, You know, even after 5:00 PM, it's not that late. However, getting customer service to accommodate whatever transaction issue is happening behind the scenes may not happen until the next day at 8:00 in the morning. So that means for a small business owner, they may have lost a sale. So when you break that down into microterms, that's, that's an issue that small business owners are not going to contend with, which means that they may or may not want to bank with a very large banking institution because they're a small business and they want to support small banks, small credit unions as well, because they want to put their investment in like-minded businesses. But if they cannot function and optimize their business at the level of the speed that Dasha discussed before, that puts them in a handcuffed situation because they still need the technology, they still need end-to-end operations, they still need, for example, Zelle or these integrations that these larger banks would have. They still want to be able to complete an onboarding application for, getting access to credit or lending within 5 minutes. So the lack of speed or the lack of technology or the lack of customer service that may not come to light for working with the credit union or small bank is an opportunity that fintechs have today to seize this market, which is going to be growing at an ever-increasing rate based on the fact that the layoffs continue to happen across the board. Across most industries as well. I also would love to kind of— oh, sorry.
Go ahead. No, no, go ahead.
I was going to say, I'd love to kind of hear Michelle's take on this as well.
So thank you, Mindy, for that. What I'm hearing is that technology trust is a recurring theme, and yet it's an amazing opportunity for organizations who actually get the right technology in place. We used to have technology generation every 100 years, and then back in the 1800s, it became more closer to 25 years, and in the last century, every 10 years. So now it's closer to every 3 years. Tech advancements are happening so quickly that it's hard to keep up, and it could be responsible for a lack of feeling safe and secure in our own finance. So, Michelle, I'm, I'm curious to know what are the trends that you're noticing in payment security and fraud protection to help consumers feel more confident?
Well, that's a great series of questions there as far as payments and, and trust and, and fraud. And that directly correlates to what Mindy was saying. When somebody is a smaller business, they need to feel safe. They want to support smaller companies, but there's that conflict there. So we need to bridge that gap. So the digital payment use, all of the, the consumer use and small business use of digital payments and digital fintech, all of the, the technology involved with that, that really was catalyzed by the pandemic. You almost had to transact over the internet or, or digitally. So that's really what catalyzed the growth of, of using fintech. But if, if you go back to 2009 when Square was founded, that was really the kickoff for business owners to use— I'm talking about the smaller business owners. To use digital payment acceptance and a lot of consumers to put their trust in using digital payments. But we've had sustained adoption, even growth of adoption after the pandemic as, as consumers get more familiar with that. They've gotten a little bit more open to new technologies. McKinsey did a 2003 study. It was a digital payments consumer study. And for the first time ever in 2003, 9 out of 10 consumers reported in the past 12 months they had done at least one form of a digital payment transaction. So it's here, it's going to stay, it's going to, it's going to increase. FinTechs need to be prepared for that. They need to be prepared to make consumers and businesses feel safe and secure, and they need to make the ability to use fintech in their business available to those small business clients that Mindy was referring to. That's going to help the, the fintechs, both the technology firms and the smaller community banks, the credit unions, is going to make both of them grow. Now, as far as that trust factor, McKinsey in that same study They looked at how consumers and businesses, what's their trust level of the larger banks and the larger tech companies versus the smaller community banks and credit unions and the smaller fintech companies. So if you look at the, the positive, the trust in the larger banks was 50%. If you look at the neutral or low trust of these smaller regional banks and credit unions, combine those two and it was 65%. So that's pretty stark comparison. If you look at the large tech companies, 41% feel high trust, 84% are either neutral or low trust in those smaller fintechs. So we, we've got a, a bridge that we need to create there to build that trust. And part of that is the threat of fraud, particularly on the consumer side. So the two instances of fraud that people I think are most concerned about are account takeover, when somebody actually assumes the account identity, or it could be authorized payment push. So they will trick you into sending them a payment fraudulently. So some sort of scam. And in 2022, the FTC reported 49% year-over-year increase in this type of fraud activity, and consumers lost nearly $8.8 $1.2 billion. So consumers demand protection. They expect protection. So that's definitely a trend that is not only a requirement, but, but a definite opportunity for fintechs. So they're looking at things like, of course, we all know about two-factor authorization, but biometrics is becoming more and more popular and more trusted by consumers. Of course, there's AI and machine learning. And along with biometrics, there's out-of-pattern analysis. So how many times do you log into your bank account and it says, huh, we don't recognize this device. Can you prove that you're you? And oftentimes that happens so frequently on the very same device, it becomes annoying. So the fintechs have to balance that customer experience with the protection that you expect. So that's another challenge that fintechs have. And I would like to just kind of wrap up and touch on payment trends and a concept called open banking. So payment trends. I, I know my cash usage, it has gone down to basically nothing. The decline in payment usage has gone down 20% globally as a share of global payments in the past 5 years, 20%. There are also decoupled payment options. You may not be familiar with that term. It is basically a payment method. Think of like the Target red card. So you can couple your personal accounts with this non-banking entity that you use as a payment source. So it gives you greater privacy, greater, greater security, um, less of a fraud opportunity, greater convenience. Um, so that's becoming more and more popular option. A lot of retailers are going into that option. There's also some other finance companies. And then the concept of open banking or open financial data. This is something that is a lot newer. Maybe a lot of people have used it as a, as a new fintech avenue, but they didn't know what it was called. So think about things like Robinhood. Chime, Mint. So you're giving those apps, those, those fintech companies access to your various financial data accounts. And, and this is the important thing. You have to give them permission. They can't go in and do it themselves. You give them permission to what information that you want them to have so that they can provide you service. So it's giving you more flexibility. You can govern it and it helps with things like budgeting, investing, financial planning. There's also banking as a service. There's a lot of opportunities there where you want, where fintech may want to offer a specific product, but not all the services of a bank. And financial product comparison, that's another service that we may be looking at. So there's a lot of opportunities for fintechs to, to identify an unmet need as long as they think about security, fraud protection, and increasing trust.
They do have a lot of work and opportunity. I want to go back to Dasha when you talked about the trends. I'm curious to know what would be one key trend that CEOs of small businesses should really focus on because for them it represents an opportunity?
Virginie Glaenzer, let me clarify, the CEOs of the fintech company or of small business?
Small business, so the other side of the table.
Yeah, I think, I think the integration of services is a very important thing for small businesses. If you think about, you know, On one hand, nowadays there are businesses out there that can achieve millions of dollars of annual revenue with basically one owner and a few contractors, right? To do that, things have to be automated and integrated, and you have to be able to pull it all together into a system. Basically, that is, that requires that technology is there. And a lot of the times, one of the most important connecting tissues is the financial the flow of money and the financial operations of your business. And so I think that that's one that CEOs should be thinking about is the integration of not just their financial tech, but other technology. But as Michelle pointed out, that has to be done securely. So on one hand, you have to be thinking about the opportunity for the use of these technologies. But on the other side, you have to make sure that you're approaching it with the right research and potentially the right cybersecurity consultations. Because when you're stitching together all these different services and programs, and then you have the APIs in between, you have a lot more potential for just either things not being compliant with each other or having different expectations. So that's just something to be both aware of the opportunity and the risks on.
I love that. So really what you're saying also is that companies are used to looking at their tech stack, their marketing stack, but now we're talking about the finance stack. What is your finance stack that empowers not only your client to use your services, but even the company to thrive into a whole new set of emerging technology? Thank you for that, I love that. Mindy, you— I love when you said about business in motion, which really qualifies those microentrepreneurs, you know, freelancers and, and independent. What would you say? What are the best ways for them, for those people who have business in motion to, to use fintech to their advantages?
I think they should ask their local credit union and ask their local small bank to implement what they need because that need is not being met. I, I can tell you firsthand, I now have a credit union and they lack a lot of things that I had 20 years ago. And I wanted those things many moons ago and made the assumption when I moved to the country that those things would now be in place because I had things that I took for granted like the API connection to Zelle. If I need to pay somebody, I automatically think I can just click on your name and send you money if I need to. Those things are not in place in credit unions and small banks. So the basic day-to-day affairs of doing business is not even in place. If they know there is a desire and a need for those things, then maybe they will start to realize that they need to modernize, they need to upgrade their systems and appeal to these. I mean, people today, everyone talks about how many side incomes can you have? That's not going away. So this is an untapped market opportunity for the small credit unions and small banks to step into. And if they don't step into it, the big banks will continue to seize the business.
Very true. Thank you. Thank you for that. Michelle, I want to go back and I'm sorry I have so many questions, but I will browse through some of the audience questions. But you talked about some of the growth opportunity for fintech leaders, CEOs, by looking at open banking. And one of the key aspects is to break down the lack of trust. But how do you break down the lack of trust, which requires adding another level of technology such as, as you mentioned, biometrics or two-way authentication that can complexify the transaction with this desire that consumers and everyone have about ease of use, you know, simple processes? How do we balance the two?
One of the ways that you can do that is co-branding with a more established, trusted name. So it could be that you, if you're just releasing a new capability, an API, it could be co-branded with a known entity. If it's, if you're going out the gate to, with a go-to-market, make sure that, that your security is an advanced security. Don't go out with, I don't want to call it the generic two-factor authorization, but it's been around for, you know, a decade. Go out with something that's more biometric. Something that's a little bit more it feels as advanced as your technology. Also, I would make sure that you put the, put the image in your prospect's vision that we're not a small-time player. We are looking at the future. We know that our clients are— they could be remote workers. Even though your company maybe only has 25 employees, they could be on 3 different continents. So we have the capability to not only be secure, but also meet every single one of those countries' security requirements. The UK has been very forward in their privacy policies. Asia, of course, we know has stricter requirements than a lot of other countries. Dasha mentioned that Brazil is just skyrocketing in terms of small businesses, micro businesses. Africa is another continent that is just exploding. So if you are going to have a new fintech offering, make sure that it's not something that you grow to accommodate, but you go out the door with that. So it's not a matter of, okay, well, if you're a remote worker internationally, you know, half of you can use it and half of you can't. There's also a lot of, to Mindy's point about the gatewalkers, I can't tell you the number of people I know who are solopreneurs and they're, they're Um, nomadic, uh, entrepreneurs. They, they absolutely travel and run their business. So you need to be able to meet those needs and stress the fact that you've already done the forward thought and you, you've done the research and you are compliant.
Very true. Thank you for that. So really when it comes to adapting to the new desires, the consumer desires, the business desire in the fintech, there seems to be a lot of opportunity for growth, whether it's bridging the gap and removing the fear by adding more trusted mechanism, or just being more adaptive to this 24 hours, 7 days a week purchase habits, or, or just offering different kinds of finance opportunity. I've seen on a number of e-commerce websites now the option of paying in 3 times. And so I'd love for each of you to maybe share a few other last, you know, input, idea, or stress different points that you want to make in this discussion.
I'd love to chime in here. One of the most opportunities that is just waiting for someone to seize is to really set up, even if it's a different company, a customer service department that represents those small credit unions and small banks after hours. People want people to answer their problem. They don't want a bot. They don't want to leave a voicemail. They don't want to send an email. They don't want to go into a phone tree. They want a human being to solve their problem at 5:05 PM. And so if people don't start getting those human rectifications for the problems that they're having with, with after-hour business times, they will be forced to continue to do business with with companies that they may— with banks, meaning that they may not want to do business with, but they still need that 24/7 customer service and digitization of their business.
Yeah, I think when things go smoothly, we would rather use machines and automation. But as soon as there's a problem, we want to talk to someone.
Exactly.
To be able to cry on the shoulder of a real human. I completely get that. Yeah, love that. Michelle or Dasha, any, any last— I know it's 12:37 and we originally set up for 30 minutes, but we want to give a little bit more time if there was some last input that you wanted to share.
I do have a suggestion as well. I know it's a digital world. I know it's very much an app-generated world for the smaller fintechs, but from a personal take, before I download your app, before I start using your app, my approach is I'm going to go to your website. I'm going to learn about you. I'm going, I want to see an FAQ. I want to see this is how we work. This is why it's secure. This is what other users are saying. This is how we're going to benefit your life. Here's how we're going to protect your information. Too many apps say download the app and we'll tell you. No. My mindset, and this is a personal consumer-based feedback, educate your prospect before they have to fully engage. That establishes trust.
I love that. You're really talking about transparency. We want transparent relationship and be allowed to do the research before we commit, when really the digital marketing strategies so far have been to push people to commit for free. Right. And then, yeah, so the model is a little bit different. And I think what really we're talking here is we want, as consumers or business owners, we want to get the power back. We want to control what we want to do and turn the table around. Right.
Yeah. My, my last thoughts. I'll just add to one from the app creators, the entrepreneurs out there building a new fintechs, and one from kind of the user perspective. So one of the trends we did mention is that investor-led funding for fintechs is cooling off a little bit, not as aggressive. And, you know, in, in it's, and it's a trend that you also see in other industries right now as well. So this is, you know, some of it might be the, the, the place in the industry timeline, but other factors as well as are influencing that there's the medtech industry, same thing. It's been a little bit of a cooling. So the, the thing that happens during that is that you have to be able to demonstrate that you're creating something that isn't like a copycat or some competitor to something that exists, but that you're going out and solving a real problem. And I think one of the things that happens is in the centers where fintechs are typically born, which is kind of that urban center, some of these other problems that are going unaddressed are not necessarily the front and center. And so taking a look at kind of the, you know, and it's not just rural communities. I want to bring a kind of a point to it. Michelle and I recently interviewed somebody here in Jacksonville. Jacksonville is a city of over a million people population. It's growing fast. There's a lot of industry here. It's on the Space Coast. So So a lot going on here definitely could not ever be described as a rural town. But we were interviewing the only asset-based lending institution in this entire city. And this was somebody who had been in New York where that was just a very common type of vehicle available to business owners. And then he moved to Florida and there was nothing here at all in this region. And so the opportunities to take something that is working and good, but just to extend it to a different market might actually be a better opportunity in this investing environment than inventing new things for markets that are already saturated. And, and so I think that consciousness of like where the markets are is going to be one that's very important for this stage of investing into these types of businesses. From the consumer perspective, using these tools just on the cybersecurity front, A lot of the time cybersecurity is nonetheless user error. You know, fishy email comes in, you didn't really check what the link was that you clicked. Somebody catches you off guard with a call. And, and it sounds so unsophisticated. You might think we've known about this for some time. Why would we be caught? But it's so common. You hear about these issues in Taking an Uber downtown somewhere, if you talk to the Uber drivers, you hear about the kinds of scams that go on there. And so a lot of the times the cybersecurity, there's an aspect of the technology, but there's also, are you staying secure? So I would say everybody needs to make sure they're educated about like how people do phishing and, and those tactics and make sure that they're themselves just have the basics, wherewithal around themselves to avoid those types of scams. You can't blame it all on everybody else.
Yes, and as consumer or even business owners, I think it, it requires us to always stay vigilant and know the latest scams that are working to not fall into those traps. I love the fact that you are reminding CEOs and business leaders, fintech founders, to continue to truly listen to what the market wants and to listen closely because usually the future or the next wave of innovation does, will not come from the loud people, but really from the, the rural, the small communities where these new needs will appear. So thank you. I think this is a great way to find untapped business growth and key differences differentiation for organizations. So thank you for that. So it is 12:43, and I really want to be not only mindful of your time, but I want to thank you for taking the time to share your experience and your vision. I think there was a lot of gold nuggets that we hopefully will put into a recording, but also on, on various blogs. There was a lot of pragmatic and very practical practical next step for those who listen to us. Thank you to all of us, and I would like to invite those who are listening to connect with us. Go to econoc.net, and you can also, of course, follow us on LinkedIn, Twitter, Instagram, and YouTube. And you can connect with Michelle, Dasha, and Mindy directly on LinkedIn or on their own page on the econoc.net About Us. So thank you so much, and hopefully we'll we'll do another series on continuing this leadership series on various topics. Fantastic. Thank you, everyone. Thank you so much. And until next time, have a fantastic end of week, and we'll talk soon.
Thank you. Thank you. Bye.