Life Insurance Policy Audit That Pays
In this informal, conversational interview, host Adrienne Barker (MAS) talks with Frank Campbell, the founder of Stratus Financial Partners, about his business auditing life‑insurance policies. Campbell explains why he started the company—frustration with policies that fail to deliver for beneficiaries—and describes the name’s origin. He outlines common problems in modern policies, such as incorrect beneficiaries, conditional guarantees that depend on investment returns and internal charges, and hidden premium increases. The discussion walks through the audit process: obtaining a letter of authorization, pulling the exact policy details from the insurer, checking beneficiaries, policy length, and cost‑to‑benefit ratios, then reporting whether the policy is sound (about 10% of cases) or needs fixing (about 80%). Campbell emphasizes using multiple carriers rather than a single one, and shares real‑world analogies (iceberg, gas‑mileage) to illustrate how policies can “run out of gas.” He touches on myths (self‑funding, taking a policy on someone without consent), explains STOLI/TOLI (stranger‑owned and trust‑owned life insurance), and defines bad‑faith and standard‑of‑care issues that he encounters as an expert witness. The interview also covers the growing role of AI in underwriting, the types of policies he reviews (term, whole, annuities), and his book, How to Do a Proper Policy Review, No Beneficiary Left Behind, which is offered for free via the StratusFP website. The conversation ends with Barker promoting Campbell as a podcast guest and Campbell sharing his perfectionist drive to protect clients’ money.
Chapters
to go see family. Hello!
Hello, Adrian!
Look who we have. Good. Sorry, Frank, I can't help it. It's Frank Gambles in the house, and he's going to talk from soup to nuts, and I think it's about life insurance policies. Am I correct?
I hope that's all it is. Don't ask me about soup.
So, Frank, we know a couple things about you. One, we know you're brave. One, we know you're bold. One, we're going to say you're brilliant because only smart people know how to sign up to be a guest on the No Prep Needed. And how smart am I that I don't have to do any prep at all? But Frank's got a team because they— is Frank all set for his interview tomorrow? Yes, he's all set. Wait, am I interviewing him or is he interviewing me? I got a little confused there. I sent you the wrong, the wrong link. But I am so glad that you are here, and you have to introduce yourself, and you have to tell us where you are from, where you're living right now.
I live in Riverside, California, halfway between LA and Palm Springs.
Oh, that's beautiful. And what do you do, Frank?
I set up a special business to audit life insurance policies.
Okay, how did you What, like, what, where did that come out? Did you one day, like, just say, you know, I should just audit life insurance policies? Did something happen? I want to hear the backstory.
Well, I've been familiar with life insurance for decades, and I just got tired of watching it go wrong. That was the problem. I wanted to see it done right, and that's not easy for a consumer to get. So I had this ego thing that I could put together a program that would make it simple for you to understand, cut through the complexities, and then you could make an informed decision about what your coverage is and what it should be. So I did that.
So you did that, and that's what we have for with your— so StratusFP.com, what— where'd the name come from?
My son-in-law is a pilot, and we were putting together Stratus Financial Partners, and he said Stratus is like the clouds, you know, you're going to do high-level stuff, and that's a high-level thing. So, and nobody took this, took the, the, the site, the name, so we grabbed it.
Oh, I love it. What does the FP stand for?
Financial Partners.
Oh, okay, very interesting. Okay, so I was telling Frank I really, really love going through the websites. It's fun, and I get to see what's going on. But before we do, let's just make believe we are in that elevator, and I see you, and I go, Frank, I see you're going to the same trade show I'm going to. What do you do? Why are you here?
I'm here to make sure that people have the ability to have life insurance done right.
Oh, and, um, what do life insurance agents think about you and your company?
Most of them don't like me.
I was figuring that. Oh no, Frank Campbell's in the room. Stop talking life insurance. So they— because— so you're, you're an— because it is really difficult, um, when you're looking for life insurance, who to go to. And I think in my life I've been approached so many times, but at the end of the day, I've also thought I've always— like, to me it was like, well, how long have you been in the industry? How long have you been with that company? Because I recognize that you, that you're really— in this case, it doesn't matter the kind of relationship you may have with your insurance agent. They may be flipping burgers the next day and not doing it at all. They may just like— right? So it's really understanding the company. And it's, it's in one case where I know relationship is important, but how important is it if you really don't know if that life insurance agent is going to stay and if they're answering the questions or just pushing whatever that brand is that they're trying to push.
Am I right?
Exactly.
And do they, do they look at it to see that it's the best thing for your particular situation? And many companies don't even have all the wide range of products. So it gets complicated real quick.
Yeah, that makes sense. I mean, years and years ago, I wanted to prove to myself that I think my family, like, I could get— I could be a Prime America. That was First of all, I just— I can't sell life insurance.
I don't—
I can't sell anything. But like, selling that was really, really hard. But second of all, right, like, if someone is trained by Prime America and you want a product that's sold by the John Hancock company, am I really going to tell you, oh, I don't offer that, you— I can't do this with you, I'm going to leave, we just spent 3 hours together, but that one little piece I can't do, so call this person? Does that ever happen?
A lot. And it's different now. It's— many agents have access to more than one company, but if they only have access to one or two companies, one or two companies aren't enough for every different client, for every different policy. So I represent— I don't— I'm not officially affiliated with any company. I use them all. Because if you give me your situation and say, this is what the deal is and this is what we need— oh, and by the way, I smoke cigars once a month— I name— I know 5 companies that will give you a competitive rate, but I don't know which of the 5, Adrian, is going to be the best one until I go there. So we never go to one company for your solution. We always go to multiple companies and come back with The best company with the best price.
And I'm embarrassed to say this, but I, if I was going to buy it, I'd want to buy from someone that's a little more seasoned. And I know I'm just being honest with you. You're seasoned. A young whippersnapper that may be coming in and just learning just feels like— I know for me, I, and I feel bad if that's you. I understand it's your— and you, and you have to make a career, and it may be better for you to have a niche of your own, you know, like your age kind of, you know. Because then you could talk to like millennials can talk to millennials, Gen Zs can text Gen Zs. I'm a boomer, so I feel like in this case I need boomers. All right, let's look at your website. So you sell life insurance?
I do. That's not our primary focus, but that's— we do that. Yes.
I mean, it only makes sense, right? Because all of a sudden they'd be like, well, what do you— what do you suggest? And then you would be like, I suggest my company.
I don't have to send you to that young guy with the one company. I can help you get the right company with the right policy.
All right, so you can see my screen. Let me make sure.
Good.
I'm having fun. So look at this. Yeah, I just love this. Okay, so will your insurance policy really protect you? Can you give us some stories of like where the insurance policy did not, did not protect?
Did not protect, right? That's the problem, Adrian. 88% of existing life insurance policies are never going to pay a beneficiary. And I see them all the time where, where it's like the Titanic hit the iceberg, but it didn't have to. If you'd known exactly where you were headed, you could have changed course just 3 degrees to the left and completely missed the ice field and tied up in New York on time. And that's what I have happen all the time. People call me and say, hey, I just got this letter from the insurance company. 'And it says that my premiums are going up by 180%.' Yeah, because you didn't look at it for the last 15 years, and they weren't real clear when they were explaining to you what was going on. And now the policy has gotten to the point where there's an iceberg in front of you. Uh, that's too late. It's really hard to save a policy like that. But typically 5 or 10 years before that before you get to Iceland, you look at the policies now and then and make sure that it's still doing what you want and that there aren't any surprises. And then you bypass the iceberg, you tie up in New York on time, and the policy pays the beneficiary like you intended.
So what are some of the things that, that happen?
Well, the first problem is most— first problem is It's so complicated and it's difficult for somebody to understand it unless you're able to put it into English. What's this mean for you? The second thing that's wrong is that people don't know this. Life insurance policies years ago all had unconditional guarantees. You pay this premium and we will pay that death benefit, and that's the end of the story. But about 40 years ago, they started coming in with different types of policies that had conditional guarantees, and that's where the devil is, because it says if we get 6% rate of return and if we don't raise our internal charges, which most of them are doing, and if it's smooth sailing, this is going to pay your beneficiary just like you planned. The problem is If it doesn't, it won't. And that's what happens far too often. And it's just terrible.
Do people feel that they can, if they have enough money in their bank and in their business, that they can, like, self-fund their own insurance policy? They don't need to take it out.
Yeah, but, Adrienne, why would you want to do that? Life insurance is just— we call it life insurance. You know what it really is? It's a pile of money and sitting there over on the side to come in when you need it. And, and so your money is more expensive than the insurance company's money. And most people that understand that have a lot of life insurance.
That is interesting. What about some of the myths? Because I, Frank, so that you know me, I love Lifetime Movie Network. So I'm watching all these dramas. And can I really take a life insurance policy out on Sabrina and she doesn't know about it, and then Sabrina, I get her, I get her, I get her to— bye-bye Sabrina, and now I could collect her money. Is that even like a reality?
It'd be really difficult if Sabrina doesn't agree to the policy.
Oh, so people do have to know?
Sure, sure. The insurance company doesn't want to just give away money, you know, they want to make sure that it's really real and that you're not planning on doing something evil with, with Sabrina.
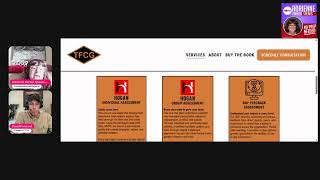
Interesting. I know that was a crazy question, but sometimes they have the weirdest things. Okay, so now we look at this, and then are you using a, like, the Stratus policy assessment without giving your secrets? What exactly are you doing behind this? Oh, see how we grade it. Oh, oh, oh, there's a picture of my husband. How did he get on here? Kidding, Alan, kidding. It's a super duper policy. Oh, I see. So you can't read anything. All right, share, share what this is. Tell us about your assessment.
I want to know exactly what's going on with the policy, all the ins and outs, and no hidden features. So if you have us review your policy, you ask us to audit it, first thing we do is get a letter of authorization from you, the owner, and we send it to the issuing insurance company and get specific information about that policy, not that type of policy, it's like your policy, so that we know exactly what that policy has. It's a little bit like lifting up the hood of a car to make sure there's really 8 spark plugs under the hood. We want to verify that, and so we get the information, and among the things that we verify are who's the beneficiary, Um, how long is the policy going to last is a wonderful question. If you're really going to live to 85, you don't want a policy that's not going to make it to 85, do you? So we verify that, we get it in black and white, and then we come back and say in the other screen you were looking at, 10% of the time we tell people Everything's good, just keep on going, you're not going to have any surprises. Uh, and the others, if there's something awry— and 80% of the time we find there is, Adrian— we help them fix it. And if we can't fix it and it needs to be replaced or they need additional coverage, then we're— then I put on my agent's hat and help them find the right coverage.
Are people still— is this for whole life or term or both?
I'm really agnostic. What do you need?
Okay, got it.
It's, uh, all the policies. And I wrote a book. We'll talk about the book in a minute. Oh yeah, I wanted it to be in English so you could understand, so I gave away all my secrets in the book. Here's what you'd look for, here's why it's important, here's what it means. And the different chapters go through the things that a layperson can understand.
I love this. But so, but it would only make sense if you're already doing this. So a lot of people would switch their policy, like, like, unless you said this policy is good, but you said 80%. So what are some of what— so what's going on with that 80%? Can you share some information on why? Sure.
What's your husband's name?
Alan.
Is Alan still your first husband?
No, he's my second.
All right.
I'm working on my third. Now I'm getting in. I got to get in.
All right. Well, maybe Alan had a life insurance policy, and after you guys got married, he forgot to change the beneficiary. So money is going to go to his ex.
That must happen a lot.
It does. That's the most common thing we see. Or the children were named as beneficiaries and they were minors, but now they're grown with kids of their own. It's a simple thing to change ahead of time, but it needs to be changed.
Interesting. What else? What else?
Let me use the analogy of gas in a car. All right, you got— you bought this car. And it says that it's going to get 35 miles per gallon, and you drive it and it gets 35 miles per gallon, then you kind of take it for granted after a while. But all of a sudden, you don't even recognize it. It's just you're going to the gas station more often because it's getting 25 miles per gallon. That's what happens in these policies when the, when the return isn't as good as they predicted, if it drops a little bit. Or the companies have the right not to change the premium in these policies, but to change their internal costs, their charges. So it's like gas went up from— I'm in California— it went up from $3.50 a gallon to $4 a gallon. Maybe you're still getting 35 miles to the gallon, but it's more expensive, right? So what happens is the ideal isn't met. and suddenly the thing starts running low on gas, and you don't notice it because nobody looks at their life insurance policies. They leave it in the drawer, and the, the fine print from the insurance company tells you that. But if you don't, if you're not in the business, you misunderstand what they say. We had a case where an agent did a really good job with a good company, and it was designed for this policy to last age 100 no matter what. And the agent did a good job of putting it together. 10 years later, we were asked to review it, and the company— this is still a good company, but they raised their internal charges, so it was taking more of the premium, right? They were still paying the same amount, it's just as much of it wasn't going into the gas tank anymore, it's going to the company. Long story short, had they not done that, it would have lasted to age 100. But once they did that, the most the policy could last to is age 85 without more gas. And when we reviewed it, the client was 78. 85 didn't seem that far off.
Wait, and were they notified?
They would have been if we'd not reviewed it. Because down the road they would have said at age 82 or 83, hey, um, you're out of gas, and then it gets ugly. I don't like ugly, Adrian.
So wow, wow, wow, wow, wow. Okay, what about— so what are the some of the things that, that, like, is it disasters? Is it, um, if you take your life? Like, what are some of the things that, that you would not receive a life insurance policy?
Okay, the first one— I, in fact, I just did a blog on this. The first 2 years of a policy, the company has the right to, if you misstated something in the application, take back the premium, but, and take back the policy. Okay, but let's say, let's say you've got, um, I don't know, some disease. You got Lou Gehrig's disease and they don't— you didn't tell them about it and they didn't find out and they issued the policy. They have 2 years to find out. After that, they're stuck with you. They can't go back and say you lied on the— the statute of limitations ran out, basically.
Okay, so how are they vetting? Do they— do they— because I know that you said They'll send out someone to take your blood or whatever, measure your blood pressure, look at everything. Are they reaching out to your doctor? What does that look like?
All of that. And but before I answer that, it's easy to avoid this. Just put everything down in the disclosures.
Be honest.
There's nothing for them to come back on, right? But now they've got all this AI, man. Technology is getting into underwriting of policies.
Seriously? Wow.
And I had a policy for a lady who was 55. She wanted $500,000. We found the right one. She paid the first premium. We submitted the application. The next day, they approved the policy without an exam, without a urine, without blood, without anything. What happened was AI went back that night and checked her pharmacy records, and it was consistent with the medical history that she disclosed on the application, and she had a healthy lifestyle. And it— whatever it is, they've got these little algorithms now. She fit the algorithm, and they went, 'Here's the policy.' I was shocked. Pleased, but shocked.
But then I've got another—
but then I have another one right now in underwriting where it's been going on for 2 and a half months. The doctor said you need a colonoscopy, and the lady's not excited about getting a colonoscopy, so she hasn't done it yet. They're not going to issue the policy until they get the results of the—
Wow. Can't you tell her to poop in a box?
I did. Well, I can't tell a lady a thing like that.
I pooped in a box. Um, that's, that's interesting. What about like a natural disaster? What does that mean when they have the clauses? So you You know, if I, if I got swept away in a tsunami here in Florida.
Ah, really, natural disasters is something that they put into auto policies and homeowner policies, not so much life insurance.
Oh, see, okay.
And Adrian, if it's done right, then the policy just says when your heart stops, we're going to pay. If you died of old age, we're going to pay. If you— you live in Florida?
Yes.
Okay. If you get eaten by a python, we're gonna pay.
And an alligator. I— okay, that makes good sense. Let's go check out— let's go play a little bit more on your site. So I want to hear your book too. Okay, so you're Riverside, Cal— I love this, guys. Love phone number right here. That's how you know. Oh, there's your LinkedIn. I'll just look at your LinkedIn really Hold on.
See, you got all this information on me. That's the way the insurance companies operate. They get all this information.
Look at this. Wait, so let's just see. Are you on here? No. Where's she— are you on LinkedIn?
I am.
Oh, but you're not attached to your own company. It doesn't show that you are.
Well, I have this wonderful tech guy and he's got a separate page for Frank Campbell and a separate page for Stratus Financial Partners. You're on the company page.
Right, but that should show that you're an employee. That's weird. Let's look at you. Hold on. So you are a lot of Frank Campbells.
There are—
hold on, Frank. All right, here you are, dapper. Oh, I love this, I love this. May I just connect with you? Do you mind?
Certainly.
Okay, let's just do that. I'm not going to send you a message request, I'm just going to send without a note. You'll know who I am, but you are on here and you're here, so why are you— oh, maybe because we're not— I don't know, it's weird though. Weird, weird, Frank. I don't know why that is. That seems really weird to me. Okay. I, it's just me because I love LinkedIn and I'm on LinkedIn and I teach LinkedIn and I'm like, why are you not? Um, okay, hold on, I'll show you something really fun though. Go back and tell right here. Oh, you— okay, don't worry about it. Oh, are you— oh, what, you were in Buffalo?
You went to, um, I can't remember what the SU State University in New York at Buffalo.
Were you born in Buffalo?
Nope. I was, uh, fortunate enough to be a crew member on a submarine for 3 years.
Oh, thank you.
We surfaced outside San Juan, Puerto Rico, and went in, and I met this girl from someplace called Buffalo.
Oh my God, I love that. Wait, why is your book here? I don't see your book. So tell me about your book. Is it on your website?
Um, probably. But I'm not in control of finding it here for you.
Um, oh, are you expert? What do you do that a lot with expert witness?
That's an increasing piece of my activity. Yes.
Oh, now that's got to be exciting, you know, enough.
It's really interesting. It's good.
Wow. So look at this guy's life insurance annuity annuities. Okay. That what are they the same thing? Annuity and annuities?
Yes. I guess I can do one, or I guess that means I could do one or many.
You know, it's so funny, my, my tagline was a second set of eyes for your business. It's so funny, I will catch everything else, but I'll never catch my own. Lapse. Okay, so what a lapse insurance, life settlement, renewal, conversion, estate planning, huge disability, long-term care, bad faith. What is bad faith?
Bad faith is where somebody says that, uh, uh, that's going to get done when they know darn well it isn't, whether it's a company or an agent or whatever.
Oh my gosh. Okay. So someone who hides the paperwork underneath in a, in a drawer somewhere and never pulls it out.
That's it.
And just to keep saying, yeah, we're working on it. Oh, let me check. It's in process. Okay. Beneficiary, trust needs a capital there. What's STOLI?
Stranger-owned life insurance.
Is that like what I was saying, like when someone owns a life insurance policy on you?
You know, about 15, 20 years ago, that was a big deal for a while. You could— you had an existing policy and and you could sell it and buy another policy that was less expensive. Or companies decided it was a good investment, and so they said, 'Here, you pay for this policy for 1 year and you'll have free insurance.' And they didn't have a relationship with you or an insurable interest.
Wow, wow.
And but you signed because they were going to give you $6,000 to do it. And it was, it was bad from the beginning, and companies didn't realize it right away. Now, I don't know anybody that can do that.
So we drop the ST and we go to the TOLI.
Yeah, that's Trust-Owned Life Insurance.
Oh, okay. All right, got that.
So the policy's inside a trust for whomever the beneficiaries are of the trust.
Oh, understanding. Standard of care, is that almost like, um, like, uh, what do they call it with your— with health?
Well, standard of care means, um, are you getting the service and the information that you should be provided with, or are you— are they hiding something?
Okay, got it. So kind of goes with bad faith, standard of care. Okay.
Yeah.
Okay, I was thinking something completely different. Expiration, misrepresentation.
These are really— these are really the things, uh, Adrian, that, that the areas that I look at as an expert witness when I'm, when I'm needed.
It's so cool. Or the policy analyzers. I'd love— I'm sorry, I'm just loving this. Oh, let's look at the testimonials, and then I need to get your— the devil right here is so funny. Oh guys, look at TS client. Frank is a phenomenal person who deeply cares about the clients he serves. I had the great pleasure of engaging him for my mother's life insurance. Did an excellent job with understanding my mother's needs and finding the best policy to meet her needs. That is awesome. Look at all the— wow. Oh, Frank, you guys add yourself to the list by working with Frank. All right, let's talk about the book, Frank Campbell. Is it on Amazon?
It is on Amazon. It's entitled How to Do a Proper Policy Review, No Beneficiary Left Behind.
Oh, okay.
And that's my way of putting it in English. That's Frank D. Campbell. But here I got something better for you, Adrian, because, um, let me find it here.
Oh wait, now where, where are you? Are you— what do you— are you going to find— you're putting in the link?
I wish I could.
Let me see.
Campbell, put in Frank M. Campbell, maybe it'll pop up.
Okay. Oh, Frank M. Campbell for good.
Um, there's a—
there we go, I got it, I got it.
There you go.
Okay, beautiful.
Um, if your listeners would like a free copy, they can go to our website and request it. It's StratusFP, um, /freebook.
And oh, oh, I like that. Oh, okay, okay. So just hold tight, let me just take care of myself because I'm all that matters. Okay, I got it. Literally took me like, I think, 3 seconds. Oh, I have to confirm humanity. Which I do have to leave. I'm a guardian ad litem and I have a, uh, a meeting. Okay, so let me see here. So I love this. So let me go back to the free book so I can— okay, hold on, let me go back here. Let me go here. I just want to put the, the thing. Frank, is there anything that I should be asked, that I should have asked you that I didn't ask you? Anything you want to share with us?
I'm a recovering perfectionist, Adrian, and I hate to see a policy that isn't going to do what it's supposed to do. But if I get all technical, it's— nobody's going to get excited about it. But if I talk about the fact that it's money and we want to protect it, and here's the easy way to understand what it is and what it does, then I've done my job and you can make an informed decision about where you are and where you need to be.
Awesome. Okay, boom. Boom. I love that. Yeah, you seem like just such a wonderful man. I love that you're doing this. I, I thank you because I find this really fascinating, and you helped answer questions. And I hope some other people get, get the free ebook. Get the free ebook. I'm gonna get it, and don't think I'm gonna just like read it out loud to you on my show. I'm not. You got to get your own book. This one is, I'm going to read it. It's only for my phone, or or computer, wherever I decide to read it. Thank you so much. You've been so lovely.
Thank you for allowing me to be here, Adrienne, and I appreciate the chance to get the message out. Thank you.
Oh, let me— one more. If you're a podcast host out there, yeah, get Frank Campbell. If you're smart, reach out to me. I'll give you his information. Go to matchmaker.fm, get his information. Just book him. Book him, Dano, on your show. Frank's a nice guy, and he's very unique and different the way he's doing this. This is presented in a very unique way. Frank, you, you need your own podcast. I got the man for you with your podcast, Seth Green from Market Domination. He would really, he would really— he's good, he's good. He is a smart guy. All right, but anyways, thank you, Frank. It was nice talking to you.
It's a pleasure. Thank you again, Adrian.
You're welcome. Have a great rest of the day.
Thank you for making it better.
Oh, you made it better. Thank you so