Meet Cash Flow Mike
Cash Flow Mike, a former state trooper, built a hotel-staffing company that nearly collapsed from cash-flow gaps before a line of credit saved it. He teaches the core rule: match operating expenses to changes in gross profit. His mission is eliminating cash-flow failure for small businesses through apps, coaching, and books.
Chapters
We are back and we're live, and I wish I had a lot of green because we're talking money. So everyone, who is brave? Who is bold? Who is brilliant? Who's handsome?
Who—
oh, if you're, if you're listening and you can't go, run, run to a computer to look. He's handsome. This is Cash Flow Mike. I don't know anything about Cash Flow Mike, but I'm excited to hear his story and how he got his name. So Cashflow Mike, you have to introduce yourself 'cause I'm clueless on who you are.
Hey, so live from San Antonio is Cashflow Mike, right? So here we go. My name's Mike Mylan. You know how to pronounce the name. You were the first person ever that came up with that right off the bat. You're like, boom, I got it, right? So if you wanna know how to pronounce the last name Mylan, just remember the song, right? This land is your land. This land is mine. Yeah, yeah. So, and it's a fun thing, but Cashflow Mike is the one that always gets me the attention, right? Right? And I didn't come up with that, actually. I teach at the Graduate School of Banking at the University of Colorado, and one day I'm walking down the hallway and some bankers are sitting there because I teach bankers at the graduate level. And they said, hey, there goes Cash Flow Mike. And I go, hey, are you making fun of me? I said, no. He says, you're the first instructor we've ever seen that doesn't talk about profit all day long. You just talk about cash and how important that is in your business. And I don't know what, what it was, but that name stuck in my head. And I'm going, that's it. That's my new brand.
Amazing. So first of all, so you are teaching bankers, and then their goal is to work with their business customers on, you know, getting cash for their business?
Yeah, it's kind of something I do in the summers. I teach at the executive level in the summers at the Graduate School of Banking. So I teach small business bankers how to strengthen their relationships with businesses in their community. Right? So that's basically what we're doing there. A full-time job is I teach accountants, advisors, business owners how to maximize cash in a business using a lot of the strategies that bankers use.
So what I find is fascinating is, first of all, I'm going to just ask the question that everybody wants me to ask right now. I can tell what it is. Wait, is— are they wearing like suits and ties on a Saturday and everyone's sitting there like—
no, believe it or not, tell me. They'll be like 45-year-old guys in here acting like college kids, right? They got their hat backwards, t-shirts, shorts, flip-flops, you know, bringing their little hydro flask in. It's more like a college environment. It's like they went right back to college. They even make them stay in the dorms, right? They're there for 2 weeks in the summer, uh, and then all the rest of it's online throughout the year. But they're there for 2 weeks, so they stay in the dorms, they eat in the— in the— I almost said mess hall from my military days, but they eat in the— whatever— the dining hall. And then, uh, yeah, yeah, it's, it's a college atmosphere.
So this is so interesting. So you— so tell us about your education. Who are you really, Cash Flow Bank? That seems very high level. You're teaching, and I am now just, like, itching to just hear every— you guys, like, take notes. Go. Let's give them a second. Go get your pad of paper because I have a feeling we're all going to learn and we need to understand. This is so important. So, okay. All right. You got it? You got your paper? Please start. Start from your 5-year— no, but, like, so did you know, like, is this your first career path? I have to know everything.
No, no, no. I'm probably like all of our listeners here. I'm messy, right? It's a messy life. It's a messy path to wherever we get. But it's a path. And, you know, believe it or not, I do have the piece of paper as an MBA from Baylor University here in Texas. So that is the formal part of the education. But that's not really where I think I learned the most, right? I've built 14 companies over the last 25 years. But my first job, where everybody gets really confused, is I was a state trooper in St. Louis for 7 years.
Hold on, I gotta pick up my drop.
Yeah, right. You're like, oh, wait a second, you're casual, Mike. You were a state trooper? Yeah, I thought when I came out of college—
before your military—
uh, all right, so my very first college experience, I went to a military academy, right? So for an undergraduate. And so I went and did a few years in the active and then transferred to the National Guard. So when I was in the National Guard, uh, for 16 years, I was also a state trooper. So, National Guard, you can do those at the same time. Here's what happens after 7 years as a state trooper, right? And you're starting to grow a family. I had my third child, my third daughter, and I'm looking around like going, hey, we're gonna have to start cutting positions here or something. Like, from now on, every child position is performance-based. So, those people that don't clean their room, those type of things, we're gonna have to, you know, lay some folks off, right? Because literally my family outgrew my income. That's basically what happened. So like I'm writing a student loan check and I'm like going, what the hell am I doing? So, you know, I need to actually go use this degree, use this thing that I'm paying for on a regular basis and get into business. So I started a janitorial company and left the highway patrol. Wow.
So let's just take a second, please, to first of all, thank you for your sacrifice and sorry for everyone that in wherever you were located. I feel bad that they didn't have you on on the, the force to protect them. So you made that decision. Wow. But that, that goes with why I always think that, I think the police and the military and first responders should be paid what we pay the sports. And I think the sports should not be paid as much because they're not running into buildings, risking their lives. So anyway, sorry. Thank you for your service.
You know what's interesting though, is that I can look back now. I couldn't for a long time look back and see a common thread, but now I can see the thread that it's always about serving others. I mean, even with what I do now, you know, teaching business owners and people how to do these things, it's all, it's all been a lifetime of service. And I really appreciate that. So thank you. Wow.
Okay. So now, so let's get back to the story.
Yeah. So, so I started a janitorial company and because remember, as a state trooper and being in the military, the only skill you really come out of those jobs with is you can clean.
You are so funny. But it's not like Oh, I'm going to start a janitorial business. Like, like, how much time did you take to actually decide that that is where you were going to go? Like, what made you even go to that path in that part of your time of your life?
Uh, I, I don't know. I— it was the only idea I could come up with, and I didn't have a lot of money to start a business with, and that didn't take a lot of money. All I had to do is go, you know, try to drum up some business and go in with cleaning materials and, and start cleaning. Uh, and it was going well, right? I did that for about 3 years until one of my clients was running an— you remember, we used to have to go to the cable office and pay your bill or get your equipment, those type of things. Well, one of my clients ran one of those offices and then became the general manager of a hotel. And this is where everything changed, was he says, I can't hire your cleaning service, but you never seem to have a problem hiring people, like recruiting and getting people to work for you. Can't I just hire your people? And all of a sudden, you know, bells went off. I'm like, oh my gosh, I don't have to clean. I just have to get people to work and your managers make them do all the work. And I just— all I gotta do is drop them off. So yeah, so we changed the janitorial company and morphed it into what's called a hotel staffing company. And that's when my whole life changed and I ran into problems and learned all about cash flow, uh, because that company took off because nobody was niching down into just hotels and providing people. What year is this? This is 2003.
OK, thank you.
2003, yes. I mean, a long time ago. But, you know, 2003, this is what I didn't realize, that you can be so successful that you grow broke, right? I became a preferred vendor of, of, of Marriott. And all of a sudden, every Marriott in St. Louis and then beyond was calling me to provide them with staff, right? Because we became the accordion part so they could keep a smaller full-time staff. And when they were full, they would call me. And when they weren't full, you know, they wouldn't need me. So we opened 27 offices in 9 states in 3 years, right? Had a few hundred people working every day. And that's when I ran out of money. You're like, oh, what? You're like, oh yeah, on paper I was rich, right? In the bank account, I was nothing. Because Marriott had this thing where they wanted to pay you every 60 or 90 days. Well, I got to make payroll every 2 weeks, so every dollar I had and home equity line and maxed out credit cards and savings accounts went to the employees until I could get paid from the hotels for the very first part. So there was a, there was a thing called the financial gap. That's the difference between money coming in and money coming out. And your working capital, the amount of money you have, should be able to cover that gap. Mine didn't. That's where I learned all about how to manage the levers that control cash flow.
Okay, so that— this is such great advice. That— so what was your only option? Did you have any options? What did you end up doing?
Yeah, uh, I actually went to the bank, uh, this is 2004, '05, somewhere in there, and I said, hey, listen, I've got all this work and I can't keep up with it. They go, oh, well, you don't have a line of credit. They go, what's a line of credit? You know, like we all would, like, what do I use that for? They say, oh, that, that's what you use. You draw on it to make your payroll, and then as your customers pay you you pay down the line of credit, right? You just pay back the payroll that you would already pay. Am I going, what? How come nobody told me this? I just thought I had to have all this money in the bank trying to run it. So once I learned how to use a line of credit, which by the way you can get into a lot of trouble with when you carry a balance, because there's a rule on lines of credit. If you go out there and I want a line of credit, well, the rule in line of credit is you have to pay it down to zero at least one time per year and let it rest. And what they mean by letting it rest is don't draw any money on it for 30 days. So think about that. So, and that's how you keep in the good graces of the bank, because it's only used to meet the demands of what you're selling. So I— you use it to buy your inventory, and then once the inventory is sold, you pay down the line of credit. Or you use it to meet your payroll in a service company, and once your customers pay you or clients pay you, then you pay down the line of credit. So if you get into that habit really early, you don't get in trouble with the balances and where they take it away from you.
Interesting. And that probably is happening a lot, maybe in today's economy.
Yeah. So what's interesting is that about 60% of folks right now that have either lines of credit or they're using debt have used it the wrong way, right? Because nobody really teaches you. There's not even an MBA program at Baylor. They say, here's how you structure debt in a small business. Nobody says that. You just, you patch it together the best way you know how. I just need money from here, so I'm maxing out credit cards and those type of things. Well, there actually is a proper way that makes it easier to run your business, and about 60% of people don't do it the right way, uh, and it's costing them thousands of dollars probably per month in interest. Uh, I, I call it mismatch financing, and what that means is, is that you're using the wrong loan product to buy something.
Oh, that's so interesting. So that's a key, really. So when I'm listening to you and also from some of my experience, I was the chairwoman for SCORE, S-C-O-R-E, and we noticed that a lot of our company, the businesses that we were mentoring, they didn't understand the importance of having a relationship with a bank. They just thought that that was something that, you know, they look at the statement, maybe they drive by and make the deposit, but that they, you know, maybe they knew Carol who was their teller and they, you know, gave her a cookies sometimes, but they didn't really understand that and teaching that. And that always struck me. That's so interesting. Can you go over like that you can have a relationship and how to actually start that relationship?
Yeah, what's funny is that over the last 25 years, I've seen the evolution of banking, it seems like, because early on, right, we'll say early 2000s, the average business owner would go into the bank about 22 times a month. Right? They'd make deposits and stuff like that. Now you're lucky if you go twice a year, right? So it's, it's harder to build those relationships because you don't look at the banker as anything other than somebody that fills out your paperwork, right? It's really what you think. You gotta remember in 2008 when the bankers burnt the world down. You remember that?
I do.
That's when people stopped listening to the banks. It used to be that when you started a business, you needed the help of people, right? You need an accountant, a lawyer, and a banker. What, 2008, the banker kind of fell off that pedestal with the business owner, and now bankers don't even rank in the top 5. They're actually ranked 7th of people who I go to for advice. 7th.
Oh, that's so— oh my God. And I was always saying around your table, you have to have a banker with your accountant, with your attorney. Wow.
Yeah, yeah, it's, it's actually— I mean, this is what banks are trying to get back into that community banking type of thing or style. What's interesting is, you know who number 6 is in the survey that I've done? You know, because I teach and do seminars around the country. Other. People will choose other. They would rather go to the bar and ask the guy next to them at the bar, say, hey, let me ask you a question about my business, than talk to the banker, right? So bankers rank behind other on my survey.
I don't even know where to go with that. That is so interesting. So, so We talked about the value of having that relationship. Can I just— I'm going to just be like open and ask these questions. Are banks the only— like, in my mind, banks are not the only place where you can get business funding. Am I correct? Are there other— and I'm not talking like credit union or SBA banks, but are there other outlets out there for cash flow?
Oh, of course. Right. And it goes back to 2008 was the explosion of all these alternative or marketplace lenders, right? You've seen it— Cabbage and OnDeck and, you know, all these other bigger companies. They're bigger now, but in 2008, the banks had to leave the small business market, and, and the small business lending market dried up for traditional banks because, uh, of— what was it? That Sarbanes-Oxley, it's the other one, one of the regulations. I— it slipped my mind right now, but one of the regulations made it just as expensive for a traditional bank to give a $5 million loan as a $50,000 loan. They had to do the same amount of paperwork. So big banks said, hey, we're not going to do all that for that little money, and they moved upstream. Well, that's when the alternative lenders came in and started giving out all these small business loans. And now what's happening is those have become big business, billions and billions of dollars per year. So the banks are trying to get back into the market.
Oh, so yeah, so, oh, that's good information because I, I know what you're talking about, but I didn't put two and two together, and that the name of it is they are marketplace lenders.
Yeah, it's, it's, and sometimes they're even crowdfunded, right? I mean, we're, but marketplace lender, marketplace lenders are just not banks, right? Uh, they don't really have a banking, uh, registration or a charter, I guess. I think it's a charter they get, uh, but they can lend, they can lend out money.
Okay, so I want to go through your website, but can you explain Do banks have— where's the Fast 50 offer from?
Uh, I don't know. I don't think I'm familiar with that. What is that?
I'm not sure either. I heard it the other day. I want to go through and I want to make sure that I understand because I want to double-check and know that I know. So, okay, so you clearly have all of the education and the experience and the wisdom to actually work with accountants and consultants. I love this. Why don't you have a podcast that's really more all your education instead of your fun one?
Well, it's a little bit of both, right? It's Mike and Blaine Business Beer and BS, right? And yeah, so it's, it's what we do is we pick a topic, a topic that's usually something that he or I are going through that week, right? Like the one we just did was cost cutting. You know, expense control, those type of things. So it's always something about business is the main topic, but we introduce a local craft beer at the beginning. We have beer sponsors that buy us a beer. And then BS just kind of comes in because sometimes our stories trail off.
OK, I love that. Oh, so you— so, OK, so tell us, so I see here a membership subscription model or membership model, which I think is great. Okay. So now let's talk because actually I do have in my LinkedIn feed a lot of exactly your target market, right? The accountants, the financial wealth advisors, even the attorneys. Tell me about this program that you have.
Yeah. So I, I've authored 3 books, right? The first book was Don't Be a Dumb Business Owner. And dumb doesn't mean unintelligent. It means I don't understand my business. So I created this program called the Clear Path to Cash, and it's 8 steps to maximize cash in a business, right? So it's 8 different techniques that I teach. Now, I've, I've built 14 companies. Some of that was in software, right? So I've built some software products that are used by banks. I've built one of the products called Cash Flow Tool, which connects to QuickBooks, stuff like that. But currently what I did was I built a product called the Clear Path to Cash, and it's an app, right? The Clear Path to Cash is an app to do these things for you. Well, here's what I noticed when I built the other products, is that I had to change the way I approached software from the financial management aspect. Because there's a lot of people just— it's, it's so deep and it's so wide, it's such a big topic that people get lost, uh, in how to do it. How do I analyze my financial statements? How do I you know, understand what these ratios mean. So I couldn't just produce an app and say, here, buy the app, because everybody would get lost. They go, I don't know what that ratio is. So I had built a membership because I have video courses that teach you what the app is doing, and there's live coaching. So about 15 times a month, I have— I'll call it open office hours, like a professor— but I either help you through something that you're working on real time, right? Like, you have a client, you have a business problem, or whatever that is, And if not, I teach, right? If nobody comes to the table with something, I'll go ahead and teach just the same way I do in the colleges.
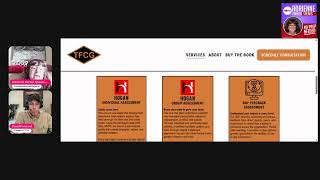
Amazing. I love this. Okay, you guys. So here is the Clear Path to Cash. So you can look at it right here. Love it. Really. And so professional how you have this. Of course. Oh, here we go. Don't be a DUMB business owner. Is there— is DUMB mean— what is that acronym for?
Yeah, it's, uh, don't understand my business.
I can't. I just can't. Like, I want to marry that word. I love that.
I—
give me— everyone write that down.
I—
good for you. That is so awesome. I love that so much. Wow.
Wow.
Okay, so working one-on-one with you, I am so grateful. Thank you for your time today. I really appreciate it. You know, I mean, everyone is lovely, all my guests, but you're like kind of like a wow wow.
Wow, thank you very much. Appreciate it.
This is really— your prices are great.
Wow.
So you, so you really will help the small or the business understand where they are with their cash flow, help them to create— will you also help them with their relationship, their banking relationship?
Yeah, there's one of the lessons in the course is called How to Deal with Your Banker. Right? So, yeah, so that's actually one of them. So, yeah, you get the one-on-one. Most people do the membership because they're not afraid to do, you know, the group coaching, right? Which means you jump in when you need me. And it's all included in that price, and it's less than the one-on-one price. Plus you get the app and the courses for the membership cost. And I think the highest one is $299 a month.
Can't beat that. But there's also something with group coaching because often you may, there may be questions that someone else is asking that you didn't want to ask because you were uncomfortable, or someone may just ask a question that you didn't even think of, and you're like so grateful, right? So I find that group coaching, that's like the beauty of it is that you've got other influences that are kind of making you think other ways. So I, I'm, that's amazing.
I think my, my program is as tight as it is because of the group coaching, because there's always something. If you're out there as an adviser or coach, you're trying to do this, listen to the community because they will plug the gaps, you know, wherever you're missing, you know, the critical piece, they'll plug it. Yeah, what you're looking at there is the counter of how often I'm available to the community.
Wow. Oh my gosh. Wow.
So you—
so interesting. So along with all the cash, you know how to market your business too. I love this. I think this is amazing. I'm like so blown away. And I know everyone's all jealous. They're like, wait, are you saying he's only got 4 tabs up there? Yeah, he does. He's kept it tight. So when you talk about being tight like that, this is exactly what you get with the website too. Check out the community. So there's literally 4. So it's cashflowmike.com and then I love it. And then there's a wall.
So in order to go log in, you just got to create it because you got to create the profile, right? If you go in there, it looks like a Facebook feed, but it's just us. It's just our stuff, right?
I just think you are so amazing. So what is your goal actually? To, you know, going on podcasts. What are your thoughts on why you're doing this to teach us, to have us share, have small businesses have options?
You know, every company should have a mission. My mission is to eliminate cash flow as a reason that businesses fail, right? So I mean, I want you to fail because the product doesn't work, the market doesn't want it, or you and your partner are getting in a fight. I don't want you to fail because you run out of money, right? And the only way to do that is to connect through accountants, advisors, and podcasts, right? To get the word out to as many people as I can that, uh, of course, I, it's— I'm here to actually solve the cash flow problem for small businesses.
And books, guys, remember the book. We're not going to forget that book because we love the title. Okay, so, so this has been a really a wonderful conversation. I also think— I, I don't know, like, my parents started their business in 1955, and growing up, all I heard was, you know, the credit rating had to— it was 3A1, I think, in Dun Bradstreet back in the day, the best credit rating in it. And, you know, my mom was always like, you always pay your vendors first, you never pay yourself first. And, and, you know, even, you know, in the business, it was always like our accounting department was the most important department because that's where, that's where you need everything to happen before you can even make a sale. So a lot of times I'll say, well, what do you think the most important business, most important department? And people will say, oh, definitely sales. And I'm always like, I don't know, I think it's your accounting department. I don't have one. Like, yeah, that's fine.
Yeah, yeah.
Go with that.
That's fun. Well, you know, you mentioned the credit scores and things like that. I mean, I, I reached a milestone I've been trying for 40 years to hit, right? You know, I'm just now 55 years old, and maybe it's the age that did it, but I, I got the perfect FICO score, right? Uh, an 850. Am I going— and guess what happened after you get the perfect FICO score?
You get like 100 pieces of mail like every hour.
Now you get nothing happens, nothing changes. So it didn't really matter. Yeah, nothing happened. And, and now what's happening is that the, you know, I heard a— you've heard of Dave Ramsey, right? I heard a, uh, a little, yeah, a little snippet from him the other day. It was on Instagram or something like that, and he was talking about how his goal and what he has now is a zero credit score. Right? I'm like, oh, maybe that's my new, new thing. Because he, he just does— he uses cash, right? So he uses cash for everything. He doesn't use credit at all. So he has a zero credit score because after, after a while it degrades, you know, because then he started closing accounts and those type of things. Here's what happened to him though. He tried to rent an apartment for his daughter and couldn't. He got turned down to rent an apartment because he had a zero credit score.
I have to look into that. That's so interesting.
It's crazy. He had enough money to buy the apartment complex, right? But couldn't rent one.
That is so interesting. And like, so I belong on this app called Chatter Social, and I love the app. And, um, and Grant Cardone— I don't know if you know who Grant Cardone is, but sure, he comes in a lot with wonderful advice. And so does Cindy Stumpo, um, an amazing woman out of Boston, Mass. Just, I, I mean, I'm so impressed by her. She is like the number one woman female, um, developer. So if you look up Cindy Stumpo, and she's beautiful, but when they come in, they give such amazing advice. So I know we'd love to have you on the app to give your advice too, but we're— so besides the coaching, do you have any other, like, is, like, besides your book and your podcast, any other Advice if someone feels like I'm doing everything correctly, I really don't need to be told, who can come in and like double-check that when you feel like I'm good, I'm good. Who's that checker?
Uh, who's that checker? I mean, you can actually do it yourself, right? I mean, it's, we all kind of need a coach to kind of make us make sure we're on the right, uh, the right path. But I'll give you a rule. The one rule I say is the most important rule of any business, and I call it just expense control. Right? And what expense control is, is that first of all, I mean, when I look at somebody's income statement, their profit and loss statement, sales doesn't matter to me. You can make money at any sales level, right? So sales is only a measurement of how much work you did. That just tells you how much you did. Gross profit is the most important number on the income statement. That is the only place you can get cash to pay for your expenses and put in your pocket. So manage to gross profit. So here's the rule: Gross profit is the amount of money you have to spend, right? Operating expense is how you spend it. If you have less money to spend, you should spend less money, right? Spend less money. So, so the rule is this: when gross profit decreases, reduce operating expenses by the same amount. So if gross profit comes down by $10,000, reduce your operating expense by $10,000, and your net profit will be the same no matter the sales level. So that's one way to do it. If you violate that, you're just paying to go to work, right? You're actually taking money out of your profit to keep this business afloat. So it's one of those things where you got to learn to live without some stuff. But if you can do that on a regular basis, you'll make money and your life would be a lot easier, uh, no matter what happens to your sales and what happens to the economy.
Great advice. I mean, that, that is a great close. I, I thank you so much for your time. You have been so helpful. Do, um, one last question. Banks, when you're starting out in a business, and I know how difficult it is if you're a new business owner, but how important is having your— my God, it just went out of my head, help me here— your business plan? What, like, do they look at that? Because with SCORE, we've always been told— I'm no longer a chairwoman or mentor with SCORE, but that was always something that we would say, well, you know, you don't need a business plan, but if you— if you want one. But if you, if you're going to go to the bank, they want a business plan. But is that still the case?
Yeah, I think the only real use for, uh, we'll say the 40 to 80 page business plan that people think about is, is really if you need to get money or you need to, you know, you're trying to, you know, attract investors or work with a bank or a venture capital firm. That's, that's the need for it. They need to be able to look and see, does this make sense, right? Does, does the idea make sense? And the business plan kind of backs that up. For most of us, we don't need a business plan. What we is this thing called the Lean Business Model Canvas. It's a one-page, right? It's a one-page thing. It identifies the two most important things on there for me is key resources and key activities, because that tells you if I don't have these things and do these things, I don't have a business. So a one-page Lean Business Model Canvas actually gets you off and running in any business.
I hope you guys took these notes. I am jealous of your students. I'm jealous of your numbers that they have access to you. I think you are amazing. And just thank you so much for being here today. Is there anything I didn't ask that I should have asked?
I don't know if you got crazy energy, man. I just, I just feed off of it, man. This is, if people are not getting on this podcast, they should. I mean, I'm telling you, I mean, just, it's a great banter. It's great energy. Really enjoyed it. So thank you very much.
Oh, thank you. I know it's weird. It's weird. I'm 63, but I really don't feel it at all. And most people have to explain things to me like I'm 9, so, you know. But thank you, I appreciate it. And I'm up late at night doing true crime, so wow, I just love it all. I think if you love life, right, then you're happy. So thank you, this was great. I'm gonna end the stream, you guys. Get on the website, Cash Flow Mike. Thank you so much. Well, okay, I will, um, you know what