Meet Sue Schuster
Sue Schuster, a Montana business financing broker, works with over 50 lenders to match small businesses with loans for equipment, growth, and SBA programs. She explains how rates depend on credit scores and business tenure, why separating personal and business finances matters, and how to spot low-quality lenders.
Chapters
We're live. So guess who I have next? Sue Schuster. Did just find out, I asked for the website. So lending, I'm all about lending money, so I know I have a lot of questions. We're not live on ChatterSocial because I don't know if they're glitching with me today, but Sue, I'm so excited to have you on Adrienne Barker Speaks. No prep needed. You know what, you have to be brave, you have to be bold, You have to be brilliant. You don't have to be beautiful, but you are. And all of those combined, it makes a great guest for me because, you know, I don't know who you are. So I'm really excited to have— let me highlight you so that the rest of the world can see us. Sue, introduce yourself.
Hi, I'm Sue Schuster. I'm from Hamilton, Montana, and I am doing business financing. So I have a strong record in growing a business. I have an echo.
Is it me? While you're speaking, try it now. I'm going to mute myself, see if that's the problem.
Okay, is that better?
I didn't hear your echo the first time.
Okay, good, good. So mute yourself because that's where the echo's coming from. All right, I gotta try again. I'm Sue Schuster. I am from Hamilton, Montana. I am a small to medium-sized business lender. I work as a broker, so I hear what the business needs. I need money. Okay, great. Let's figure out the right type of money to get you. Is it a loan? Is it private equity? Is it SBA? Is it a term loan? Do we just need something for a short period of time and we need a bridge loan? All kinds of different options. So I come from the small business world where I have worked in my own small business for 18 years. We built it, grew it, sold it. So been there, done that. And back in the early 2000s, there weren't coaches, fractionals, and everybody else. You figured it out yourself. Now it's like way easier, and it's way easier to get in front of people and network with more people, because before COVID um, you had to go to your chamber and you had to go to your meetings. Now you can just get online and talk to like 30, 40 people across the US and anywhere else in the world, and you can talk to a lot of people. So I think it's a great time to grow our companies, to learn about stuff. And whenever finance is a problem, which it usually is at some point in the business, then they contact me.
So, okay, I think I got rid of the echo cancellation. So, so first of all, I want to say to the speakers, Sue only— like, Sue's biggest problem right now is she looks so young. So we can't judge people by how young they look. So if you come on, don't think, oh my gosh, she looks like she's 18. She's been in business for 18 years, not that she's 18. So you're like a Doogie Howser but in the financial world.
Well, when you come from the swim school— yeah, the echo's gone. When you come from the swim school world, I think it's the chlorine. I think it keeps you young. But yeah, no, my youngest child is 19 years old, so I just said to Sue, her photo on the website, which is—
you can see it in the notes, uh, I thought there were siblings. I know that's unusual, you get your siblings in there. So, you know, the husband looked like the older brother though, I just want to say that.
Okay, so he doesn't have any hair. True.
Okay, so this is fascinating to me, and I was a SCORE mentor for 8 years. Oh, yay, SCORE in the house! Where are you located?
I'm in Hamilton, Montana, but when I was a SCORE mentor, I was back in Pennsylvania.
Okay. And I, I did 8 years, 3 out of Tucson, Arizona, or maybe 5 out of Tucson, and then a few years here in Daytona Beach, Volusia County. So I understand the relationship and the need. So, and I remember at one point we were looking at like talking to the bankers to make sure that there was a relationship and what the bankers need. So Let's, let's do this. Let's, let's talk about, first of all, the lending side of it. As far as the business, like you're having your business or becoming a lender, are these days, are you able to become a lender? Like, what do you need to even be a lender?
Well, I mean, I'm more of a broker than a lender, so I listen and then take them to the right lenders. So, okay, this is— in personal are different. Like, if I was a mortgage broker you need all kinds of certificates and everything because you're on the personal side. But when you are a broker for businesses, um, you don't have much of that. And a lot of the businesses just go to their bank, and sometimes they don't fall into their bank's box. They haven't had this many years in business, they haven't had the right— they don't have the right FICO score. They do have a relationship with the bank, they've had the banks— like, the banks had their business for, I don't know, 5, 10 years, but they still don't qualify to use the bank for whatever they're using it for. That's when I can help millions of small businesses out there that don't fit in the bank's box.
Yeah, that's so fascinating that nowadays— so, but you still have to have your relationship with your lenders, right?
Of course. Of course. We have over 50 lenders that, like, you're talking about equipment financing, we're going to somebody. You're talking about trucking financing, we have about 4 of those. You're talking about SBA loans, there's a bunch of people, and then a bunch of other people that just focus on that so we can get it through faster. And growth term— yes, we have a bunch of people, um, who are in the lending space, and that's why I hear the story and take them to the right set of lenders to get them the best rate.
So let's talk about how to actually find someone, a broker like yours.
So you're—
look, you, you need money.
You, you—
Sue, today is a weird day. Do you know something? Today it's 3:30 and I have not gotten one AI caller asking me for lending. Is that weird? Usually I get like, like 5 to 10, and, and then they leave the voicemail message, like out of the blue, I'm gonna want money and I'm gonna just choose the person that decided to call me. That is not— so let's share with people what to do, how to really look for money the correct way.
Well, just, I mean, there's so many scammers out there and there's so many people who do not have your best interest at heart. They just want to make a commission and they'll get you strapped in the worst thing that you can possibly have. And next thing you know, that you're having daily, weekly people in your account taking money out, and it's in the thousands of dollars, and it's killing your business. So just like you get those scam calls— I mean, I don't get any of those lending calls, but, um, you get those scam people like, hey, I want to sell you a burial plot or something like that, or hey, this is Google, there's a problem with your account, give me your login and all your credentials and I'll help you fix So whenever you're coming across these people, give them a call back. No, I'm not giving a call back. Research them and then call them. Like, this is Google. Okay, let's go find Google and find the right contact number for Google. Is this really true? And then go right to the source. Not, not hit the give them a call back or reply to this message. I'm sorry, never do that. That's not right.
We're going to redact that. Also, so if I, if they, if they were savvy, they're going to create their own website and make it look so fancy they could do it. Pretty quickly using these AI tools. And so then you got to know how to know if it— and then you could call and they'll sound— to me, it's, to me, it's like this, like seeing a person on a podcast, seeing Sue, like, and then calling her. Like, I would never, I, I would never do— anyone that approached me, first of all, I don't work with anyone that doesn't give me their phone number. So, and, you know, if you're trying to sell to me and you're not giving me a phone number, I, I'm sorry, but So if you try to do it, just know, guys. And, and so because this, it's blown up, right? The lending world, it's blown up. I'm not sure why. So I'd love for you to tell us, do it right now. Why, why has it blown up?
Well, back when I was in my SCORE days, um, we had grants and we had all kinds of stuff. And then as new administration, new stuff came through, SCORE's, uh, budget itself got cut. Like you couldn't buy the donuts with anything anymore. So I talked to some of the other school mentors. I'm like, okay, we're looking for grants. They said you'd have a better time looking, growing your business than looking for grants. There's just not that many out there. So the grants have shriveled up. There's still some, especially in the counties and stuff like that. You could go to your county and see if they have a development or growth type fund that they can use. But a lot of that has shriveled up. Banks have tightened. They don't want to lend to just anybody anymore. Um, qualifications have gotten more, and there's more products out there. Just like we're talking about the insurance industry, they come up with new products all the time for things. Like, things phase out, more things come. Lending has done the same. I mean, credit card stacking wasn't a thing— that's an SLOC— that wasn't a thing like too, too long ago.
Wait, what was it? Credit card stacking? Yes. I don't, I don't know.
Then you take a bunch of— it's called the Nest Lock. When you take a bunch of credit cards— all right, anybody comes up to you and says, I've got this great way that you can get $100,000 for your business and it's 0% interest. Oh wow, that sounds amazing. Well, it is for the length of time, a year, 18 months, something like that. You would have the money for that much time. But if you don't have it paid off in full, then you get credit card type interest. Boom, all of a sudden balloons. So is there a good place for SLOCs? Yes, if you're— it's more like a bridge loan. I have a business and I'm a construction person, and in 4 months I'm gonna finish this job, I'm gonna get paid a lot of money. But in the meantime, I gotta get— I got inventory, I've got payroll, I've got all these things. I need something to get me there. Perfect spot for that. But people don't tell you the whole thing. And then in a year and a half, now you're stuck with these 5, 6 credit cards that you have to pay off, like, now.
Interesting. Okay, thank you for— thank you for sharing that. So, so when I was with SCORE and I was working with the banks and we were trying to come up with something, what surprised me is that the banks were saying that people, business owners, were coming in wanting a loan but couldn't say why they wanted the loan. There was no like, I want a loan because I'm going to buy $100,000 worth of equipment for my business. It was more like, I want a loan. So can we share with the people out there looking, what do you need as a broker? You're going to— do you need a conversation at first? Like, what are those steps that take place?
So I always— because I, I'm up, I'm in front, I'm always here, all that stuff. So I want to have a conversation first. I want to get to know you. I want to get to know your business. I want to know who you're working with. Do you have a business coach? Do you have a fractional? Do you have a financial advisor, somebody that's advising you on your money? I like to work with those spaces, and those are my partners. I partner well with that, those type of people in businesses. So conversation first. Let's talk about your business and your money. Next stop would be, here's an intake form, which is not an application. It is literally an intake form. Just give me all the information about your business, your EIN number, stuff like how long you've been Is this your address? And then I can kind of go to— I'm not kind of— then I go to the Secretary of State, make sure you have a real business because we can't fund some things. So we make sure we have a real business and then we start asking for information. We need tax returns, we need bank statements. We don't— unless it's an SBA loan or equipment financing, we don't need to know exactly what you want to use the money for. But I would much prefer that you do know exactly what you want to use the money for, because I don't want to give you money and say, here, yay, money, and then you go blow it and you're in a worse spot than you started. So that's why I like to partner with the coaches, consultants, fractionals, financial advisors, so that they can help guide the business owner to use the funds that they've just secured. Because there's money— it costs money to get money. This isn't free money. So that they can pay it back and use it wisely to grow.
So you, so you actually create like a team. You don't, you're just not like in there running in, throwing it and running back out. You're actually like there, right? Wow.
Wow.
Can we talk about SBA loans? Because I know at one point I thought SBA loans were, that first they stopped doing it and then it's very hard to get and only a few SBA offices are open. And what is going on in the SBA world?
There's again a place for SBA. I don't want to talk negatively about stuff, but SBA is tough. Um, and then with the government shutdown that we had, but now we have again, who really knows, the SBAs were closed down. Um, keep in mind that this loan is government-backed and the government will ask for its money and You can't put that into, um, what am I talking about, like a Chapter 11 or bankruptcy?
There's always just thinking that word. Okay, bankruptcy. Oh wait, so you can't, you can't go bankrupt on an SBA loan?
Nope, you still owe it. So you can definitely lose your house in an SBA loan. Um, so government-backed, yay. Government-backed, let's think about it. Uh, also you need down payments. So you would need, like, if you want, I don't know, lots of thousands of dollars, you need 10% of, or 20% depending on your bank, uh, down payment. So you might have $200,000, $300,000 you're looking for. So now do you have $20,000, $30,000 that you can put up front towards this loan? A lot of people don't have that. So there's all kinds of qualifications to an SBA loan that we really need to look at. And sometimes, like, for startups You— it's the only option. Nobody else is gonna fund besides friends, families, and fools, I think is what they call it for startups on, um, getting money. And then you'll have private equity too, but then you're giving away part of your business, which could be way more expensive in the long run. Wow.
Okay, so interesting. So really the key is, if you are looking to— you need help in funding your business You need to find someone like Sue Schuster. So let's, let's go over again that, like, the questions that someone would ask when they are looking for a lender— a broker, let's call it broker.
Okay, so how many lenders do you have? What kind of relationships you have? I mean, sometimes you go look online and you see somebody has great reviews, but then you get terrible feeling about the person, or if it's shady or whatnot, because there's lots of shady out there that, that rose-colored glasses and just make it look very pretty online. So I would definitely have a conversation with the person, see if they're knowledgeable, see if they can help you. Um, and if they start to try to pigeonhole you into something, then that's pretty much what they have to sell. I only have said product. I have SLOCs, I have credit card stacking, but really you should do this, this short term, it's a 0%, you'll be good. Well, no, they're trying to— just like an insurance advisor who only can do life insurance, there might be other products out there, but all they have is life insurance. So every— they're the hammer to every nail. So we need lots of different options to go to, especially when we're talking about financing and funding. They should have lots of, lots of ways to skin the same cat.
What is your history?
What is—
how did you get started?
I mean, I—
because I, I can't tell if this is like your first line of work or what you were doing. So give us that background bio. I didn't even ask you for it.
So I was, uh, well, I was a PE teacher. You were 5 years of PE teaching. That was great and fun, but the PE teacher always gets bus duty and lunch duty, and the other teachers don't think they teach anything. But you know, you might be excellent at algebra or trig or whatever else, but if you're, you're not healthy, well, you can't do that anyway. So, opinions. After that, um, I started a swim school. I thought that was a better idea. So that's the business I had for 18 years. We started about 600 kids a week in '04 and grew to almost 2,000 kids a week in 2022. So made it through '08, pretty much flatlined, but did okay. And then made it through COVID. And we were one of those businesses that had a backlog because the kids just didn't learn how to swim. Now they're just a year older and they still don't know how to swim. So we had double the amount in, uh, 2021, '22. So sold in '22. After that, I was like, now what?
Wait, did you get a good price? Were you happy?
Pretty good. And I'm like, now what? I'm too young to not do anything, and I'm too much of a busybody, uh, so got to do something. So I made my way into the financial industry, got my life insurance, my 63. Again, I didn't want to be the hammer. I wanted to give them all the options they could. And then I was like, I don't really like it here. I'm black. FINRA is great, but they have a lot of rules, and I don't like rules. So me and FINRA didn't get along. That one commercial that says we're a fiduciary drives me absolutely bonkers, because anybody with these certificates are fiduciaries, like all of them. And sometimes life insurance is the right product. So if you— maybe you guys can't even offer that, so maybe you're not the right people. Anyway, so did that, and then I was like, I like coaching. I've always been a coach. Coach swimming, coach this. So then I became a small business coach. Still am in my niche of dance, karate, gymnastics, cheer, that stuff. So child-centered activities, like insert sport here, pretty much all do the same thing. And from then I just kept hearing about, oh, we need money, we need money, we need money. So I kind of got rope into this line of credit business lending things. I found our founder. I'm like, I really like what you're doing. I like what you stand for. You need a little help on the business side. I can do that. And we've really grown it to something substantial.
What a delicious combination. I have to say, I think that is fantastic. I love the coaching. Your story is great. Thank you for sharing. I definitely enjoyed hearing every minute of it. Okay, so what would stop someone? So, so obviously you could go to a broker, who to me makes so much sense because just like if you went to a realtor, they have access to a lot of homes. You go to insurance, they have— brokers have access to all the different insurance. So it totally makes sense to me. But what about the people that go and they see something on Facebook and they're like, you know what, well, yeah, I do need a loan, let me, let me click. And they're working with, um, I can't think of the names, but some of those quick and loan, let's just say. I don't even know if they're still in business. Quicken Loan, is that— that's a loan and not— explain that. Like, what's the difference?
I can't talk about Quicken Loans because I really don't know very much. Okay, so I'm not gonna—
is that one product, right? They sell one product.
Oh, I have no idea, but the bank is selling one product, their product.
Okay, so is there— is there— I can't think of, like, Easy Funding, we'll just call it.
Yeah, so, so, I mean, you can go to one of these big places, and you can be a number, or you can have a real relationship. I mean, that, that's really what it's coming down to. And I, I specialize in real relationships, that I want to not only help you with your funding in your business, but everybody you know who's in the same boat you are. So I'm not trying to just do a transactional approach here. Yes, it is transactional. Hey, you need money, we go through the thing, hopefully we get your money. And then you're okay, great, I got my money, I'm out. But word of mouth is how we grew our swim school, and that's also how I want to grow this.
How do brokers also try to get more brokers?
Yes.
Can you share that so I can understand a little bit what, why, and what and how?
Because everybody's got 40 hours in the day, right? Well, 40 hours in the week, whatever. Yeah, we all have the same amount of time.
Exactly.
So if I now train somebody else, now I'm working and they're working, and now I have 5 people doing that. So now, and it becomes a little bit of a pyramid. So I train somebody else, they secure a loan, so they get paid, I get paid, the business gets paid. So the more brokers that I can have to teach and they can get out there and Maybe somebody's good in trucking, maybe somebody's good in med spa, maybe somebody's good in dentist, uh, maybe someone's good with the, the coaches and the consultants. Everybody has their unique ability, and I really triumph them for their unique ability and capitalize on it. And so my team has different unique abilities, and that's on purpose.
So curious about this too, so let's just say that I wanted to be a broker. I'm like, oh, Sue, I'm a business strategist, I have plenty of clients, I would like to do that. What would you suggest? Like, is that—
I would say partner.
Yeah, you say partner with you.
I lead a program. Yeah, you just partnership. So what— that's a lot what I do with my coaches and consultants. I've got somebody who's in construction, so he's a consultant for construction people. Well, I need a loan, so then he sends them to me We secure the loan, the, um, coach would get a little bit of the commission, I would get some commission, and the Ms. Phi would get some of the commission. So it just works really well. So not only are they serving and being another tool in their tool belt, they're serving their client, getting them what they need, so that now that we continue their relationship, we grow and scale with the new money, um, and we take it to the right place. So it works all the way around, wins for everybody.
So if I'm a business and I've been in business for many years, but I'm struggling, and I think to myself, a lot of my struggling is because I can't get the inventory, I can't do this, I can't do that, I can't grab this, I don't have access— sorry, um, I— someone, a client was calling me, so I— Daryl, I'm sorry, I'm doing an interview myself. Anyway, I'm a podcast producer too. We're supposed to be 24 hours, like you're supposed to be 24 hours open. So I lost my train of thought, obviously, because I'm old and I'm not as young as you. I want to ask you a question. So with SCORE, are you— does your SCORE office— I know that with SCORE you can't recommend, you could like give 3 recommendations if you're doing it. Are— will your SCORE office, if I went to your SCORE office, I talked to them and I said I was getting some advice and help, and then they realized You know, you could, you'd be able to quadruple your money if you just put this into it and got this piece of equipment and got this inventory. But I, okay, but I don't know who to go to. And they give me the 3 names. Would one of your names be included?
No, because I have not been part of SCORE for a little bit. So after this, yeah, I'm no longer a SCORE mentor. But yeah, after their funding got cut and because a lot of the people are retired and they don't have any kind of skin in the game anywhere. And so that's great, but they don't also really go look for new things. Whatever SCORE gives them, they get, they get. So I am no longer part of SCORE. So my name would not pop up there.
I mean, I always thought that if you were, if you were, were you a SCORE subject matter expert or a certified business mentor?
I was a mentor.
Oh, okay. So, so, but with SCORE, you're not able to do any business because you're— but what I'm trying to say is if you are not even involved in SCORE at all, and you're going— your client of SCORE, are you able to— will they recommend a lender?
They will, and it's probably the bank that they have a relationship with.
Okay, so it's all relationship. That is really the word though. That is the key to this, money and relationship. I, I, yeah, I couldn't imagine working with someone or, you know, uh, who's calling. Oh, it's AB345892.
Let me pull up your numbers.
Oh yes, how could I— like, no, you want to sue, right? It just makes total sense to me, Sue.
Yeah, it is completely relationship-based. And think back in the day, pre-computer, like they go to Joe Schmo at the bank, probably say, I need money. Joe Schmo says, yeah, here's your money, and gives you a handshake, and off you go with your money. I mean, that's how it used to be. Now we've got all kinds of qualifications, everything else, but it's still a relationship.
Yeah, it's such an important conversation, and I wanted to ask you, is there anything that I didn't ask you that you would like to share?
Um, I don't know, you got most of it.
What about rates? Like, I know that the S&P, I think, hit 50,000, and, um, and somebody—
Federal Reserve and their, their rates, because you got prime. So prime is the amount that the banks have to charge. Now, if the bank wants to make any money— and that's the rate that the banks are lending money back and forth between the banks, because they do that all day long, they lend each other money all the time. So when they're lending you money, they need to make money off of it. So you got prime plus 2 or 3 points. That's the money the bank makes on your loan. So depends completely on your your FICO score, your time in business, your revenue. The greater the risk that you're going to default, the higher the rate goes. So things that are more secure, like equipment financing— there's collateral there, that is the equipment. So if you default on your loan, I get my equipment back. That's how I get paid. Uh, SBA is government-backed. That is a lower rate loan because if you default— it's always, if you default, how am I going to get my money back? I'm going to take it out of your Social Security. I'm going to make you sell your house. I'm going to do all these things. So then you have things that are unsecured, like, um, some of our growth term loans. A lot of the business loans are unsecured, that your house does not have a lien on it. And if you default then you file bankruptcy and I don't get any money. That's how that works. So they are higher. Now we're talking about 14, 20%. After that, you get to the credit cards. Now we're in 25 through like I've seen 50. So it's all on if you can't show that you have a great ability to repay, if you're a higher risk. Or your business is not quite as fundable as others, you will have a higher rate.
That's so interesting. Okay, that— thank you for that. I can't think of, I can't think of really any more questions that I have. I mean, I know there's tons, but I'm not in the industry to really ask it. So, so just to prep you again, if there's— is there anything else that we should share with the audience?
Do some best practices. Make sure you're separating your personal and your business finances. They should be completely separate. You can also grow your EIN credit— means credit that's just on your corporation, not attached to you. That is something you can grow over several years and then get substantial credit. I can teach you or send you to somebody who can do that. So that, that is a key strategy. There's also people out there who are doing shelf corporations. I can tell you all about shelf corporations. Some work, some don't work. They're all expensive. They're all—
I'm sorry, thank you for recognizing that. I may forget my train of thought. So the EIN number, so you're saying— so normally when we first started talking, I was thinking my personal line of credit is going to be looked at, but you're saying if you grow your business credit, that could take 3 years, that, that could— if you have great— does that— is that like an 800 too?
Is that the It's changing. It is changing. So that's like Dun Bradstreet, Experian Business, Equifax Business. That's where that stuff is. So Dun Bradstreet, you can get your DUNS number and you can get qualifications and all that for free. But the key is to have people report to Dun Bradstreet, Experian, or Equifax. And it costs a vendor or business money, not the one who wants the corporate credit, but like the— you have a gas card. You have a gas card, some gas cards report, some gas cards don't. It costs the money for the gas card to report to Dun Bradstreet, Experian, or Equifax. So it's not— you have to know what to use that actually gets reported. And your local bank is not reporting.
When you, when you apply for a business, so you're applying for like a business line of credit, If you're doing that with your bank, you're growing corporate credit.
That's what it's called. Might not be corporate, but you're building corporate credit with that bank, but you're not building it at the 3 bureaus for anybody else to see. So you go down to your local credit union, your local bank, that's not building corporate credit, although some of them do. There's a few in Pennsylvania I could tell you about, like KeyBank reports. Bank of America does not report. No, wait, no, they're starting to report. Chase Bank does not report. Your Amex card, not reporting unless you have the Black Card, which is the high card that you have to have. That's not reporting. So all these things that have your business name on it probably aren't reporting.
That is, that is so interesting. Wow. Wow. You're sharing so much. I, you think I would know all of this, but I, I know this.
I had a business for 18 years. I know I couldn't have a clue. All I know is our Capital One card kept getting hacked. That was annoying.
So the D&B— so I am familiar with Dun Bradstreet. Growing up in a family business, we were always 3A1s. I remember that was something that slipped up. I think that's like one of the best, right?
And, uh, well, I mean, it's one of the three. Not one's better than the other. It's just like our TransUnion, Experian, and Equifax. They put them together and make your— every one of them looks at things a little differently. And some corporate credit reports to Experian, others report to Equifax, and some reports to Dun Bradstreet. A few report to two of them. Report to all three.
So I never thought of— that's so interesting. All right, so, so the key though is actually, if you do have good business credit, I personally, I think that that's almost could be in your marketing, right?
Like, because yeah, I did teach about— I mean, I do teach, but I, I was really part of that world, but it is such a long process that business owners get tired of it real quick. And there's a lot of education and there's a lot of apply to this card, now dump that card, get a new card, get the better card. Now you're in tier 2, blah, blah, blah. I think you may have misunderstood me.
I'm thinking, I'm thinking if I'm going to sell a product or I'm in a big business, one of the reasons to work with me A benefit would be that I have good credit, that you could trust me. Okay, a lot of business on it. Sometimes I wonder how, how business— I'm sorry, sometimes I wonder though how, you know, people will spend $150,000 with a company but yet they didn't really vet them. Um, or, or, you know, so to me, I would like that as your marketing to let me know that you have great credit, right?
And businesses do look at other businesses. They just need a subscription to something like Credit Suite, and then I can go look up any business. So I mean, just for fun, I was on there like T-Mobile, Walmart. I mean, who knows what they're doing with corporate credit? And it'll show you how much the recommended amount is that is unsecured, as in there's no board member saying, I'm going to personally guarantee this, I'm going to personally guarantee the next, uh, factory we're building. Nobody does that, not in the big world. So they all utilize their corporate credit, either with their bank or without, and we can kind of look to see who knows what they're doing and who doesn't.
That is intense. All right, I, I'm going to, um, I'm going to say goodbye. I love this conversation. I do want to share that this is my PodMatch book. This has actually got a foreword from Alex. And, uh, Sue, you were from PodMatch, right? Yes, the PodMatch community. I, and I love it. So Alex did a foreword, he's got a chapter in the book, but I'm putting together my next episodes of the book and the color will be purple. So you will be receiving the manuscript. There is a slight cost to it, I'm just putting it all together, but once you see it, you'll make your decision what you decide to do with it. Um, I think it's— you're gonna love it. You've dropped so many great Golden Nuggets, uh, the book, it's like a narrative, so it's really cool. So, um, I want to say thank you again. I will make sure you have all of your information. And again, tell us about the website because I, I myself is a little confused. Let's, let's just take 2 seconds if you don't mind. Let's, let's show it off and then you guys grab. So, all right, so I have Sue's LinkedIn. Right here so you could see it. And then I'm just going to go grab it this way. Oh, I like the way you put your email right there.
That's brilliant.
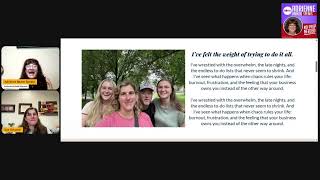
Okay, and then her contact information is here. Boom. Here, let me share this tab instead. Don't you love the picture, guys? I love the picture. They— so Sue, this is family, her siblings. Okay, kidding, guys. I know you're the husband, wife. I get it, I get it. But you all are so beautiful and young looking. Not my fault. Um, I love this. I love that. I felt the weight of trying to do it. I loved when you went back and told us about, like, you know, your, your ex experience. I, I love your past experience. I love it. I love, I love your, your theme picture too.
That one's fun. That one. So let me read it.
I felt the weight of trying to do it all. I've wrestled with the overwhelm, the late nights, and the endless to-do lists that never seem to shrink. And I've seen what happens when chaos rules your life— burnout, frustration, and the feeling that your business owns you instead of the other way around. That's awesome, Sue. I love it. What, what are you jumping? Oh my God, are those hot coals?
It's fire!
Wait, wait, wait, wait, what? Where are you? What are you doing?
That is a Spartan race. I've done 33 of them, uh, so it's an obstacle course, my run. And that's the, the finish.
Did you say 33?
I did.
I, I don't understand.
What do you have?
You did one like 2 a year, 3 a year?
One I did 9.
When you did 9?
Yeah, and there's different world records now on Plug and Spartan, but there's the short races, which this one is, is a sprint that's like a 5K, and then you have the 10K, which is the, the middle one called the Super, that's green. And then you have the Beast, which is, I don't know, 13, 15 miles, but they always put it on a really large mountain that you run up and down a bunch of times, and there's obstacles.
So, so, so what's the, what's the, um, most amount that someone did in Spartan?
Like what, like, like, oh my goodness, you can do 3, 3 races in one weekend, but, uh, there are some people who do the lots. Like, oh my gosh, how far—
how, how high are you jumping?
Oh, I'm not jumping real high. I mean, it's, it's, it's like 2 logs high, so it's not real high, but you can see one of the other, um, obstacles behind that one.
Oh, I can see it.
Wow.
Oh my God, I love that. If you're fierce doing this, you're definitely going to be fierce in business. Oh my God. And brave, bold. Holy moly guacamole, this is a great site. Oh, and you've got your— I love this. That— I love the way you're— I'm not gonna cry. It's just a really sweet picture, by the way. Okay, I gotta get off your site because it's so beautiful. Sorry. Oh, it really is. So that is— wow, I am so glad that you said yes to me. Well, I said yes to you.
I do say yes out there, but I always do. I mean, go to church by myself because, you know, everybody's lonely. Just meet new people. Gotta get out there. I mean, you always have a no unless you present a yes and allow them to say yes. Otherwise you get a no. So I'm out there.
I just admire you, just everything about you. Thank you so much for being here today. The last quote probably will be the quote that'll be pulled from the transcript. That, um, I'm glad to meet you. I'm glad we're following you on LinkedIn. I'm going to follow you. I'm happy to support all of your posts. And love the work you're doing, keep checking on your LinkedIn and the contact to see when you get that where you can put your website. I don't, I don't know why you don't anymore, but maybe give it a week, um, with your premium and see if that will do the trick, because sometimes that was it. But otherwise, if, um, there's anything I could do for you, let me know. But I really— and I love to share your information. So Sue, you and I are friends. Shake. I love it. Thank you so much for being here today.
I really enjoyed it. And this will be—
I think I'm 1, 2, 3— I think about 4 weeks By the way, guys, Sue, do you know how many downloads I've been getting? I've been getting 5,000 a month. I hit that 5 grand a month. 1,250. And just think, I'm trending in the Netherlands. So there you go.
I went to the Netherlands. I played field hockey there for a hot minute.
Oh, that is so awesome. All right, thank you so much for your time today. Have a great rest of the— Happy Valentine's Day with your beautiful family.
Thank you.
Uh, bye-bye.
I'm gonna end the stream.