Global CEO Ashish Rai on CNBC-TV18 | FY25 Results, Growth Strategy & FY26 Outlook
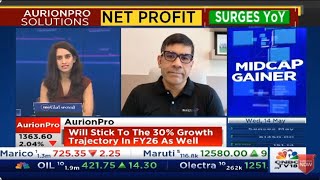
Transcript excerpt of a CNBC-TV18 interview with Ashish Rai, Global CEO of Orion Pro Solutions, covering FY25 results and FY26 outlook. Key facts: reported FY25 revenue ~₹1,170 crore (≈32% growth year-on-year); EBITDA margin 20.6% in FY25 vs 22% in FY24 (≈140 bps compression); PAT guidance around 15–16%; FY25 product/channel investments ~₹97–98 crore and planned FY26 investments ~₹160–165 crore; Europe expansion with investment ramp-up; acquisitions contributed minimal revenue (≈1% or less); order book >₹1,400 crore and pipeline said to be ~50–60% larger than at the start of FY25. Management expects to sustain ~30% revenue growth and to operate around a ~20% EBITDA band while investing for global scale.
Chapters
Welcome back. Orion Pro Solutions is in focus. After reporting the Q4 numbers, net profit and revenue surged over 30%. Margins came under slight pressure. Ashish Rai, global CEO of Orion Pro Solutions is now with us on the show. Thank you very much for joining in. While it's a good quarter and even for the full year, Ashish, you've clocked in a 32% revenue growth, so maintaining that 30% plus trajectory. I remember our last conversation and you said that you are hopeful of pushing the top line for the full year to about 1150 to closer to 1200 crore. Has the year the quarter turned out in line with expectations? And for the full year, next year, FY26, what can you guide for? Can we sustain 30% growth?
Good morning. Yeah, thanks. And thanks for remembering the last conversation as well. Yeah, look, it's been a, it's been a great year for us. We said we'll come in between 1150 and 1200. We came in 1170. The business has now grown at 30% plus four years in a row. I don't think there are many other tech businesses in Asia anywhere in the world growing at that pace so consistently. So I think we feel good about where we are, we feel good about the demand environment and also feel very, very good that both the segments of the businesses have grown at a good clip. Banking grew consistently through the year. TIG had a slow start, but we, we picked up the pace going into the second half and, and it came in, it came in at a good, good thing. I think we, so overall we are good. The margins have been good at the pace at which we're investing. Of course, you know, margin will go up and down one point or two here and there. But I think overall the pace at which we are accelerating, we feel very, very good about where we are. There's also been fairly strong conversion of EBITDA into cash and, and that's again, you know, sort of points to how efficiently the businesses have been run over the year. Going into FY26. I think we've been, we've stayed on a trajectory for the last four years since we pivoted the business into building out the, you know, the global products, global platforms player that we're building out. I think we'll stick to the growth trajectory and we will continue to, to grow at about the same pace.
So 30% plus should sustain even in FY26. But there were also a few acquisitions that you concluded there was small tuck in. But can you tell us what was the organic growth last year?
So all of it is organic growth. I don't think there is any material number coming in from the acquisitions. We don't really acquire for revenue. If you were to attach a percent to it, I would say it's probably 1% or thereabouts or maybe slightly less than that coming in from the acquisition. So I think why we acquire is mostly for the IP and the quality of the team and it's fit with our longer term strategic blueprint, not so much for revenue. So there's not, not, it's not a material number.
Thank you for joining in. You know, most of this large IT companies during this quarter in their commentary mentioned that clients have been turning cautious. They are in a wait and watch mode and so on and so forth. I know it's still early days, it's just a couple of days since this tariff easing happened between us and China. But what have you been hearing from your clients on ground? It's been almost 45 days into the first quarter of FY26. What have you been hearing on the ground?
Yeah, so look, we are not really that much affected by what goes on in the US. First of all, 90% of our business is in Asia, you know, India, Southeast Asia, Middle east and Africa. And I think the demand environment has been fairly strong. The second part of it is we are in spaces where you're going through a little bit of a demand super cycle. Almost on the banking side, we see the move away from custom software, which is very legacy, into buying out mature enterprise software that brings in the best practices in the spaces we are in transaction banking, lending. I think we've never seen a demand environment so strong. Similarly on the transit side, the movement from closed loop to open loop, I think it's a massive movement around the world. So again, a very, very strong demand cycle. So overall I think from a demand environment, honestly, pipeline is very, very strong. Our win rates are very, very strong. We built out products which have proven to be very competitive. So we will I think keep on accelerating at the pace we've been accelerating last few years. I'm not really qualified to comment on the broader IT services space. We don't really know much about that space. But in the products that we build, the platforms that we build, demand is very strong.
Ashish margins in FY25 were 20.6% versus 22% last year, FY24. So there was a margin compression of 140 basis points. Three reasons why that happened when you look back. And what can you guide on margins going ahead?
Yeah, so I think we guided beginning of the year between for EBITDA to land between 20 and 22 back to land between 15 and 16. Pat came in slightly ahead of 16. EBITDA came in in the band at 20.6. I think the way to look at it is this, right? I mean I would not look at as margin expansion or compression. I look at it as we are building a business out. We are growing at a very fast pace, which means we are investing at a very, very fast pace. And most of our investments are actually expenses because we don't really capitalize much other than, you know, where we need in small parts of our business for regulatory reasons. Right. So most of that build out, expanding into newer geographies like Europe is a huge bet for us this year. So investing close to 60, 70 crores, 60 crores plus in that overall product build outs, we've invested in transaction banking, in transit and lending. So there is a massive amount of investment going on. So it would always be very, very hard for us to calibrate the margin down to a percentage point. And that's why we give a 2% band when it comes to margins. This year we will step up the investments overall. So again we will operate within a band. I think 20% is about the level we feel comfortable with. But it will go up and down depending on the quarter. It's very, very hard to calibrate down to fine point. But overall I think the economics in the business is improving which allows us to invest more and more in building products out, go into new geographies and keep powering the growth ahead. This is not the time for us. We said this before. The next three, four years is the time for us to really grow global scale. This is not the time we will try to optimize the winters.
No, got that. You need to step up investments, prioritize growth and increase your total addressable market. Get that? That's the logic behind it. But in terms of numbers will a downward bias. So you're saying FY26 margin should be closer to 20%. What is the 20 to 22% margin band that you operated in in the prior year? So is there a downward.
Yeah, I think so. So I think, you know, there may be some pressure for a couple of quarters as we expand into Europe. So Europe as you know is basically zero or very close to zero last year. This year we expect Europe to climb up to at least 7 or 8% of revenue, which means a very significant investment in building a sales team out that we're Already done half of it and a very significant investment in building the products out to make them ready for the markets we are going in. So for the next couple of quarters the investment will be pretty heavy around market expansion. Overall I think we should be able to hold to a number in the range of 20% but from one quarter to the other it will vary in terms of growth. I feel we should be able to grow certainly excess of 30% on both revenue and earnings thereabouts. And I think that's, that's roughly where we'll be on the guide.
So just some numbers PAT margin guidance. 15 to 16% stays.
It stays. Yeah.
Okay. What were your investments in FY25 Ashish? Because you're talking about stepping it up and what would the number look like?
So FY25 mainly around the product. We invested close to 9798 crores in terms of product build out and incremental channel investment was fairly incremental. I don't think it was. Significant this year. I think it will certainly be a number more than about 160. 165 crores including product and channel investments.
Okay, so investments of 160 to 165 crore this year versus about 97, 98 crore last year.
Go ahead Ashish. I wanted to ask you about your order book. Currently at the end of the third quarter it spread around 1300 crores. What was at the end of the fourth quarter and what is the kind of pipeline that you're looking at? You mentioned that the deal pipeline continues to remain very strong but if you could quantify that.
Yeah. So the order book now stands at about. It's certainly more than 1400 crores. So typically the way it works for us is we don't really declare that many multi year orders. We also keep most of the AMC is allowed. So most of the order book for us is executable over the next four to six quarters. So every quarter we sort of consume from the same order book and we add to it. So an incremental 110 odd crores addition is a pretty significant thing in a quarter. So it's very, very strong and most of it will get consumed in FY26 and that gives us a lot of confidence in terms of the demand outlook for 26 pipeline I would say is at least 50% larger than when we entered FY25. It's probably 60% larger than what we have by 25. So I think the demand pipeline is really something we've not seen before. I think Part of the reason is the transformation spend on the banking side, which has really gone up, especially with demands around AI and almost all the banks want to catch up on the technology stack. So I think that demand is really strong. And second also is because now we are in a lot more newer markets. So we've gone into Europe, Middle east is a lot stronger, Southeast Asia is a lot stronger. So that also adds to the pipeline. So the pipeline is really very, very large right now and we feel, we feel good about the win rates we will have on that pipeline given how competitive our products have proven to be.
Since you are stepping on the investment pedal, what is the cash in the books and the cash generation that you anticipate? And also I think your banking revenue contribution has come down. Last year it was more than 50% and this time it's about 34%. So explain that also to us and is that going to change?
Yeah. So look, that is a very tough one, Riva. Right? So I think, look, both sides of the businesses are going, businesses are growing at 30% plus and from one quarter to the other, one side of the business may grow a little bit stronger and that moves that percentage up or down 1 point. I would not read too much into the 1 point movement as a change in mix. Banking will continue to grow very, very strongly as we go. And a lot of that constraint, the growth comes not so much from the demand. I think the pipeline is strong, the conversion of the pipeline is strong. It comes from the capacity. It takes us time to really build. And that's why we, you know, we feel comfortable around the 30% growth because we feel that is a safe pace of growth for us while we, when we sort of grow, but we also keep the delivery reputation intact, make our customers successful. Right. So I would not, you know, I think from one quarter to the other it will change, but broadly I feel it will stay the same. Both businesses will continue to grow at roughly the same space. If you look at a four quarter period on a one quarter period, that may go up or down a little bit.
All right, Ashish, thank you so much for sparing time and joining us today. Wish you good luck for the rest of the year as well. Take a short break on the other side. More on the mark.
More from Ashish
'Rs 5,000 Cr By FY30': Aurionpro CEO Ashish Rai Reveals His Plans To Grow 30% Annually
Ashish Rai, Group CEO of Aurionpro Solutions on How India Is Emerging as a Global Tech Hub
Aurionpro Group CEO Ashish Rai on CNBC-TV18: Growth strategy and Fintra acquisition
Ashish Rai, CEO of Aurionpro, featured on ET Now discussing Aurionpro's Arya.ai acquisition
Ashish Rai, CEO, Aurionpro Solutions, in an Exclusive interview with NDTV Profit