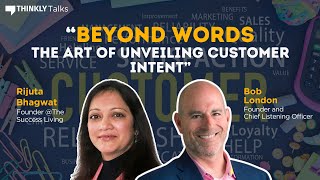
In this interview, Bob London and Speaker B discuss the financing journey of their media startup. They raised $400 k from sophisticated friends‑and‑family angels in Washington, D.C., with an initial hope of later venture capital. However, their business model—focused on early profitability rather than rapid audience scaling—clashed with the prevailing VC narrative that favored BuzzFeed‑style, high‑growth media properties. After receiving term sheets that undervalued the company, they chose to wait, proved the model by becoming cash‑positive within 6–9 months, and ultimately decided against selling equity because they could now fund growth internally. The conversation reflects on whether the undervaluation was a market perception issue or a communication shortfall, emphasizing the importance of controlling destiny and aligning investor narratives with a contrarian, profit‑first strategy.
You have not— had not taken in outside money other than I think some friends and family type financing. Was that the goal to be bootstrapped or was it just something that you realized you could achieve and continue?
We were fortunate, you know, the friends and family, I would say sort of sophisticated angels from the DC area, right? But we raised $400,000 to start with. And that was sort of a number that we felt could get us moving. At one point, we hoped that there might be venture dollars along the way, but the reality is we're a bit contrarian in our thinking at the time, and it was a harder story to tell some of these venture capitalists, the ones who were investing in media. And at the time, the folks were chasing the BuzzFeeds of the world, the Vices of the world, which were all about getting as many eyeballs and scale as you could, and sort of, we'll be profitable, monetize it later. And what we were doing was distinctly opposite of that. And so we knew venture was going to be a hard sell, so we wanted to bootstrap for a while. We went out and started looking, uh, for money maybe, you know, a year in and got a couple term sheets. But what we realized is the term sheets didn't see the value in the business we saw. And we thought, if we can hang on for another 6 to 9 months, we can go back into the marketplace and show a much different company And what transpired is, you know, 6 to 9 months later, we were profitable and generating cash and we just never needed the money. Interesting. And at that point we just thought, why would we sell away parts of our company when we are now, you know, we're running now. Yeah. The business we can grow.
Control your destiny. When you mentioned something just now about the term sheets didn't reflect the value in the business that you saw, do you, in retrospect, do you see that as that's just the way investors were thinking or could you guys have done a better job of expressing underpricing the value?
I think it was both. And I think there's parts of this that entrepreneurs always see the, you know, a bigger value in their business, right? Like, that's why you start a business is because you truly believe that this thing is going to be fantastic. I think we also could have done a better job telling the story. And quite honestly, there are some things we wouldn't tell. Like, I didn't want to promise anyone, no, no, this is going to be a $500 million business in 5 years, right? Like, that's just not how media works. That's not how successful media works. There's a, you when you're trying to grow audiences, that takes time. When you're trying to grow traffic, you can buy that, but audiences takes time. And so part of it was we didn't, we could have told a more inspiring story, but part of it was we didn't tell a story that venture capitalists at the time wanted to hear.