The Entrepreneurial Journey - Make More Marbles PODCAST with Brad Hart & Travis Steffen
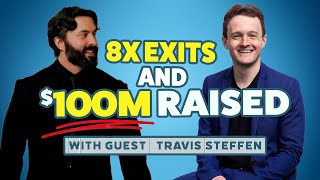
Interview on the Make More Marbles podcast (Sept 29, 2024) with host Brad Hart and guest Travis Steffen. Travis narrates his path from athletics to serial entrepreneurship (eight exits), selling Grow Flow (a B2B SaaS for licensed U.S. cannabis operators) and later shifting to consulting and startup advising. He ran an aggressive guaranteed consulting offer: double a client's growth in 90 days or refund plus $3,000 cash. Flagship consulting pricing started around $20,000/month; booked-call CPA for the offer was about $28–$32 with initial call-to-sale close rates ~75% before operational scaling limits forced a productization/streamlining change. Travis discusses growth-by-experimentation (themes, 1–3 experiments per theme/week; avoid unlabeled A/B 'horse race' tests), fundraising/exit tactics (cold outreach to hundreds of funds; building acquirer relationships early), and his current churn-recovery startup (Ravado/Ravato/Rado) — performance-based pricing (20% of recovered MRR), claims ~86% recovery on involuntary churn, typical minimum customer MRR ~$40k–$50k and largest ~ $1M/month. He is a doctoral candidate in marketing with an AI emphasis (expected completion early 2026) and mentors at major accelerators.
Questions this video answers
Double the client's growth in 90 days or refund every dollar paid plus $3,000 cash for wasting their time.
About $20,000 per month for the premium engagement.
Approximately $28–$32 per booked call.
Roughly 75% in the first month or two.
Eight exits (as a founder, co‑founder or CEO).
Chapters
Foreign.
Welcome to make More Marbles. My name is Brad Hart, and today I have a very special guest. I have Travis Steffen. He is a dear friend of my friend and mentor, Joe Stolti. And shout out to Joe. We just had a mastermind recently with Joe called Prime Live in Austin. If you haven't checked it out, definitely do. And we had some really great people there with David Gonzalez there and Alex Moscow and some others. Travis came up in a conversation we were having about market research, and Joe told this story and I'm going to mess up the details, so we'll get into it here in a second. But the essential piece of it is Travis was getting into consulting and he ran this ad that was like, I'll give you more than your money back if you felt like I wasted your time. It was like this super aggressive ad that was like getting some of the best and brightest in the industry. Got him a bunch of clients, and I'm like, that's like market research on steroids. And since we talk a lot about that in the book, I wanted to do an interview with Travis and get the, you know, from the horse's mouth, what exactly happened, how he did this. And, and why don't we start from the beginning? Travis, tell us a little bit about yourself, your background, multiple exits, incredible, incredible career. Let's start with that and we'll, we'll roll right into this.
Thanks. I mean, yeah, it's been a, it's been an adventure, that's for sure. Let's see, what can I tell you? Born and raised in Iowa and eventually escaped after my first master's degree in about 2010 and came out to Los Angeles, spent some time out here, went up to San Francisco, came back down, which is where I'm at now. But started my first in undergrad and was at the University of Northern Iowa. Went there to play football. Did not go there to use my brain at all. Immediately had a rude awakening in, in Division 1 athletics that I was not at all in any way in the league of the guys that were, that were getting playing time and destined for the NFL. And so that kind of nerfed that dream.
Isn't it crazy when you're like, you're playing football and then you meet a real football player and you're like, this is a different person. This is a difference type of human being. Like, this is not a subclass of this person.
The, I mean, the physical gifts were profound. I would say the, the thing that I was unable to overcome without any shadow of a Doubt was how quickly these people were able to react and how just ingrained the game was in their psyche. They, they just knew what was happening before it would happen. And I, I just had not had that type of coach not build that type of, like, cognitive awareness around the game, which I, I was completely unaware that I was missing. And it was, by that time, it was far too late, you know, because when you're trying to break into a depth chart, you're not getting any reps or anything like that, so you have to make up ground, and I hadn't. So, you know, it took me popping My Achilles tendon 2 1/2 years in and just being forced out of the sport to really have that sort of, of, you know, choice made for me. And even, even after that, I, I fought professionally for a little while here in the States, in Thailand. Eventually just came to the realization I was doing that and I was playing professional online poker with a what am I doing with my life? Moment, trading money with a bunch of other nerds on the Internet like me, and getting punched in the face all day. Like, what am I contributing to the world? I mean, at 21 years old, you rarely even think like that. So thankfully, I had recently started, kind of started my first company just as a, like a vanity project and just decided I was gonna go all in on entrepreneurship and try to become the best I possibly could at that and just got obsessed in the same way that I had gotten obsessed with, you know, sports and, and things like that in online poker for a while. Like, I made that my life for several years. And, and so over the course of the next 17 years, you know, thankfully, I've been able to. To do a lot of things. Some really good outcomes, some not so good that the, the world and the press don't often hear about. But, you know, along the way, I have had eight exits as a founder, co founder or CEO, have taken a couple other companies that I have not been CEOing or, or was a co founder of to exit as well. And since then, like, a number of my clients have. Have also know, gotten some exits to. Not all of them are the ones that you see in the movies and read about in, in TechCrunch or the Wall Street Journal.
Sometimes an exit is I got out alive.
Right, Exactly. Sometimes the exit is you get your money back plus a little bit of extra. Sometimes it's. It's gaining a good reputation with your shareholders and investors and gaining a line item on your resume that makes it easier to do it the next time. Sometimes it's a, holy crap, my life is set and I can choose whatever I want to do for the rest of my life. And people think that they're gonna sit back and sit boat drinks and lay on the beach. And if you've gotten to that point, you're in for a rude awakening if you think you can tolerate that for any more than a couple weeks. So. Yeah, well, if you're the type of.
Person who's going to build something that you can ultimately sell and exit from. I think Tim Ferriss said that in one of those books behind you there. If you're that type of person, you're going to sit on the beach for like seven days and then want to stick bicycle spokes in your eyes and get right back into it, you know?
Yeah. And candidly, I mean, sitting idly on the beach is not as fun as, as you think it would be. I mean, I live, we're, we're on the ocean in Los Angeles, like on the west side of Los Angeles. You can jump off out of, off our balcony and into the water. I don't ever go to the beach. Like, I, I'm that guy. Like, I, I don't like the sand. I'm a weirdo. So. But it's been a crazy fun journey, like, you know, going through startup life a million times. I'm also, you know, now really fortunate to be able to give back a lot to the startup community. I am a mentor, like a growth mentor for all the major Silicon Valley Accelerators, Techstars, 500 Startups, Mass Challenge, SOSV Hacks, Orbit, IndieBio, a bunch of them. I'm a doctoral candidate in marketing with an emphasis in artificial intelligence in the space. Should be done with that by early 26. And that came on the heels of finally between exit 7 and 8 and MBA, just to kind of figure out what I don't know. The real answer is like, these are very worthless degrees at the end of the day, but there are little nuggets in there, here and there, that end up making all of it worth it. And there's also some level of just prescriptive ability after you reach the pinnacle of academia as well, where your expertise is sort of just assumed. And so the, the things that work but don't necessarily have the necessary credence for people to buy into without that label ends up being, you know, a lot of an easier process.
That's so interesting to me because, you know, entrepreneurs, they make their own way. It becomes less about, you know, money. Right. As you get More successful. And I sound, I've heard a lot of them going back and getting Master's degrees and PhDs and getting into research and publishing more books. And you know, some of it makes sense to me. And some of them, like, why would you, why wouldn't you run screaming from academia and go make your own thing? You know what I mean? Like, you don't see Elon Musk going and getting a doctorate. Like that just makes no sense to me. So I'm wondering what drew you to that and what, what you believe the benefits were. What, you know, what do you.
Yeah, actually it was a conversation with a multiple time co founder who you mentioned at the top of the podcast, Joe Stulte. We've been close for about a decade and a half.
Building things back in the breakdancing days.
Yeah, oh yeah, oh yeah. I was not part of that. But he, he's very good at what he does in that way. But he, he had made an analogy at one point just in a throwaway conversation that we were having, that just the power of the word doctor is still so present in society where, you know, just using a medical doctor, for example, you go in and you tell them your problem and they pay attention for 30 seconds. They write something down on a scratch pad and they say, this is the solution. You take that blindly to a pharmacy. You walk past 10 aisles of a hundred different things that could help you in the same way that this thing that they gave you. Otherwise, could you go up to a counter, pay literally anything they tell you to pay, and take it exactly as they told you to take it until you're done. Like, that's, that is the experience of most people with doctors, and that's the case in many realms as well. That title holds a lot of power in the eyes of the general public. And if you're trying to use your powers for good and really influence people ethically, it's, it's a really kind of like powerful frame to come from. Now you can take a number of different paths to get those letters in front of your name, but personally I opted for, you know, a lesser known path called a dba. Kind of like a super mba, right. The doctoral equivalent of, of a practitioner's business degree. Right. Which would have, would be my, my third, you know, graduate degree. And at the end of the day, in terms of like what I've actually learned that I'll go and put to use in entrepreneurship, you know, probably very little, but the, the process I would say of, of like going through the ringer on trying to satisfy all the criteria to contribute to the body of knowledge has been eye opening. The failures of academia have also, like, just how antiquated everything is has also been an eye opener. So maybe there's a business there in the future, who knows? But at the end of the day, the purpose has more so just been, you know, I wanted to try to add another tool in the tool belt. I wanted to try to validate an expectation that, hey, the field is the best place to learn. And you know, candidly, I think being able to have a more comprehensive approach to learning is always something that I want to be active in. So it's, it's entirely possible that I'm down this rabbit hole for many more decades. We'll see. But it'll be nice to get this first one out of the way.
Yeah. And the more you're talking about it, I mean, I think back in my own life, my grandfather died when I was six of a heart attack. So growing up, I always wanted to be Dr. Hart, the cardiologist. Right. And I was going to save everybody. And I didn't know what that meant at the time. And I built my whole identity and career around this idea. I'm going to med school. I'm going to med school. And then when I kind of got to the precipice of going to med school and I did my, you know, two of science courses that were like back to back, you know, physics and Orgo and all that stuff, it was hard, man. And then like going for the mcat, having to learn physics because I basically was left behind on math at, you know, grade eight or so. Didn't really do well after that. After being like a couple years ahead, I ended up about even at the end of all just because I kept failing and beating my head against the wall. You mean you want letters and numbers in this equation? What's going on here? I had to like, teach all my stuff that myself, all that stuff out of these like exam crackers books. I remember that was a big thing. And like, I was, I was training for a triathlon at the time. And it's just like this crazy transformative period of my life. When I finally let go of it, it was like a spell had been unwound. But it's so deeply held in you. Like, I remember still having nightmares. Even today, I'm 39 years old, I have nightmares that I didn't get some credit or I didn't finish some paperwork or I didn't get my degree or something weird. Happened. And I wake up and I remember, I'm like, this has no bearing whatsoever on what I do in life at all whatsoever. Nobody cares. I've been so far removed from that for so long. Like, I've been out of that longer that I've been in. For some reason, it still says such a deep hold on you. And you talk about it like it has a deep hold on everybody. It's like this, this. This cult of expertise that we've crafted that is so. Like, it might as well be witchcraft in some ways. You know, it's like, how can we possibly believe that all these pills actually do what they say they're going to do? Or that that's the only way to heal people? But that's the only method that's, you know, like you talked about. You go talk to somebody for 30 seconds, you get a prescription, and all your ills go away. And then we'll solve the problem that that creates. And we'll solve the problem that that creates. And pretty soon you're taking 75 pills. What the hell's going on today?
Yeah, but let's be honest, man. The real people at fault in, in the pharma equation like that aren't the doctors that are. It's actually.
Exactly.
It's people like us that are actually like, yeah, you know, building the businesses that are influencing those people and utilizing their expertise for unethical means. So it's. Yeah, it's a. It's a fascinating paradigm across.
You're teaching them to be pill pushers and to give the least amount of attention because you're. You're making them essentially slaves to their debts.
Sure.
And you have to work this hard to get enough money to even survive or to be able to thrive.
Very true, very true. And I think that that limitless, that like, bottomless access to. To cash for young people, knowing that they're going to have this grip on you, like student loans and all sorts of types. You can never forget the card debt.
Never get out from under.
It is incredibly. I could talk for hours about just that one piece.
It's wild. Well, and then you look at guys like Huberman are trying to do the right thing, get, you know, good information out to people and have real conversations around it. And they're not polarizing or they're not trying to be like WWF characters, you know, and spout their own agenda. You have, like, real balance and raising conversations also from PhDs at big colleges. So I think that's. That's a good sign as well. You Know, Lex, free people like that who are, who are spreading the good word and having detailed, nuanced conversations. And that's what you need, right? You can't just have sound bites anymore. We're not going to get anywhere. Sound bites. They got us into this mess, they're not getting us out of it. So anyway, that was a digression, but I'm obviously passionate like you about education and it's really interesting to see where the world's going with that. But all those, all those dollars that people are spending on education are now open for the best and brightest to come in and say, hey, yeah, I'll teach you. If I actually have a track record, I broke my heart. I took a marketing class in college and I asked where the guy marketed the professor, and he said, oh, I never had a marketing job. What are we talking about? Right?
This is unfortunate. It is unfortunate, and I will say, like the, they have part of the equation, right, in my opinion, where the, the criteria for actually contributing to the body of knowledge is very, very strict, unlike it is with, you know, the Internet and social media, with anybody with a keyboard key can, you know, quote, unquote, contribute in that way. It's kind of like the shift from traditional news outlets to social media, where you used to have multiple validated sources with credibility that, you know, may even hold up in court. Now it's just people who have an opinion and can, you know, spout whatever they want. Now in academia, you do get people who are, are not very seasoned in the actual field they're teaching, but they are imploring you to follow, like, this really rigorous process, ensure that the knowledge you contribute is approved by internal review board and has a variety of other sources, many of which are also not practitioners. So, like, one piece of the process feels really useful. The other piece, where you're actually having people who haven't done the work teach is, in my opinion, like a detrimental thing for the field.
Yeah, well, this is a good segue because we're talking about marketing. And the reason I initiated this conversation, I asked to reach out to you from Joe, is because of this market research formula, as I'm going to dub it. You can call it what you like, but I, I teach all my students that you need to talk to people, you need to be on the pulse of what's happening in the market. You need to ask them questions, you understand what kind of words they use to describe the problems that they're facing, and ultimately create offers that are in line with what they want. Right. Both on an individual level and on a more scalable level. When you start to see, you know, things that rhyme across multiple people, maybe you have something there. And when it proves out, like, I've had clients that, you know, launch crazy things like a mastermind for cops, I'm like, I don't know if that's going to work. And I taught him market research. You got 15 clients and 100 clients. Now he's a 600 clients. It's like, oh my God, we really have a real thing here. So, you know, being that giving, giving people that extra step of like understanding how to assess a market both on an individual one to one scale and a larger scale, how to make sense of the data, how to test your hypotheses and how to work towards, and ultimately a working theory, if you will, to use scientific parlance, allows you to be a better entrepreneur. So this is one of the strategies I think is so cool. And then when Joe told me the story, I'm like, Travis is doing this on steroids. I want to get it from the horse mouth. So tell us from the beginning, like where did this idea come from? What was the goal? What did you learn along the way and how did it go?
So I think that the story that he told you was a more recent one. So he and I worked on a business called Grow Flow. We ended up selling it in February 22nd and after that I kind of just did not want to jump back into building another tech company right away. Wanted to start.
What were both of your roles, just so I'm clear on how that went. So you worked at girlflow. What was your, both your jobs at girlflow?
I was the CEO and Joe was the chief revenue officer.
And what was the main product you guys were selling or service?
So it was a B2B SaaS and we were doing compliance, inventory management, point of sale and analytics and sales tools for licensed cannabis companies in the U.S. great. So, you know, anything that like happened within those facilities has to be reported in real time to their state government. Those governmental regs differ across straight line state lines pretty dramatically. And you know, we basically kept people in line with, with, with state laws. We ensure that they could transact business in a compliant way and be above board shops essentially. So it's something that, that they absolutely needed and we were able to give it to them in a way that, you know, actually real business value in so doing. So we went from pretty much nothing to industry leadership. Having almost 2,000 licensed companies, many of which had several facilities within about three and a half years and then exited to the largest fintech in the space.
Very cool. Okay, cool. So you're coming off the back of this, you're out of the game for a while. Do you have a family as well? I didn't ask you.
I'm married, but no kids at this point.
All right, so you're hanging out with your wife, I presume maybe you're just living the good life out in Los Angeles, enjoying soaking up the sun and then what gets you back in the game? What did you decide to do do next?
Yeah, I wouldn't say I was soaking up the sun really. I mean I, I was, was helping the, the parent company that bought the company for a little bit and then started to just think about other things and was just really having a good time in, you know, what is essentially a volunteer role as a mentor at, at the accelerators. Just trying to help founders who are day one and, and have really great ideas and are really intelligent try to learn the ins and outs of building a startup and not falling on their face too much in the process and said okay, how can I do this for a little while and actually get paid for it so that I can be my own angel investor in the next one? I prefer to typically not just let it ride with exit capital into a new company. I've learned that lesson the hard way over the years and try to build new capital beforehand. So like that's, that's just like a rule that I made after learning that lesson a couple.
Does that mean like keeping your chips safe and off the table and bringing in other people's money to start new ideas? Or is that more like, oh, I'm going to start really lean and then build something and then bring accelerating capital? Or what is, what does that mean to you exactly?
It could be one, one or the other and it has been one or the other in the past. At this point it was more so the latter where basically let me generate something from nothing and, and utilize that to bootstrap the next tech company and take any exit revenue and use it for other things. So that's the frame that I was looking at through. And while it's really the general public and most of startup land thinks it's really sexy to go raise venture capital and to be a venture backed CEO, it's actually a lot less, less exciting than, than people assume it is because for example, if you're a bootstraps business, especially these coaching companies, you're usually taking home a tremendous amount of money. In contrast to what a venture backed CEO takes home, even if their company is ten or a hundred times larger, they're effectively relegated to because of fiduciary duty to their shareholders, many of which are institutions.
You're not going to make more than 100 grand a year.
Yeah, you're, you're making between 100 to 250 a year. And the rest of your, your potential upside is all in paper.
Whereas if you have a legit million dollar consulting company, then you take home half of that.
Yeah, I mean, yeah, you can go buy real estate, you can go get involved in a lot of different things. Right. So I said, okay, well let me try my hand here and did some kind of more generic executive coaching for a little while. And really my focus for most companies that I start are it's usually on a couple different things. It's on H, it's on company culture, it's if needed, fundraising, but it's also on growth, like rapid growth systems. So we're talking, you know, high tempo experimentation, thematic experimentation, meaning we're choosing to only ideate around a specific metric and experiments to improve that metric and understanding the way prospects think, feel, behave, make decisions the way they do from a behavioral psych perspective. And we want to rigorously experiment and create almost like a psychological profile on a buyer just based on the behaviors that we see and the information that we gather. And developing themes from that information kind of blends a lot with a doctoral case study research, for example. So through that lens, it was a process of generating that information from the real market as quickly as, as possible in as inexpensive a way as possible before you run more robust, more expensive tests. So the potential goal at that time was how can I try this playbook, the one that I've been running in a really insular way without really telling anyone else about how I do what I do and how do I distribute it one by one over the course of time to specific customers. So one of the things that I ended up doing at the time, which I wouldn't necessarily always recommend that people do, they have to be very careful with the FTC and so forth and with, you know, any payment processors that you need to run in a compliant way. But what we did for a while was I basically said, we will double your growth rate in 90 days and if we don't, we're going to refund every dollar you pay. Plus I'm going to give you $3,000 cash for wasting your time. Now what we found was the people who would act on a growth Related offer of that kind were typically one of two kinds of people. One kind were people who were, you know, for whatever reason enamored with my resume and wanted access to me rather than what we were promising. So we would kind of like throw those people into one bucket and the other bucket were typically founders who had stalled out in their growth. They had plateaued. So we only had a few companies that were legitimate, growing companies that took us up on that offer because why tip over the Apple cart if everything is going well? So it was typically the people who really needed help that came to the table. But it was very, very effective in bringing people to the table who, who they needed help. That was far more basic than what I expected to provide to them. But it was really, really useful. Just that one frame. Because even though people didn't even have the context to understand half of what I just told you in terms of our systems for growth, a lot of them did not even really know what a well formulated experiment meant. So that was like we had to go back to day one in practice.
They didn't have the basic scientific theory. They didn't understand how to design hypothesis, design experiment, test it rapidly.
Even if they. Yeah, even if they knew in theory it oftentimes in their minds was something that successful companies do. Like, meaning we'll do this when we become successful.
Right, right, right, right. Not as a rule for throughout. Not.
Yeah, not as a method to become.
So you found a lot of. It was like teaching people how to think. So I want to clarify a couple points you made. So point number one, just to, to clarify the offer. So the offer was we're going to double your growth rate. So if you're getting 10 new clients a month, we're going to make sure you get 20 new clients a month in 90 days. You know, so you're doubling your growth rate or whatever that metric is, 90 days or going to pay you three grands or you don't pay and pay you three grand on top. So that you said you don't. So you collect the cash up front, Right?
Correct.
Whatever your consulting rate is and then you have this guarantee in place and then you basically check in, I'm sure you know, certain points throughout you're teaching them how to think as well as how to act and design experiments. What were the types of things that were the lowest hanging fruit in your experience of like what were the things that moved the needle the most for these people?
Yeah, it's a good question. I mean I'll say that the people there were only a handful of folks that took me up on the actual offer. The reason for that was to, to actually move forward on our end with that offer. We want, we needed to be in control of speed, so we needed to come in and actually like deploy a little fire team inside that company and have some base level of decision making power.
This wasn't just you, this was you and your people coming in to do this.
Exactly. That, that, that was what was associated with the guarantee that we gave in the ad. Right. Right. Now knowing that like, and that that price point started at 20 grand a month. Right. We knew that there were gonna, there was gonna be a pretty significant chunk of the market that didn't wanna go from like Nothing to a 20 grand a month deal. So there was also kind of a reduced like down sell offer that was essentially just like, hey, I, I'll tell you guys what to do, but you have to go do it. We, we don't have control of speed though, so we're not going to give you that same guarantee because we have, you know, every expectation that you're not going to move at the pace that you need to move because that's one of the reasons why you're here.
So you have this premier flagship offer which is only really going to apply to people who can afford 20 grand a month to start out with and believe enough in it that they want to do it and they, they're allowed to give up enough control or they can with their ego or whatever. You have people who are, you know, you're going to disqualify just because you, you know that they're just too far away from being able to, to double in 90 days. There's too many things that are missing and ultimately you get this whole wash of people who are less qualified. But still you can consult and now you're kind of off the hook a little bit because you're not making them that offer. You make them a different offer, like, hey, I'm going to charge you less, 5, 10, whatever it is, and I'm just going to consult you. And it's more like a group consulting at that point. Are you doing individual consulting or.
At the time I was doing individual. Honestly, I, and Joe has permeated the Internet marketing world so much that he's like familiar with all these structures. I came from kind of like the traditional Silicon Valley tech. I did not know anything about group coaching or anything like that. Right. I was, I was, and I, I wasn't the kind of person that like went and took A whole bunch of boot camps from existing Internet marketers or anything like that. I was, I was going to like General Assembly, I was going to the all the more Silicon Valley kind of educational events and so forth. So like, and that's one of the reasons why we work so well together because, like, we have such a differing perspective on so many things that when combined, that ends up being really powerful. But so it was one to one and I kind of treated it in the same way that I had with when I had executive coaches working on me all the time as a CEO. Like we had a certain structure of one on one conversations. That's just kind of what I innately assumed would be the best, best path forward.
I love that. Well, you know, side note on that, I love how different types of business and styles of business are starting to, you know, come together and share what's working. You know, like the Silicon Valley startup world for a long time dominated the, the biggest wealth creation engines that have ever been. And now a lot of that's trickling into the mainstream on the same side. Like a lot of these info marketers, coaches, consultants, kind of entrepreneur startups, SaaS people, agency people, e commerce people, they're all starting to share notes and understand how each other's business models work. And I've always been kind of a hybrid. Like I coach all kinds of people, so I love it because it gives me different insights. And I love listening to podcasts like Acquired, where they talk about the stories of how these companies came to be in their different playbooks. It's just great stuff and it just makes you sharper because you have different reference points. You'd be like, oh, this is the time that Costco did this, and this is the time that Home Depot did this, that, and the NFL and, and like all these random businesses that somehow are lodged in the back of your brain. You're like, oh, I have the right tool for the job, you know, or I know how to get there. So, okay, so let's just break down that funnel a little bit. So you're running ads, I imagine, on Facebook or some major platform, right? What was your, like, cost per acquisition when you're running that ad? How many conversations were you having per conversion? And what were you say, like, you know, dollars in versus dollars out. What did that look like?
Yeah, that's a great, great, great question. We, we probably could have done quite a bit more had I allowed more calls to. I just kind of have this weird hard and fast rule of like, I don't want to have but so many calls both per week and, and per day. You know, I like to kind of go deep on whatever I'm going into and I don't want to be interrupted and, and chat. So. But on the, the I'm going to go from memory here, I believe we were doing about between 28 and $32 cost per book call. Wow. And the vast majority of those, you know, did close, I would say upwards of, of 75% of them for you know, the first month or two. I then started to, to find that, you know, we were just getting these companies and their problems were so unique. Every one of them was as unique as a fingerprint and it would, I was used to having to solve problems for one company at a time that were like my, my businesses, right. So I could really, really go deep and get in the weeds and get curious and explore and experiment and, and all sorts of things. And when you're spread across, you know, 15, 20, 30 different companies and they're kind of relying on you for like to be the all seeing, all knowing oracle of, of success, the depth that you're able to get to with each one of them is, is not quite what you're used to. So I immediately, like after the first six months or so, really scaled that back quite a bit and we started to think a lot more systematically in terms of like, let's, let's cut down on the number of like really bespoke problem sets that we're dealing with and, and really take people through a more streamlined version of this, which is part.
Of market research too. In the beginning, you kind of got to work with whoever you can work with in order to see what kind of results you can get. Because it's one thing to do it yourself, it's one thing to build your track record, but you're never going to work on 10,000 businesses. That's insane. But there's a possibility you could interact with 10,000 clients over your career and you got to kind of decide like what are the lanes that you go in. So like when E commerce people go with me, you know, I know a little bit about E commerce. I had a successful E commerce agency, but I didn't know every job in that house. And it's changed so much. I'll usually refer them out to my old firm, right? I'll say hey listen, these folks can help you with this. Or somebody comes to me with like a tried and true like, like you know, newsletter publishing, you know, Agora type info product. I'm like Yeah, I could, you know, inform that and I could help you design a strategy around that, but I don't consider myself an expert on that. But then when people come to me with like masterminds, coaching businesses, like, I'm all over that. I know that inside and out. If they're like, I want to build a course, I go to my wife. Like, there are levels of specialization, but you got to try some of this stuff out in order to understand what you're great at and what you can really move the needle with better than anybody else. Because it's just so broad and every single one of these categories and you see so many people just winging it and like making the whole thing look bad. It's just like you gotta, you gotta fly the flag to the thing you care about. So where did you eventually niche down to and what problem sets did you initially eventually niche down to?
Well, oddly enough, I eventually niched down to going back and starting another tech company, which is exactly where I, where I expected to inevitably be like, get it. Because you know, really what we were trying to do was just kind of explore and I was chasing that type of fulfillment I would get from working with, you know, the, the accelerator programs and whatnot. And everyone is typically just so grateful for any ounce of insight that you can give them. And you know, to some degree that was also present in, you know, that business as well. And it was, it was fun for a period of time. But I definitely missed going really, really deep on to, on one thing and, and you know, my career like has had more exits than you would assume someone would have who likes to go deep into one thing. So I like, I beat around the bush. There usually is some multitasking involved, but it's like I'm usually a co founder but not CEO in a handful of different companies at any given time.
Is there concurrent startups? Are you working on one at a time or how did that concurrent?
Typically yeah, but, but usually I like, I don't like to CEO any more than one at a time if I can help it without, you know, there being a radical set of circumstances that, that would enable me to do so. Because usually at that point if you're a CEO or cfo, you do have that fiduciary duty if you have any other share shareholders other than yourself, like you have to really take that seriously and be as committed to it as you can. And there are a lot of CEOs out there that will try to hedge and multitask. Maybe they don't believe Fully in what, what they're actually doing. So they want to be doing multiple things just in case because they're afraid of starting from scratch.
Right. That quite often that's been a truth in my life. I'm being honest is like I have a couple of like right now things I know are working and I'm always kind of like looking towards the future of like what could I build? That's a cool tool for the future but you're never really fully in either then and it's just like it suffers on both sides. So I feel you on that.
Yeah, yeah, yeah. So I mean they're like where I inevitably landed. Like we. One of my clients that I was working with through that whole, you know, adventure, we took him to Exit and then he said, hey, do you want to co found something together? And I said, tell you what, build an mvp, get a couple customers and come back and, and talk to me and let's see what you got. And then maybe. So he did. It worked really well and here we are. So that was one. I had another investor that I had built a really good relationship with after a prior Exit who needed someone to come in and take over one of her companies. That is honestly one of the things that I do these days. It's not something that I ever intended to do and I can't really say genuinely that it's something that I really love. But because of the like Exit based track record I've built, there are a lot of folks who have like a more established business in, in their hands and want to take it to Exit, but absolutely have no clue what they're doing. And they'll sometimes tap me and install me as, as CEO so I can take it to Exit with them. So that's, you know, another one that I, I jumped in with. We are still, you know, working on some semblance of a similar problem set around, you know, kind of this just we, we would always kind of joke around and call it this fundamental ser. Like theory of everything for SAS growth. And that was what that consultancy was for. But trying to kind of productize that and you know, bring it into tech a little bit more. So that's right now a quest that we're on and we're actively experimenting. That one's early, the other ones are, are quite a bit later stage.
I love that. Okay, so your CEO, one at a time, you'll be partner on a business or advisor to a business and you kind of count that as like, hey, I'm on that team. Therefore if exit, that's one of my exits. But you're really only going to steer the boat on one at a time.
Well, I mean if I co found it and I have like co founder equity, I'll, I'll count it as, as an exit of mine. If I'm just an advisor, like as usually advisors, at least in the Valley, you're getting like a fraction of a percent of the company.
Right?
I wouldn't count that as something in my pocket.
Yeah, I'm always just curious about that because people throw these bendy words about, you know, that you don't really understand and would you consider yourself a technical founder? Are you a coder? Do you build the technology?
I would have at one point in time said that I, I could code. It's been many years since I really got in the trenches. I would never even joke about calling myself a software engineer. I wouldn't be able to build a, I could get something like some sort of MVP off the ground that would be clunky and would need to be completely rebuilt, but it could validate an idea, right? That's more or less what we did with one of these that we're building up right now. It's called Revada. And it is like the, the intention that I have moving forward is building like a private equity portfolio of businesses that grow businesses.
Okay.
The intention is to make sure that all of them are in some way growth related. And that is, you know, one of the, the levers of growth is what this particular company helps solve.
Okay, great. So you have all this startup experience, you've had all these, can we talk about your like, exit playbook or your philosophy around it or how you build things or what are the steps? Steps?
Yeah. So I mean, honestly, the steps for exiting are very similar to the steps for fundraising. And the steps for fundraising are very similar to the steps for enterprise sales. Or at least that's how I've, I've. Because a lot of people will think about fundraising, they'll think about exiting. Oh my God. You have to be in these like really big rooms with these like dark, shadowy figures with a lot of money and you have to go to Harvard or be part of an alumni network at Stanford. Who do you know? Can you introduce us to investors? And like that is a very real, you know, strategy for a lot of people. And it has not been anywhere close to the one that I've employed. I've, I've raised, raised probably a little over 100 million for my companies over the years. The companies that I've like built or co built and I have never thought that I had a network of investors to pull from for most of those like I've almost always done it completely cold and it's always been just like as basic of cold outreach process as you could imagine it being. So like to raise money effectively we would generate a list of companies that were either similar products, different space or same space, different products because we would want to ensure that we had a thesis fit with their fund. A lot of people assume that venture capitalists are rich people investing their own money. They're not, they're people with, with jobs investing money from other people. And so they have a specific thesis that no matter how good of a deal yours is, they have to follow by law or they'll be committing fraud. Right. Like they have to invest only in line with their thesis or they have to get an approval for their entire LP base which they wouldn't want to have to do.
Right, that would be an exception. Which is more of a hassle than just playing by the rules.
Exactly. Because they're going to have such a mountain of deal flow coming their way from a million different startups anyway. So like I would typically go out to let's say a list of 4 to 500 investment funds that we think might be in the neighborhood of a thesis fit. We develop a blurb. That blurb at the end of the day would end with a call to action. Can I send you more information? It's maybe a paragraph and three to five bullet points. Can I send you more information? Now those items in that blurb curb are going to be the most impressive things that we could have possibly come up with. Because by the time we're raising, we want to have some substantial wins under our belt. We want to be able to demonstrate why us, why this, why now. Is the demand real? What hypotheses have we validated in a concrete way that you as a fund are going to bet on? And then can you be confident that I'm going to be a good shepherd for your limited partners capital? And here's a path towards venture returns which means minimum 10 to 100x on their investment. Right. So then you know, if they reply in the affirmative, we send a deck. The next step is to get on a call.
So break down the numbers so 500 go out, how many come back and say yeah, I want more info, so on and so forth.
Yeah, it depends on the company, depends on the space. Like for something that is a little bit more generic, you know, maybe you get that one out of ten reply in any way at all, you know, may, if you're doing great, right from there you're sending the deck, you're, you're getting maybe one out of five that says, yeah, let's hop on a call. And you want to try to get to either a yes or a no. Like when I said you want to get to a no as quickly as possible. It's in the playbook of almost every venture investor to ride the fence for as long as humanly possible possible because they want to try to validate their own thinking with, you know, larger diligence teams from more successful funds. Right.
They want to see Sequoia come in, they want to see Peter.
They want to see somebody. Yeah, they want somebody impressive.
And then they could kind of ride the fence until it's like, oh hey, so and so's in, therefore we're in.
And yeah, so I'll typically press them right away and, and ask, look, I would love you to tell me whether or not this is a thesis fit for you in terms of what we're doing. Try to get a yes or no on that, that what are your diligence criteria of companies that you green light? Like what do you look for? Try to press for specificity on that. If we, if we don't have that at any given time, I will call it out and say it doesn't look like this will be a yes for you based on this criteria. Is that correct? And I, I want to try to get like a concrete answer for, from, from them like as soon as possible whether or not like yeah, this looks like good enough to, to take it to my boss, like take it to the general partners in the fund and take it to investment committee or something along those lines. But like a lot of them will be, most of them will be very cagey on providing information because it's in their direct best interest to ride the fence as long as possible.
Well, and that, you know, once that gets out in their minds, they don't want their special sauce being leaked all over the Internet where totally, you know, so and so does it this way and so and so does it that way. And now people are trying to game the system. They, they kind of want it to be a little bit of, of a, of a black box, so to speak true.
Yeah, they want, and honestly like I've in over the years like there have been a number of companies who that have not exited that I've like built or co built and one of them was a Fundraising tool to bring like more order to the chaos of startup fundraising. Founders absolutely loved it. Investors did not. They want fundraising to be hard. They want their founders to be capable of doing hard things. Like, yeah, you know, so like that, that's an on purpose thing for them. It doesn't necessarily make sense on every level, but on one level, which is like, we want to invest in founders who are capable of figuring out hard problems and figuring out hard puzzles and getting access to things that they would otherwise have access to. And that's like part of the, the gating factor of getting investment is like being able to prove that you're capable of doing hard things and not giving up because it's hard. Right? So like that is like it was something that I thought was asinine at the time, but in hindsight, like over the course of several years, like I've really started to understand why that's the case. Now I say all that because the process is very similar from an exit perspective, but it actually starts way earlier. So in some of the companies that I've sold, we've started to build relationships for exit before we even started building the product. Like, we would want to develop relationships with potential acquirers and the decision makers at those companies, like the CEOs and so forth, long before we even knew what we were building or before we had reached any sort of fit in the market. And the reason for that is, you know, their founders too, they're obviously busy. They're not going to, you know, make a massive bet just because you want it to happen. You want to plant the idea in their minds that you're almost like an egg that they've been incubating for, like in some cases several years before it's ready for them to acquire. So being able to work closely with them, building trust, building rapport, you know, like ensuring that you're establishing relationships, I think with grow flow. I had quarterly calls with every single other industry CEO that would, would even remotely like, allow, like, and a lot of them were much smaller than us. Some of them were much, you know, other, you know, industry players that were our size or, you know, direct competitors, I would still build really good relationships with those CEOs and share information. You know, if they were trying to hire somebody from our team, you know, and it was a good fit, we would allow it to happen and encourage it to happen. If, like, maybe that person had, you know, the potential to go be a leader somewhere, we didn't have a spot for them. Like, we would want them to go have that experience. So for that reason we were able to build a lot of really, really good relationships in that company. And one of those ended up being being the company that we exited to. And that was the case in most of the exits that I, that I've had. And honestly it wasn't something that I learned anywhere. It just was the process that made the most sense the first time I did it. And it worked well enough that I just kept iterating on that process over the course of time. Now that's obviously a strategic. You can do the exact same thing with private equity and like, you know, give those guys a call, like identify the funds and say what is your fund thesis? What are your criteria? What do you look for? How do you evaluate? Like we want to inevitably become an acquirable asset for you. Like tell me all the things that would make us one right now.
The end of the day you want to end up being something they want to buy. And the best way to do that is to be in consistent communication with them and be like, hey, where's your trajectory? We're building this. What do you think we should be looking at?
And ask like, what would make. Like this is what we're building. At some point in the future we're going to exit. It would be really awesome to exit to a company where, you know, we could create this one plus one equals three equation where like our, the whole is greater than the sum of its parts. Like for example, the company that we sold this last one to was meant to be an accretive acquisition because Regtech had a lower multiple innately on revenue at the time in the market than Fintech did. So they had like a. FinTech had like a 14x that they were getting in, could easily buy you for 21. Yeah, and we were. And like Regtech was, was going at like seven to eight. I think we ended up getting like eight and a half because we got a term sheet for that, that exact multiple from, you know, a potential investor. But just by making the deal with us, the acquirer was able to roll our revenue into their books and have that counted at a higher multiple than the one that they paid for. So like when you, when you understand like the little, the little like factors that make differences like that, like when you're building relationships with these decision makers, they will tell you exactly what they're looking for because they want you to become that. Like that's the thing. Like private equity investors that buy businesses want to buy businesses. Like one of the companies that I'VE talked to recently Constellation Software out of Canada. They own 800 plus SaaS companies. They've never sold one. They will absolutely tell any founder this is exactly what we look for when, when we're buying companies. Like these are the criteria that we want and like they want people to know that because they want to go buy that company at some point and they're worth about like $90 billion or something like that because of that.
Well, they're like the Berkshire Hathaway of SAS startups.
There you go. Yeah, it's a good, a good analogy. So like at the end of the day when, when you identify, you know, potential and now here's the exception. Like if you're like, oh, we want to go sell to Google or we want to go sell to Meta, getting time from Corp dev is going to be very difficult at organizations of that size because the kinds of acquisitions they're looking at, unless it's like profound, groundbreaking, really, really innovative technology, you're, it's existential to them.
They need to buy it, otherwise they're going to be screwed. Like Instagram.
Exactly like Instagram.
They got to buy it or they're to be losing market share rapidly.
Exactly. But even though like both of them were massive runaway growth stories, you know.
The, if it's small enough and they can catch it early enough, they'll just build it themselves and kind of deal your.
Yeah, that'll get them to pay attention but also just like scale will get them to pay attention. At the end of the day if you, if you have and it's not like patented technology isn't going to move the needle for them because they're so lawyered to the hilt that they're, you know, know they're going to take the screw your patents approach and go ahead and sue us.
Patents are always only as good as you, as you have the money to defend them. Yeah.
And at the end of the day like one of my companies right now is a patent pool. So like I know that's a space really, really well but like so exits are not nearly as complex as people think. It's just a long game relationship building process. And yeah you know, the earlier you can start working on better.
I'm making connections as you're speaking. It's like connection number one is it's just fascinating that you look at it as a math formulas like hey, raising money is not hard. It's just a series of phone calls. I remember an interview with Elon Musk. I brought him up earlier when he sold I think Zip2, when he raised money for whatever the second thing was, X.com he's like, oh, raising money is just a series of phone calls. It's just as simple as that. I just keep calling till I have the money I need. And if you know who to call, it's just how many calls I gotta make. So in your case was like 500, down to 50, down to 10, down to however many of those became deals. If you're trying to raise a couple million bucks, 3 million, 5 million, whatever it is, is like the money's there. What's, what's the average check size in Silicon Valley? It's got to be, you know, a couple hundred grand, I would imagine, at least at the minimum.
Yeah, it depends on the stage. I mean, if you're pre seed, you're probably looking at several hundred grand. If you're seed, you know, low seven figures, like 3 to 5 million maybe. And then A, you're looking at 10 to 20 maybe. And then it kind of goes, goes up from there.
Yeah. So the math checks out there. And then as you're building this, you know, with the exception of like Meta and Google are trying to eat the world and they can actually go after a lot of things at once and have entire companies within companies, companies. I think any savvy entrepreneur within a growing space recognizes there's 15, 20, 25 things that, that are going to win, but they can't focus on them all, so they focus on the ones that they feel like they're going to win at. And then they see somebody like you who's like building another part, they're like, oh, that's a good idea. Maybe I didn't think of that or I see how that's going to be accretive to what we're doing. We all want to kind of have a coopetition where we're kind of helping each other grow and grab more market share so that ultimately we can either like you say, be acquired or merge companies or get both acquired by PE companies. That doesn't hurt anybody because I literally could not capture what you're trying to capture. You got to focus over there with your resources and I got to focus over here with my resources. And there's like 15 or 20 of those, those verticals within the industry that, that somebody's going to grab up. So the more you can collaborate, the better in those situations. As long as everybody kind of, you know, recognizes this isn't personal, this is business. They don't get in their ego, they don't get in their feelings about it. It's like, hey, how can we all win here? More and more I have the saying, I don't need to know everything if I know everybody.
Right. That's a big thing. By the way, the, the last thing you said about not having an ego about it because like an earlier stage founder who hasn't gone through, whether it's fundraising or exit conversations before, when someone passes, they will get very defensive and they will likely burn the bridge on that relationship.
And it's always a pipeline issue. It's always, you don't have enough. Yeah, 100% of the time.
Yeah, yeah, yeah. And you're thinking that this person just doesn't get it. And, you know, who cares? Like, the, the, the approach is, is so incorrect though, because oftentimes, like, because a lot of VCs want to invest and maybe they would if they were angels, but they can't because of their thesis. And maybe you don't fit it because you're a year early or because you, you are participating in a space that they, they don't know anything about or something along those lines. Right. And. But oftentimes the people who pass are going to be a really great referral source to another fund that they know will be perfect for you. And you're only going to get that intro if they like you at the.
End of the day. I love this. So, okay, so in your. So one of the things that kills entrepreneurs is they can't move fast enough. And we talked about this thematic, you know, iteration and all that. How many experiments do you feel like is appropriate to be conducting at one time? And also how many in a, like, let's say a quarter or a year, however you want to track it.
So, I mean, always the caveat is it depends. Right, I'll skip that one. But you know, typically you want like, and it depends on things like how many experiments per segment of the customer journey. So you're not disrupting and corrupting your own data collection efforts.
You can't track and you don't know what's actually working or moving.
Yep, exactly. Another kind of. It depends on them. It depends on the size of your team. So you are not stretching yourself thin bandwidth wise. The main thing is like, you don't want what we call horse race tests where it's just like version A versus version B. Let's see which one wins. Let's test button colors or headlines or whatever and just see which one wins. The problem with that approach is, number one, like, you're not starting with an observation that you to want, want to explain. Like if you were to do this in an academic setting, you have to start with like this is a pattern or an observation that we, we see occurring or not occurring and we want to know why. Right? That's, that's an experiment at the end of the day, like learning why it's not just throwing a couple things out there and seeing which one wins because something is going to win. But then you don't know where to go from there. You don't know why it happened. You don't know how to spread that elsewhere in the business business. You don't know what to do to get more juice, like to squeeze more juice out of that moment. Right? So if you were to go in and basically say, all right, we're making an observation, we're forming a hypothesis around why this might be happening and our test is meant to validate or invalidate that hypothesis. Right. First and foremost we want to understand what makes our customers think, feel, behave, make decisions the way they do so that we can have them do more of what we need them to do and we can learn more of what we need to learn to build better solutions for them at the end of the day. Right. So that's like just foundational context in terms of what's enough. There's no real easy answer because you're always going to be experimenting like you should be experimenting constantly. And my opinion of like a minimum threshold you want like on any flow, on any customer journey journey that you've got on any like, you know, product in your, in your suite of products. I know a lot of people like funnels in, in the Internet marketing world. I'm definitely a lot more in the loop based camp like the, the Silicon Valley growth loop camp. There are utilities for, for both. But I love compounding growth stories a lot more than I like the linear growth stories. Funnels oftentimes lead people to have a high churn like plateau. Click. Funnels is a great example of that. Right? Like they're, they have a higher churn profile than any other company I've observed. So at the end of the day like one, one of the. One of you're not one funnel away is what I'm trying to say. Right. You're so, so like as cool of a marketing hook as that is, but one minimum three maximum on a per flow basis. And the reason for that is like any more than three, you typically end up corrupting your own data and you, you have more variables in the Mix than you know how to analyze or that you even know exist fewer than that and you're just handcuffing yourself on velocity. You really want to build the muscle internally of being able to, I mean, just have growth as the DNA of your organization. And growth comes from experimentation. And it is org wide. Like a lot of people use growth and marketings and honestly they're not growth like is anything that allows the business to grow. That's, that's not just leads in or sales made, right. It's also engagement. It's also retention and customer referrals and biomechanics. It's also developing things that are exposed to new customers through use of a product. It's your monetization, experimentation process. So what you're doing, your model looks like what your pricing looks like, what your frequency looks like. Like all these things are, are orchestrated through experimentation. Exactly.
Yeah.
There are also things that can cross pollinate. When you learn the basal psychology that leads people to do some of the things that you want them to do upstream, like if you really understand the reason why they made those decisions, you can reuse that knowledge downstream. Like we, we use a couple terms that sometimes are made fun of because they kind of have like a, a weird sexual connotation. But we use like drilling and plowing, right? So drilling is like we want depth. If we learn something in an experiment, like while we're like running a test or something along those lines, sometimes more isn't better, but sometimes it is and we want to know, right, if that is the case here. So how much more can we exacerbate? Can we agitate this, this particular psychological concept that we may have uncovered in this moment with this particular buyer? If we do more of this thing in this moment, what happens right? Then plowing is like, can we spread that benefit upstream and downstream? Where are the boundaries of this psychology in this learning? Right? So can we take the same concept if we just learn that someone is really, really responsive to, to loss aversion, Right? Just as like a random example here that might resonate with like an IM audience, they're really responsive to loss aversion. Can we play with that same concept a step prior? Can we play with it a step later, two steps later? Three. Like, what happens when we like at what point does the psychological roller coaster really take another dip, right? So like those types of questions are important to answer. And over the course of time as you experiment, experiment more and more and you're doing this correctly, you don't want to hold all this in your head, you want to start to compile some sort of, like, dossier on your, on your icp, Right. You want to have this psychological profile of what makes your customer think, feel.
Behave, make decisions the way that's your Insane Clown Posse. If you're listening at home. That's your juggler. No, it's your ideal customer profile. Right?
Correct. Yes, yes. So, like, you're.
You guys got acronyms too.
I tell you what. But anyway, so, yeah, at the end of the day, it's really important to note that a lot of that experimentation can happen outside of just like the A B test. You've got survey data, you've got customer interviews, structured, semi structured, non structured, et cetera. You have a bunch of other qualitative sources. You have session recordings and heat maps. You have, you have focus groups, you have lit reviews, you have interviews with other companies that have done similar things like. And that's just scratching the surface on the kinds of data sources that you can pull in in a wider experiment. Because we usually want multiple sources to really. Because at the end of the day, one of the things that I think is a big handcuff for a lot of newer, even more experienced marketers is like the, the 95 to 99% confidence interval in a B testing that a lot of the testing tools will require you to have that are very impractical for most companies to reach.
Right, right, right. Yeah. Just the amount of your data you need to get there is like, impossible for most companies.
Yeah. So they'll give up on experimentation just.
To pull out and kind of synthesize some of this knowledge. Because you dropped a lot on us. Okay. Experiment all the time, one thing minimum, three things maximum. Otherwise you're going to, you know, end up in a place where track your data, your KPIs are going to be all out of whack. You don't.
Three per theme per week.
Right.
So, like, for example, let's say we have a theme of like, we're looking at habit formation, which a lot of people call customer activation. We call it habit formation because that's the finish line. Like, this is this particular lever is done when the customer has created a habit within the product. And we, if we're looking at that this week, because that's where we feel like we're weakest from a, a point of leverage. We want between one and three experiments that impact that one thing launched this week. Right. And we want actively collecting data so that we can shift our focus to the next theme next week. So at any given time we might have 12, 15, 20 experiments running, as long as they're not corrupting the data that we're collecting from, from other flows like on, on too much of a, a degree degree. But our velocity of experimentation is almost always going to mimic the velocity of growth.
Yeah, and I love this. And just to give an example of what you described earlier is like the, you know, the one funnel away thing versus the, you know, like you got to market really hard to sell your product and you have high churn versus the, the viral growth loop that you experience with a lot of these products. Like I have an iPhone and then other, other people want an iPhone. It's like when you finally have an offer. And I had this recently where, where we were doing the special go high level deal where every time I sold one, three people would come to me and say, I want that. With no prompting, no advertising, nothing. It was just word of mouth, like, can I have that too? Can I have that too? Can I have that too? Like when you have an offer like that you realize like, oh, wow, okay, this is a really special thing. So it kind of leads me to my next question, like, what do you believe? And just let me know if we're, because we're running over a little bit of time is an issue. But what do you believe is like the window of opportunity when you find something that really works and you're like, okay, we're going to go all in on this. Like you, you know, you have a clock in some way or shape or form. Do you think your clock is getting shorter? Do you think it's getting longer? How.in your brain, like how do you treat that and go about it?
So it depends on how publicly we're building, right? And if, if we are building in public in some way or they're like, people are, we're marketing really hard and people see what we're doing. Like as soon as you start to become successful, you're going to get copycats. It's going to happen and it's oftentimes a signal of, of the fact that you're onto something. If there's demand in a market, it's not always a bad thing because if you're niching down correctly, you're going to alienate some prospective buyers that can be served by another company that's positioned a little differently. But you know, speed is one of the most important things for a startup for sure because you know the market conditions are going to change regardless of your, you know, your pace and how well you execute the things that might be true today in terms of how the prospect thinks, feels, behaves, and makes decisions are going to fundamentally change over time based on all the other things that they're exposed to. The products, the media, the anything, you know, the macroeconomic client, their climate. It's going to be, it's going to be a little different. So the striking. While the iron is hot and expecting things to change is, is, is going to be, you know, both are very important piece of advice.
Yeah. And that, that comes down to diminishing returns, too. It's like, hey, sometimes you can spend 50 grand a month, sometimes you could spend 500 grand a month. And it's just, you don't know what the, the diminishing return is until you push it. But I recommend when you find something that really works, you go all in as fast as possible and you get as much leverage as you can because you know the likelihood that something's going to go from 10 to 1 return to negative return overnight is pretty low. So while it's up in those kind of crazy metrics, I typically tell my clients, like, if you can get three to one, you can run a business. If you get five to one or more, you got to go all in. You got to do everything you can to, to, to. To get as much as you can while you can and, and build that business as fast as you can, because that window's going to close and you might get like 5 or 6 or maybe 10 or if you're really lucky, a few more experiences like that in your entire life and career where it's like everything is, is, is lined up in the right time and you're just cranking.
So, yeah, at the end of the day, I think the, the act of going all in as well, I think it's, it's both, yes, financially, but also just from a focus perspective. And for me, like, going all in kind of may mean something a little bit different than it means for, for most, which is like, oh, I'm gonna put all of my effort on this one thing. For me, it's, it's more like, how can I pretend that I don't know everything on this area? How can I treat myself as a, an absolute beginner and collect as much knowledge as I possibly can and continue to treat myself as a beginner? Meaning, like, going all in. Yes, it means focusing a lot on the business, but it's also talking to as many smart people about the problems that the business is having as possible and being open to Experimenting with what they say, regardless of what you may think. Because at the end of the day, you know way less than you think you do on any of the things that you think you're an expert in. And oftentimes the entrepreneurs that you talk to are going to know a lot about a very, very unique shape of one business type. Right. So the standard wisdom that got you there is, is typically going to keep you there and you have to go on a quest for 10 to 100 times more so that you're able to really get like unique insights on what would be fundamentally true across the board. And, and also just like what would be TR particular shape of the company. Because like, let's say you have the, the identical company in every single way, but serving a slightly different buyer. The psychology is going to be so different in many places that most of the tactics that work in company A will not work in company B. Right, right. So it's, it's, it's always a, an interesting puzzle to solve. What we call full fit, which is market, model, channel, product and message. Like we need all those five factors to bidirectionally fit with one another in order to like prime a business for rapid growth.
So you say again, market model, product.
Channel, product and message. A lot of Silicon Valley talk about product, market fit, those are important, but it shouldn't end there because if you can't articulate the message to the market, they're not going to resonate with the product even if it would already work for them them. If you can't deliver that message in a cost effective way through a channel. Right. Then the, the market is never even going to hear the well crafted message to begin with. And if none of that does a good job at describing the product or the model, if that business model doesn't align well with the economics of that channel or the, the ability or willingness to pay of the, the market, like none of this is going to matter anyway.
Right?
Right, right. So like all those factors have to fit with one another and over the course of time you can experiment around those as well. So like having a tighter fit at any given time is, is always something that can help the business grow faster.
I love that. Travis. Okay, so we've talked about a lot. I feel like I could talk to you for 10 hours. I'm so grateful for your time today. Any, anything you got going on right now you want people to know about, any links you want to share. How can people learn more about you and get to, to learn more from you and maybe work with you in some capacity.
Yeah, great question. So I'm not super active on social media. I want to kind of be clear about that. I would love to tell people to go follow me on Instagram or Twitter, but there's really nothing there.
Fair enough.
You can if you want.
I googled him earlier and I got a guy that does breath work and it's not.
Yeah, I'm, I'm pretty like anti social media. There's a reason why like 42 states are filing a class out action against, you know, social media companies. It's, it's toxic for your brain as a founder. Like a big chunk of your ability to succeed is managing your own psychology. So it's a very stressful world that we live in and if you don't have the ability to temper that and have people working on you at all times, you're, you're going to fail. So like in terms of like how to get in touch with me, it's, it's not super easy. But what I would say is you can, you know, reach out through my website, travesteffen.com it is not updated. Like there's nothing that, that really gets sold over there at this point. You know, it was an old newsletter that I had but you can reach out. I do respond to emails and you know, LinkedIn messages here and there if they're pertinent in terms of what I got going on. Like one of the companies that would be appropriate to chat about here be Ravato. So it's fairly early in our journey there, but a little less than a year old. But the company is one of the more effective ones early on that I've ever been a part of. And we are trying to solve churn for subscription based businesses. It's a tall order but we've already become pretty successful at a halting involuntary churn, meaning clients that just, they turn out because, not because they voluntary voluntarily elected to cancel, but maybe their billing fails, maybe it's uncollectible, maybe you know, they have other issues. We essentially solve that in a completely hands off way. About an average like 86% recovery rate on all involuntary churn. So we bring that back into your, your business. We also also have voluntary churn prevention and deterrence. So like those are, we basically have like AI plus human bespoke negotiation and dialogue with any customer who's even remotely considering churning to make sure that they can get what they need to stick around within the next month or so. We'll do the same with chargebacks. You Know, kind of having elimination on that front. And right now we're hard at work at predictive indications. So it means like if we feel that the engagement level of your customer is dipping below a certain threshold, we then launch targeted personalized messaging to ensure that they can get re engaged so they don't run the risk of becoming a potential churn. There's no hard cost associated with it. It's all 100% performance based pricing. We take 20% of what we save for you in the month, we save it.
It. That's a killer offer too, by the way. It sounds like you're pretty good at making offers. Just saying.
Thanks. Yeah. So it's, it's, you know, let's say we save $1,000 a month customer for you. We, we take 200 bucks one time. The next month if they pay, it's all, it's all back being yours. But that would have been a customer you lost anyway. So you're paying with house money and we just do that on autopilot. You don't do anything except for receive notifications. When we save people, we do send out digests around why people are potentially churning as well. So you have the ability to, to solve the problem at the end of the day, which is against our best interests. But we do it because we want to really satisfy the customer. So that's what we do over there. There are a lot of other things that we're playing with. For example, getting customers through trial. We're in alpha testing for one of those. And again all this is 100% hands off. Once you're onboarded and configured, which takes a couple days, we, our system takes over everything and our people monitor the system every single day. And we have private slack channels with every customer to ensure that they're able to be as involved or not as they want. And we have customers all over the place on that side of things. But usually the lowest per month mrr customer that we would take is about 40 to 50 grand a month. Right now our customer that has the most is probably around a million bucks a month. Month. But any recurring revenue business can, can come and, and chat with us at Rado.
So I love that, that's, that's beautiful. And it's a helpful service. Right. And the fact that you're doing it with the way like hey, we're not only going to plug your leaks, we're going to help you, you know, make sure that you don't have leaks in the beginning.
Yeah, yeah. Some companies aren't doing anything on this front, some companies are using like standard stripe dunning and, and doing very a bad job at this sort of thing. And then other companies are doing really well, but they have a customer success team deployed on this that are spending dozens of hours a month doing it and that time can be better allocated elsewhere and just pay people exclusively on commission to, to make it happen.
Well, Travis, you're a legend. I appreciate you. I've heard so much about you. I'm so glad we got to connect more. I know we've met briefly before, but this is a really great deep dive and understanding who you are as a person and what you care about and just the, the fact that you give back to entrepreneurs, you know, you've had lot of success. You could ride off into the sunset. I know you'd be bored as hell if you did that. But it's nice to see you in the game and keeping building things and pushing forward. You can find Travis at Travis Stefan. That's Travis spelled the normal way s tfn.com and you can reach out to them there, send them a note and let them know you listened. And you, you got some sort of value from this podcast. So thank you so much for being a part of this, Travis. I'm grateful and we'll talk to you next time.
My pleasure.
More from Brad
The #1 Reason AI Isn’t Working for You (Yet) #AI #businessowner #founderenergy
What tasks would the best assistant ever be able to do for you? #BusinessSystems #BusinessOperations
Nobody expects you to use a harder way when there's a better way. #AI #businessowner
Which side of the table will you be on in 2026? #AI #Mastermind #BusinessOwner