A speaker defines financial freedom as automating wealth creation across businesses and tracking net worth as your retirement scorecard. He targets $300,000 saved yearly and $8 million liquid by 55 to fund retirement to 90, while aligning money goals with personal values like faith and family.
Questions this video answers
$25,000 per month (stated as '25,000 a month').
About $15,000 per month (stated as 'like 15,000').
$300,000 per year (after tax).
$8 million liquid by age 55 (14 years from the talk).
Wells Fargo.
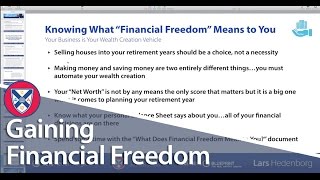
Foreign. This isn't necessarily real estate related, but I want to take you through an exercise and a spreadsheet that I created in Google Docs. It's fine. It's financial freedom. And so I want to talk about what knowing what financial freedom means to you. I consider my business to be my wealth creation vehicle. So I know a lot of real estate agents that are selling real estate way past the point where they really want to be selling real estate. So selling houses, you know, into your retirement years, this should be a choice, not a necessity. And I see a lot of. I'm working with a client now who's 42 years in the business and her husband's working seven days. This is a private consulting client. Her husband's working seven days a week, and she's working six days per week. Because they're both in their 70s and they don't have the money they need to retire. And it's sad. I mean, they may love real estate, but I don't know anyone that loves real estate that much where they're gonna be working into their 70s, working all hours of the day and night. Making money and saving money are two entirely different things. You must automate your wealth creation. So I have a system, and I do this for the multiple businesses I have where each business contributes to a wealth creation account. I have all my accounts with Wells Fargo, and they all give money to a wealth creation account and a tax account. So I put. I think I put 25,000amonth into a wealth creation account, and I put like 15,000 into a tax account every month. And so my tax account is building. So when I do my quarterly payments, I've got the cash there and my wealth creation, I take money from that account and I give it to my money manager on a monthly basis. So you have to automate that process. So this process is automated. Your net worth, it's not the only score, right? Obviously, the relationships and, you know, your faith and your health and all those things really matter a lot of. So your net worth is not the only score that matters, but it's a big one when it comes to planning your retirement years. So that's the scorecard that I use when I measure the effectiveness of the time that I dedicated to business or sort of to working. The scorecard is how much money did I put in the bank this year? So my goal is to put $300,000 after tax into my wealth creation account, into my. This vehicle that I've created. My goal is to put $300,000 away each year. And it's a deliberate plan. There's no. I didn't start at that number or anything like that. It's to live an amazing lifestyle and to put $300,000 away each year. And I work with a money manager who has a living balance sheet. And so I constantly know my net worth. And I have a goal of having $8 million liquid by the time I'm 55. So 14 years from now, I need 8 million to have the choice of retiring and not having to work at all. If I live until 90, I think is the age that we picked. So you have to be able to make those conscious decisions. So you have to know what your personal balance sheet says about you. All of your financial decisions are on there. So I'm like, big. I've realized over the last handful of years, as I've built a team and I've interacted with a lot of people, that personal responsibility is just huge with me. And all of the decisions that you've made, all of your financial decisions are on your balance sheet. So when you look at your net worth and your ability to generate income, the decisions you've made are on there. So if you're, you know, solo practitioner and you've got leads coming in that you're not calling, or you know that decision not to prospect is going to impact your financial situation. And so anyway, so just know that that is one scorecard that is unbiased. And it's too easy to say that money's not important or it's not the only measure. And I totally get that. Right. Cause I'm. I have faith above everything else. And I have family. My wife first and then my children, and then I'm a good son, and I'm a good brother, and I've got friends. So all that stuff is extremely important. But this is the one measure that we. It's pretty objective.