In this solo presentation, Mendell Gosnell, CPM, argues that cash flow, while important, accounts for only about 20% of the long‑term wealth generated by rental real estate. He explains that cash flow is inherently variable due to capital expenses, tenant turnover, market cycles, and economic shifts, and that owners who judge performance solely by monthly cash‑flow numbers often make reactive, wealth‑destroying decisions. Gosnell introduces the 80/20 principle, detailing the three other primary wealth drivers—property appreciation, mortgage principal paydown, and tax advantages (depreciation, interest write‑offs, lower tax rates). He stresses the need for adequate reserves for capital improvements, regular asset‑level evaluations, and a long‑term, portfolio‑wide perspective that mirrors stock‑market investing. The talk also clarifies the distinction between property management (day‑to‑day operations) and asset management (strategic, owner‑driven decisions), warning that owners are ultimately the asset managers unless they hire a dedicated professional. By adopting a tempered, long‑term view and recognizing all four wealth drivers, investors can avoid premature sales, under‑investment in maintenance, and other short‑sighted actions that erode wealth.
Chapters
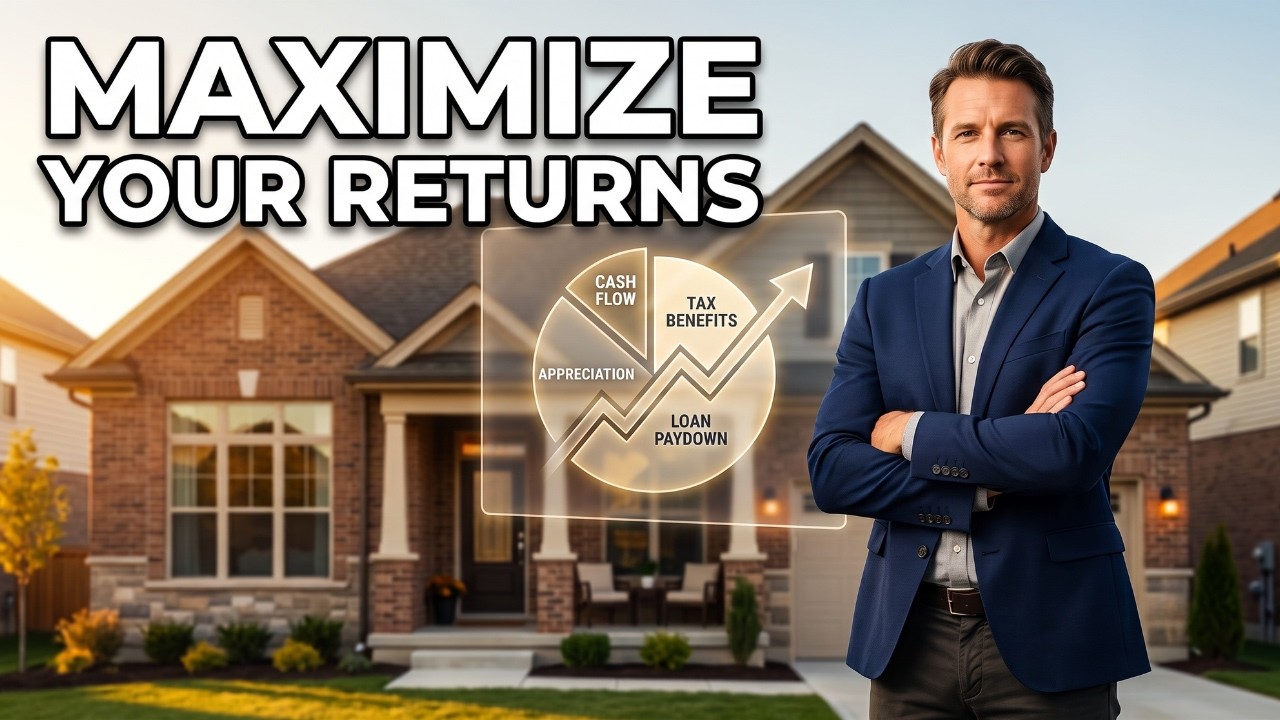
So cash flow isn't the whole story and why focusing on it alone costs investors millions. So let me start with something that I hear all the time from property owners as a property manager and things that I've said myself or think sometimes each month, like I didn't get any cash flow this month or my owner disbursement was low or why was my payout smaller than last month? And those are all fair questions. Cash flow matters. Anyone that tells you that cash flow doesn't matter is, in my opinion, not correct. However, I do think that focusing only or exclusively on cash flow misses the bigger picture. And some, some people would say that there's a little bit of a principle in long-term investing in real estate that's the 80/20 principle, that 20% of the value long-term in the real estate is going to come from cash flow and 80% is going to come from the other 3 drivers, the tax benefits, the appreciation, the mortgage paydown. So I want to take a look at some of those things in this video. You know, cash flow becomes— if cash flow becomes the only lens that you use to judge whether a property is performing or working well, you can really end up making decisions that quietly destroy long-term wealth. And I see it happen far more often than most people realize.. And one thing to keep in mind is cash flow is not linear. And here's the first thing investors need to understand. We want stable returns. I get it. And on a portfolio basis, whether it's my portfolio, the portfolio at large that we manage, or investors that have a number of properties, their cash flow is fairly stable. But any one property at any given time might not be. And there's a couple factors that you can do to improve that or mitigate against that. One is having a reserve set aside for capital improvements that are going to happen. The roof is going to wear out. You're going to have to replace things over time. And if you're planning on paying for that out of cash flow, your cash flow is going to go up and down. And so real estate doesn't move in a straight line upward month after month. Again, that cash flow is going to be very variable. Even well-run properties will have lower months, uneven years, and periods where cash flow dips. And that doesn't mean anything's broken. It doesn't mean call up your property manager and yell at them for doing a bad job. That's just normal. I'm speaking from firsthand experience. I've been investing for over 20 years, and I can tell you there are years where performance is lower than the year before. There's certainly months that are phenomenal, and then there's months that are very painful. Over time, I've realized that it does normalize, and the more that you can do to do your annual evaluations, stay on top of deferred maintenance, set aside adequate reserves, and anticipate the water heater going out, anticipate the turns coming, and, and doing that does help to normalize your cash flow. It's not because of bad management, it's not because you've done something wrong, But because real estate is a real physical business operating in the real world, cash flow dips happen for a number of reasons, like I've mentioned. But just to kind of reiterate, it's capital expenses like roofs or HVAC or plumbing issues. And again, those are going to happen. You need to be ready for those. You need to anticipate them and be prepared. Capital improvements that also raise future rent, right? So they all— it is an investment. You are maintaining that property, you're keeping it up, you're improving it. And there's going to be economic shifts like interest rates or inflation, or a lot of inventory is going to be dumped on the market and then the vacancy is going to go up, right? And so things are going to change over time. Normal turnover and leasing cycles are going to affect cash flow, right? And you might get in there and just experience bliss right from the beginning. You get the best tenant, they end up staying there for a decade, and and then all of a sudden they move out and that's your norm. And then all of a sudden you get a tenant that only stays a year and they move out and your cash flow dips and you're like, what's going on? You know, what's changed? It's just good to keep in mind the long-term trajectory of real estate. So if cash flow were perfectly smooth, it would mean someone was probably deferring maintenance and hoping nothing goes wrong. That's something we do see when we take over management as we get in there, we gotta cause a little bit of short-term pain bringing the properties up to speed. That does impact your cash flow as well. We wanna encourage our clients and educate investors to really have that perspective shift. So for instance, you know, when you think about your rental portfolio, you might compare it to your stock portfolio. But if you track your stock portfolio all the time, you'll see that it varies as well, goes up and down. And so, you know, here's a comparison that usually resets expectations. A lot of real estate investors also invest in the stock market. So let me ask you this: how much monthly cash flow does your stockbroker send you? Okay, so some of you might be dividend investors and you actually might take those. A lot of people that do dividends, at least early on, are reinvesting those dividends. But the reality is, is most people are checking their stock market, their brokerage account, and they're going to see it go up and down, and— but they're not getting checks Mendell Gosnell like they do for rental properties, right? And most people aren't getting those checks at all from their stock portfolio and maybe dividends. But usually those are again reinvested. And yet you almost never hear someone say, "Oh, my stock portfolio didn't cash flow this month." Well, why? Well, because people understand that stocks create wealth through appreciation compounding reinvestment and time. And you weather the ups and downs over time. And real estate works the same way but with an advantage. Real estate often produces consistent cash flow and all the while it's generating long-term wealth. Again, thinking about that 20/80 principle. A lot of times people are just focused on the cash flow portion whereas a lot of times the cash flow is going to be the smallest portion or make up only 20+ percent of the 80% of the wealth that's being created with that rental real estate. So, cash flow is powerful. But it still is only part of the pictures. And again, I've done other videos on this regarding the 4 wealth drivers of real estate. And this is where investors get into trouble. Cash flow is only one of the major wealth drivers in real estate. Just to kind of Recap, those 4 most common are cash flow, which is number 1 at the top of the list, everybody sees. But the other ones are not as apparent, and so they don't get the focus, and a lot of people forget those, or some people don't even realize that that's the big reason that makes investing in real estate so powerful is the number 2 one, appreciation. Now that goes up and down, and we've come off of a 10, 20-year period where appreciation has been pretty good, slowed down in the last couple years. But then number 3 is the loan paydown. You rent it out to a tenant and they're paying rent which is essentially helping subsidize your expenses or paying down your loan. And that is kind of like a forced piggy bank. You're— And you're also able to write off the interest payment as well. So, the tenants pay it, you get to write it down and then your loan gets paid down with inflated dollars again. So, there's a lot of additional benefits for real estate. And then the 4th wealth driver is the tax advantages. And this one's very hard to see unless you talk with your CPA and you still might get the explanation from them and still scratch your head and say, I don't really understand. But the reality is, is the money that you're getting from real estate is taxed, one, at a lower rate. You can take depreciation and that helps to minimize your tax bill. So it's hugely powerful. And I just encourage everyone to take a look at that more and realize that and not get so stressed out on just the cash flow. So, you know, 'cause when you focus only on the monthly cash flow, you're ignoring those 3 other forces that are still building wealth, even during a low cash flow period, right? So as long as you're making your, you're holding onto the property through the challenging times, For the long period, it's just going to continue to compound over time. And that's how short-term thinking leads to long-term regret. I've seen it so many times, 20+ years doing this. People have a bad stretch and they're out, they cash out and they're done. But those that weather the storm, I've never seen anybody hold for the long term and regret it. But I have seen unrealistic expectations. Expectations kill long-term success. One of the biggest dangers of cash flow only thinking is that it creates unrealistic expectations. Real estate is not a get-rich scheme, although you might see a lot of people talk about that. It's, as they say, overnight success takes 10 years, and that is so true with real estate. And it's not frictionless. It's a business involving people, properties, laws, and maintenance, and when owners expect cash flow to be perfectly smooth and always increasing. You know, a normal down month gets interpreted as a crisis, and that's when bad decisions happen. And I can't emphasize enough how I really want my clients and those who are watching this to really understand how important it is to have a very tempered, long-term view and not just microscopically looking only at cash flow. Cash flow, hugely important. But it, again, it is one of the four main primary wealth drivers with real estate. And so, those bad decisions, I've seen it again and again. It really, it leads to selling or selling too early or selling in an inopportune time when you don't have the advantage, you know, or cutting maintenance budgets. And, or rejecting necessary improvements, or constantly switching property managers hoping the problems disappear. It's the property manager's fault, and sometimes it is. The reality is, is a lot of times it's just the market. It's just the natural course of owning real estate. And sometimes owners stay invested, but they still make reactive decisions that reduce performance because they're trying to force a clean spreadsheet onto a messy real-world asset. In summary, the hard truth is you're the asset manager, right? We're the property manager and we do a lot of asset management and asset management type things that a lot of property managers, plain property managers, don't do. But the owner really has to be the primary asset manager unless you're specifically hiring a third-party specific asset manager, different than a property manager. A good property manager is going to be kind of like an asset manager. But here's the part many owners, you know, don't want to hear, unfortunately, is that, you know, if you didn't hire an asset manager, you're the asset manager. So it's important for you to have this understanding and this perspective to make good decisions. You know, your property manager handles operations, leasing, rent collection, maintenance coordination, the legal compliance reporting. And a great property manager also provides insight and guidance like we're doing right here. And you know, the best ones absolutely do a lot— the lion's share of the asset management. But at the end of the day, the decisions rest with the property owner. You got to have a long-term strategy, a long-term perspective. And that just really sits with the property owner because only you fully understand your goals, your time horizon, your risk tolerance, and what success actually looks like for your portfolio. I hope this has been helpful, informative, and helps you to lower the stress and look at the bigger picture, have a longer-term vision and just hold through the challenging periods and think about the other wealth drivers. But then understand the difference between property management and asset management and understand that real estate really is a phenomenal investment. But you do have to have that long-term perspective in mind. So, again, thanks for watching. And we just want to encourage all of our clients and those that are beginning the journey or somewhere, uh, along, hold on for the long term and you won't regret it. Thanks for watching.