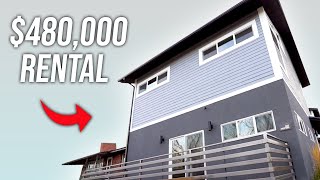
A $480,000 rental near Midtown Reno generates $657 monthly cash flow on a $120,000 down payment. Over seven years, the speaker projects $355,000 total return from appreciation, principal paydown, and cash flow combined, a 300% return on the initial investment.
So I just purchased these new rentals near Midtown Reno. Here's how I got in the deal, and here's what the numbers look like. So we start with a $480,000 purchase price. I put 25% down, which is 120k. That leaves me with a loan amount of 360k at an interest rate of 2.875. The monthly principal and interest payment is 1493amonth. Add $250 a month for taxes and insurance on this house, brings me to a total payment of 1,743amonth. This property rents for $2,400 a month. That leaves me with $657 a month of positive cash flow. $657 a month of cash flow works out to be $7,800 annually. I plan on holding this property for 7 years. Over 7 years, that's 55k total. The property value starts at 480k. This area is appreciating at 6% annually over 7 years. The resulting value would be 721k. That's a total gain of $240,000 over 7 years. The loan balance starts at 360k over 7 years. The new loan balance will be 300k. So that's another gain of 60k of principal pay down that the tenants paid for me. So to summarize, we have $240,000 of planned depreciation over seven years, $60,000 of principal pay down, $55,000 of total cash flow. So over seven years, my total return would be 355,000. That's a 300% gain on my initial 120K investment, or 43% annually. So to summarize, we have $240,000.00 of appreciation over seven years, 60K of amortization, 55K of cash flow, for a total return of $355,000. And when you look at these three things total, I think people sometimes don't consider all three together. You know, obviously people think about appreciation, but many calculators don't even count for appreciation. But my strategy was to buy in high growth markets with extreme population growth and extreme job growth. So that way I can get a 5 to 6%, which isn't asking for very much. If you annual rate of appreciation and then that amortization people don't think about this. They miss this all the time. The balance goes down every payment that is made on that mortgage, and the tenant is making the mortgage payment for you. So every month that balance slowly goes down and over seven years it isn't much, but it adds up to a pretty good figure, 60K. And then that monthly cash flow is huge. You know, if you can get into the current interest rate environment allows you to get a higher than normal monthly cash flow because your debt payment is low and your rents keep rising. So it's a weird thing where for the first time in many years you can positive cash flow many properties that you couldn't do in the past. That total figure is pretty insane when you think about it. And it leaves a lot of room for error. Like, you know, maybe this figure doesn't pan out as much, but you know, these other figures compensate for that. So when you look at it all together, you have multiple ways to win and it adds up to a huge total return. And when you look at this figure, you wonder why aren't more people doing this? Like why aren't, why aren't we buying 10 of these properties to get this total return over seven years and maybe do that, buy 10 of them. And over seven years you've hit your target for retirement or whatever your goals are. And my last quick point on all of this stuff is, let's just say, you know, for sake of argument that the appreciation target I'm using gets cut in half or let's cut it in a third, let's you still have the other two things and you still have a strong total rate of return. So that amortization, that balance is going down every month regardless that cash flow is locked in. Because I've locked in the debt on a 30 year fixed mortgage, right? So that spread between what I have to pay every month and what the tenant's going to pay in rent is locked in essentially. I didn't even account for the fact that rents may increase over the next seven years, right? So it does leave some room. These properties were brand new construction, so I didn't account for very much in the, in the way of repairs. But even if you threw in some budget for annual repairs, that would still leave you with a very, very strong rate of return, right? So I know there's quicker ways to make money. You know, in Bitcoin you might be able to make that same amount of money in one year instead of seven years or in Tesla stock or whatever the hot fat is today. But the thing is, with a lot of these investments, most investors lose a lot of money, right? Short term traders lose. And for me personally, I prefer to put my money to work in a hard asset like real estate that I know is going to be there that I know it's going to pay off in the long term and I don't have to worry as much about the volatility. Right. So I can sleep at night. So this is definitely a strategy for the long term. And it's not like get rich quick, but it's more like get rich for sure.