
The Private Equity Playbook That’s 10 Years Ahead of the Curve
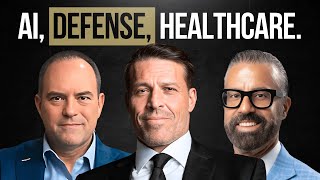
Ramsey Musallam of Veritas Capital, which manages over $50B, invests at the intersection of government and high-tech. He sees $1.2 trillion in U.S. healthcare waste and $180-200 billion in supplemental defense spending as opportunities to deploy AI and data solutions where government is the customer funding R&D.
Questions this video answers
October 7, 2025.
> $50 billion.
First fund ~$175 million; third fund ~$600 million.
About $25 billion in aggregate revenue.
Approximately 55–60%.
Chapters
Hey, it's Tony Robbins. And welcome to the Holy Grail Investing podcast. We are involved in protecting citizens across the globe through companies we own. In this episode, my co host sits down with Ramzi Musalam. He's built an incredible track record by investing in mission critical technology companies across national security, defense and education. At the end of the day, the world's not getting any safer. China has stolen all of our ip in that realm, we're quote, wasting, but there's elements where we need to spend more.
Most people went like, what? Did he really just say that?
Where do you see the greatest opportunities to not just make a difference on the battlefield, but also generate a good return?
We've been investing in companies involved with AI for decades, providing analytics to the President, United States.
I'm sure you've heard some very troubling things. Maybe you have a great therapist on speed dial.
Yeah. We're going to see things the next five to ten years that are unprecedented.
I've got a three year old grandson and a six month old granddaughter. How do they prepare for a world that is changing so, so fast?
It hits home differently when you think about loved ones.
I will tell you this, and I've been very direct with the President.
I'll ask for your forgiveness in advance, but I'm going to ask you a completely unfair question.
I love Ramsey personally, because his story is one of an extraordinary sense of resourcefulness. He is the CEO of Veritas Capital. Under Ramsey's leadership, Veritas has grown to over $50 billion in assets under management and, and he's consistently ranked among the top performing firms in private equity. He's overcome extraordinary challenges and he's been able to execute with purpose. This conversation is powerful. Let's dive in.
Hello everyone and welcome to the Holy Grail of Investing podcast with Tony Robbins and Christopher Zook. Very, very pleased to be joined by Ramsey Moussalam today and my co host, Mark Wade. Mark, glad to have you.
Good to see you.
Good to see you. Thank you. Yeah. It's my pleasure to introduce our guest, Ramsey Moussalam with Veritas Capital. I think that there's many things about Ramsey that make him interesting. I think all of our guests are interesting, but with Ramsey in particular, I'll point out three. The first is that he's the CEO and managing partner of Veritas Capital. It's a very large private equity firm based in New York with a specific investment strategy that we'll get into today. But beyond that, he's the son of a First generation immigrant, which I think is super cool for our guests to learn about. And then finally, he's a bit of an international man of mystery. So he is very one of few people in the world who has as a private citizen, access to some of the most important, sensitive, confidential information that our government has in terms of secret clearances. And somebody who grew up in the military and who has active duty family today certainly know what it's like to walk around with that and the care of it. So, Ramsey, thanks for, thanks for being here, man.
I appreciate it. Thanks for having me.
Absolutely. Let's kind of kick it off for the audience, if you will, by just tell us your origin story and you know about the early years of Veritas.
Yep. No, I'm happy to go through that. So, yeah, a bit of a unique story in that I actually was not even born here in the United States. I was born in Amman, Jordan. And the thrust and kind of the genesis behind that was that my father actually came to this country and was the first in his family at the time to go to college. Studied civil engineering down in University of Missouri, Rolla School of Mines. And after he graduated, he actually worked for the government Department of Transportation and then actually the Army Corps of Engineers. And so that's when the journey began. And I not only was born in Jordan, I actually lived around the world until I returned back to the United States shortly before high school or I came to the United States before high school. I lived in exotic areas and unique areas such as Jeddah, Saudi Arabia, Riyadh, Saudi Arabia, of course, at Amman, Jordan, and Mabel, Tanzania. So. And at the time, again, he was responsible for building roads and bridges effectively in the middle of the jungle. So I, I lived in a camp for a few years, a couple years in, in the jungles of Mabel, Tanzania, where I actually learned through correspondence. There was no schooling, so everything at the, at the time, there was no Internet, so learned through correspondence, mailing to and fro work and, and you know, that's how I actually spent my childhood. So I think that obviously is a very important part of, you know, who I am. You know, needless to say, say, having lived in unique areas, different cultures, it really does embody a lot of what I hoped to bring to the. The world I live in today as, as CEO and, and managing partner of. Of Veritas.
Well, I mean, at Veritas in the early years, you had to deal with a different kind of challenge, but it's still a very, very big challenge. Tell the audience about what that was like. And how you had to overcome, you know, what is a very different type of, you know, scary situation. But what did you do and how did you do it?
Yeah, so I mean, just a quick high level and, you know, step back relative to Veritas. You know, during business school I went to, you know, again, Chicago Business School, University of Chicago. And I had the great fortune of working for a gentleman then by the name of Jay Pritzker, who at the time was the patriarch of the Pritzorg Pritzker organization. You know, again, sort of five, $15 billion family office at the time, but as I said, run by, by Jay. Tremendous experience and one which was, you know, eye opening. And I learned a lot from. But I knew and prior to that I had been in private equity, was a cottage industry then, really didn't even exist by name. So I knew what I wanted to do and I partnered up with somebody and we RA after business school and we raised our first fund here in New York. And it was a, quite frankly, high level, a very generalist fund. You know, we were happy to raise at the time. It was $175 million fund. And, you know, I always say, better be lucky than good. I, I actually went to visit a very high tech business down in Huntsville, Alabama, which is, by the way, a hotbed of technology based on, you know, the government spending a lot of obviously capital, Resto and Arsenal and otherwise to develop, you know, again, programs in Huntsville. And I was fortunate enough to look at a business through a contact that I had and kind of started to learn about, you know, the ecosystem which ultimately, you know, I'll get to relative to, you know, that specialization that you referenced relative to Veritas. But long story short, that was the, the initial investment we made in technology and government. That's kind of the nexus of where we live. And, you know, started to go from there. That was when the focus started. We moved away from being a generalist into a specialist. So the partner that I mentioned, fast Forwarding now to 2012, unfortunately passed away. And so he and I were key persons. And in the world of private equity, as you all know, when there is a key person event, you have to basically go start from square one and make sure your investors are happy with the way forward and they have the ability to effectively again shut down the fund, so to speak, by not contributing capital anymore. And I think this is what you're referencing. So again, in a very short amount of time, again, I had been front and center with our investors obviously over the years Got to know them very well and was fortunate in that 100% of our investor base wanted to continue to move forward. At that time we were investing still out of a very small fund, a $600 million fund, our third fund. So our AUM at the time was well, you know, less south of $2 billion. And you know, I continue to push at that point and you know, focus the business on areas that we had not been focused in underneath this overarching umbrella of the intersection of government and technology and moved into healthcare tech and education tech, ultimately infrastructure technology and lastly financial technology, fintech. And fast forward a little over 10 years since that point. We are now north of $50 billion of AUM. And most importantly, what I focus in on and obviously what the firm focuses on is we continue to deliver top tier returns across every one of our vehicles since, you know, since inception. So we are top again quartile, top desktop, again manager across all of our funds. You know, there's not that many firms in the world that can say that our gross returns are, you know, and gross and net returns are second to none. So you know, the thrust for us is always to maintain that focus, the discipline around that focus, to continue to learn to be entrepreneurial in our approach. But we took, you know, a very difficult time for me, both personally and professionally, you know, a very difficult time. And you know, I think the ability to adapt, the ability to, you know, overcome obstacles is obviously a key element of anyone's, you know, success. I don't care who you are or what you do. And we were fortunate to obviously get through a very difficult time and continue to move the firm, quite frankly, you know, to a different level over the next 10 plus years.
It sounds like it. Ramsey, I, you know, you mentioned focus there a few times in your comments. So let's, let's take a deeper dive into your focus and your niche. You mentioned a few of the asset classes you guys are, are, are laser focused on. So why, why those, why critical infrastructure? Why the technology side of it? Why government and the confluence of these areas like. Let's flesh that out a little bit more.
Sure. And a lot of people say exactly why you're crazy to focus in areas like this. I mean, just to define it, again, the ultimate focus is investing in very high tech businesses in these government influence and heavily regulated industries. So if you look at today for example, our portfolio in aggregate about $25 billion of revenue, call it 55, 60% of that revenue, is driven by sales and revenue to government entities, predominantly US Federal agencies, some state, local, some foreign governments, but predominantly US federal agencies. The other call it 40% is through is not direct to consumer but enterprise. So commercial enterprise revenue. And you know, the decision really quite frankly is twofold, one of which is it was personal. So just taking a step back even, you know, shortly, as I said, we started as a generalist firm until we, you know, kind of started to learn about the ecosystem. And the initial ecosystem that we really delved into was the defense world. And you know, my best friend, one of my best friends was actually on the first plane out of Boston that unfortunately went down and hit the World Trade center on 9 11. And you know, as I sat there and thought about what I was doing at the time and how hopefully I could make an impact in something positive, started to really focus in on more and more, not only defense, but importantly national and global security. And that is a very intricate market. It's a very complex market. It's a very high barrier to entry market. And you mentioned obviously with security clearances, but not only relative security clearance, it's also knowledge, it's also, you know, again spending the time and quite frankly years to learn those ecosystems is, they are very different than the ordinary, so to speak, commercial marketplace and how they procure goods and services and solutions. So you know, so when you think about the areas we're focused in on defense, national security, healthcare, education and fintech, these are all areas that impact our daily lives in the most meaningful way. So the way that we've kind of chartered our journey is really how do we make an impact, a positive impact, through the use of technology in markets, in areas that are so very important to each and every one of us, we are involved, and we can go through some specific examples, but we are involved in protecting citizens across the globe through companies we own. In the defense and national security security world, you know, in healthcare we are focused on through the use of technology and artificial intelligence and analytics data and analytics. We are focused on not only the reduction of the cost of care, where we rank abysmally low in the United States, 50% more than the next OECD country. But importantly, how do we improve the quality of care where we rank even lower, you know, 28th to 30, 35th across so many different metrics, longevity or again infant mortality or otherwise, relative to quality of care. So how can you use technology to improve that? And then personalization of education, again, using technology K through 12 to improve the education and personalize the education so you can actually customize it to that Specific student and their requirements versus broad based education. So that's how we kind of said this is where we want to play because it means so much to all of us. And we think that technology could be an enabler to achieving the overarching objectives that we have in each and every one of those areas. And that led us to.
I'm curious, Ramsey, if I could maybe just jump in here. Let's take one of those areas. Healthcare. Why? You know, for those in the audience, I think we, I think people are. There's a spectrum of awareness around healthcare in our country and what it costs and our impact. And you just laid out some statistics that are, that if you'd never heard them before can be alarming. What do you think are the top two or three explanatory factors around like why the US healthcare system is the way it is? Why does it cost so much for us to do everything? And why is the, why are the general like metrics that we follow lower than some of our peers around the world who have similar economies?
So you know, he's going to have to answer that in about 15 hours, but we're not going have that long. So make it as quickly as you can, Ramsey. But that's a broad topic.
I'll try to make it very quick. Yeah, very high level. I mean one for, for one, you know, the goal posts are such that, you know, it's really fee for service driven, meaning I don't care what kind of quality care you get, you just get to pay a fixed fee for doing it. Right. So if you actually embedded in sort of quality metrics relative to that, you know, service you were getting and got paid for performance, so to speak, you would have a different outlook relative to the quality and how you achieve that quality. So I think there's some, some clearly high level things that. And we are migrating away from kind.
Of fee based services, ACOs and whatnot.
Yep. Yeah. Into areas which measure quality and that's ultimately going to be the driver. You know, I think that mindset change and the incentives relative to that mindset change and the payments applicable to that are going to drive, you know, again a shift. Ultimately it'll take a long time to happen. But you know, you think about that bureaucracy and you know, more morass, so to speak. You know, healthcare is what, approaching 20% of our GDP within healthcare, just healthcare alone. And you guys, obviously everybody reads about Doge and what they're trying to do, but within healthcare alone There is about 1.2 trillion McKinsey and others have estimated a fraud, waste and abuse in that system. A trillion dollars, over a trillion dollars of just fraud, waste and abuse. And we have had and continue having, you know, companies that focus in on this and try to whittle that down, but it's still a gigantic number. So there's a lot of different ways that you can come at this problem. And technology, again, is a key enabler to drive, you know, for example, that fraud, waste and abuse down and improves that quality of care. But fundamental, I mean, just to answer your question very, you know, quickly, I think it has to be a mind shift change which we are undergoing, and then there's a payment for, you know, obviously performance element that comes into play. But first and foremost, we should just clean up our house. We have so much within our, you know, again, our control that is just gone for, you know, and, and without any value created, you know, by this $1.2 trillion that, you know, we should focus in on cleaning up what we have, which will lend itself to, not only reduce expenditure, but quite frankly, improve quality in and of itself.
That feels like a very easy segue into the next part around, especially with Doge and everything. So, Ramsey, I'm curious there. You know, I can't think of many people who are closer to what's happening in Washington from the standpoint of the private sector in the business world than you are. Right. Given 50 to 60% of all the revenue that your portfolio companies come from, as you just mentioned, are, are coming from the government. So, like, you know, what's happening right now in Washington, like, what's changing, what's hearsay, what's, what's real, what's not real. You know, I think, I think you have a unique opportunity here to, to, to set the record right. At least as far as you understand it.
Yeah, that's the key qualifier. As far as I understand. Yeah. Yeah.
And that's why you're here, Ramsey, because.
You understand it, right? I hope so. I, I've spent a good amount of time, you know, in Washington. I've spent a good amount of time with the President and the current, you know, the administration, but a lot of time with the president himself, you know, talking through a lot about what we, what we're talking about and what you continue to hear about. Look, like I said, there's a lot of inefficiency, you know, so when you talk about Dogens, there's a lot that needs to be done, not only from a cost standpoint, which is critically important in terms of reducing that waste we all know 36 trillion of debt and growing and how do we, that's not sustainable. And we've got to attack it. You attack it through cuts and spend. But I will tell you this, and I've been very direct with the President and otherwise, look, going through that discretionary budget and finding kind of dollars to save there through personnel reduction, that's just a, not even a drop in the bucket. You know, again, that's not even a penny on the dollar. That's just very small numbers. You know, ultimately, if you're going to reduce what has to be reduced, you know, because it's like I said, not sustainable. We all agree on that. You're going to have to look at, you know, entitlement spending. You're going to have to look at that non discretionary, the, again, the discretionary, which, you know, I, I think I said non discretion, but the discretionary is where we're, we're looking at right now. But you're gonna have to look at the non discretionary, the entitlement spend. For example, you know, you're going to have to look at Social Security. You're going to have to look at Social Security. There's some political hot buttons you're going to have to look at and make hard decisions about if you're ever going to make a significant dent in that debt. But what I will tell you is this is long overdue. We have been trying to push, for example, a lot of our customers and they have been wanting to do it too, but within the bureaucracy of Washington D.C. wanting to do something and do something is very difficult. Difficult in many cases. But to push, you know, a lot of our, you know, programs and, and you where we're providing this intricate and complex solutions to our customers. In many cases, again one of the intelligence agencies or DoD or subdirectorates underneath that, we are trying to push them more to kind of these fixed price, what's called time and material fixed price contracting mechanisms where, you know, instead of these cost plus mechanisms whereby you have to make sure, you know, whoever's providing that solution knows what they're doing and if they do it well, they get compensated for it. If they don't, they, they obviously don't get compensated for that. And the cost plus world that is really, that dominates government and how they procure, you are going to get paid a percentage above your cost. So there's no risk, you know, so.
It'S a lot like the healthcare conversation. You just talked about the mindset fee for service versus versus you Know, value based care.
Well, I mean, it goes back to the point we have a saying as a firm, we literally repeat all the time that we're freakish about alignment. You want people to be aligned to positive outcomes, whether it be health care or defense spending, et cetera. Which is why companies that are new to the scene, like an anduril or shield or a chaos, et cetera, they're absolutely changing the way that, that manufacturing is done, of defense technology. So, you know, when you think about what is happening, let's try to make it very real for the audience. How is it impacting investment decisions? Does it make you go faster? Does it make you go slower? Does it make you go. I don't know what to do. Talk through how you go about with this much change in this shorter period of time, what do you do about it?
Yeah, great question. You qualified it very well. I think, you know, quite frankly, all the above. I mean, you know, the good news about having done this now for 25 years is we've seen a lot, you know, there is some, you know, stuff that's happening now. And quite frankly, the uncertainty element is the most problematic, you know, as you've heard, with not only, you know, again, folks in that, quote, government ecosystem, but in the technology world, you know, that uncertainty lends itself to indecision, which lends itself to pushing things to the right, which then lends itself to, you know, a slowdown, broadly speaking, in the economy, et cetera, et cetera. And that's what I worry most about. But, you know, relative to how we approach things, you know, the good news about where we sit is we, you know, our businesses, like I said, are not tied to consumer, which is obviously a big part of the US economy, 2/3 of the US economy. We're directly tied to government and enterprise. And, you know, the thrust for us is always about driving unique solutions to that customer. So best value, so to speak, better solution, lower cost, you know, so our approach, you know, in the world we live in is, you know, continues to be the same. We've lived through, you know, wars, obviously, we've lived through the Great Recession, we've lived through a pandemic. We've lived through government shutdowns, we've lived through sequestrations. You know, you, you name it, you know, we've seen it. And this is, I don't think too far too much different than, you know, some of those other, you know, events that I've highlighted in that context of uncertainty. But what I would say is, broadly speaking, in private Equity deal flow has been low relative to historical norms, you know, exits in terms of, you know, sales and distributions. The limited partners has not been what it has historically as well. And that is because of the element of uncertainty that, you know, kind of exists. But I will say from our standpoint, our pipeline is as strong as ever. And you know, I think relative to all that I highlighted, we continue to be busy on all fronts in terms of not only again, acquisitions and new investment opportunities, but also in terms of realizations. But what I would say, look, we're close and we have been close. I mean, part of our ethos is what we call tip of the spear. We define ourselves by the intersection of technology and government. It's incumbent on me and others at the firm to remain close to folks in government, folks in and around that ecosystem. We've done this for cross administrations and continue to do with this administration to understand where things are headed, so to speak. But when you predicate your entire kind of raison d' etre behind understanding to invest in mission critical, and that's such an important part, defining what mission critical is, is really paramount because if you really do that right, and then you apply your playbook to that investment and grow the business and move them into new areas, then you're going to be fine no matter what. But that definition of mission critical, the must have versus the nice to have, is so important. And that is somewhat really kind of the shield against any sort of volatility that the market experiences. Because we've seen this historically. If you buy the businesses that not only apply to your playbook, but have that mission critical status in defense or health care or education kind of, that must have. That's, that's really what will ultimately, let's.
Let'S dig in there a little bit because I think we can get very practical for the audience. So what you, you know, my, my phrase would be that, you know, you're talking about what moat does this particular business have around it? How mission critical is it? Kind of the same thing. How do you go about deciding which moats are big enough, which moats are not? You know, I don't know if there's any examples that you could give that you're comfortable giving. But I mean, businesses that you go like, this is a big moat. This is what we look for as opposed to others in the industry that just maybe they're good, but they're just not good enough.
Yeah, I mean, a lot of it is. Again, this is somewhat, a little bit of an art as well. As a science, but more of an art than a science. But yeah, that's that critical assessment in terms of the moat and the ability. That barrier, that barrier and defect, definition of that barrier is such an important element of, you know, where you can really, at the end of the day, determine what your baseline business should look like, no matter what, agnostic to whatever the macroeconomic backdrop is during your ownership period. And, you know, we, you know, look, we've learned so much. We don't create and manufacture widgets. We develop intellectual property. That's what we do here. And we've actually productized that ip. We have our own internal portfolio optimization team that effectively productizes all this IP that we've now accumulated over 25 years across all these different types of business. Thousands and thousands of different investment opportunities across all the target industries. So we, and, you know, we've been applying, you know, by the way, just. And I'm sure you may bring it up, but I'll bring it up first, you know, this application of artificial intelligence. Well, guess what? You know, the good news about the government, the government is, quite frankly, and I, again, tip of the spear in another respect, is at the forefront of technology. We've been investing in companies within that government ecosystem that have been involved with AI for decades. For example, taking unstructured data exabytes and petabytes of unstructured data, and in real time, providing analytics to the President of the United States and his cabinet. And we've been doing this for a portfolio company, and they've been doing it for over 40 years. So we also utilize that internally to help us gauge the moats, so to speak, as you just qualified and described. And that's an important part because, you know, those, you know, again, those things change over the time, over time. But understanding whether critical variables, I'm not going to obviously get into the details of which those are, are critical for us to make those decisions, have conviction around those decisions, and then invest around that business to help drive it into new adjacencies. You know, again, you can get to the IRRs that we've achieved. If you buy a company, hold it, and then, you know, five, five and a half years later, sell that business without really kind of reorienting and transforming that company. Our real thrust, our kind of playbook, is driven by investment. We're very different in the private equity world in the context of, you know, we're not a. It's not focused on cost cuts. It's most actually focused on increasing expenditures in two key areas, two fundamental Key areas, one of which is obviously research and development, the other is sales and marketing. Business development now, sales and marketing, not only to entrench and further entrench these companies in their core markets, but importantly to move them into adjacencies that we ourselves at veritas identify as areas of opportunity, markets of opportunity that we want to take their capabilities and qualifications from that core into these adjacencies. So I think, like I said, just having done this now for 25 years and having remained a specialist, one of the things that I owe have seen in private equity is, you know, as you grow and we've grown again, less than 2 billion of AUM to north of 50 billion. Now, sometimes people stray from what they do best to get to that, you know, additional growth. We've never done that. We won't do that. And that's really kind of the, the real secret sauce behind the success. Because what that enables you to do is to continue to learn, to continue to build on that ip, to continue to learn from your mistakes and apply those lessons to future situations. If you're moving into all these different areas that you don't have that experience in, that's when you see returns decline. And you know, again, that's when you see, I think, more of the problems occur. You know, again, broadly speaking, it's quite.
Amazing that we're going from talking about when you were a child and literally taking your test and mailing them in from across the world to now what we're talking about with artificial intelligence and actually the, the speed there. But I think what the audience is going to be surprised by, and just because I've had some familiarity with it and we as a firm have, you know, you just made a comment that most people went like, what? Did he really just say that? And that is that the government has historically been at the forefront of technology. Well, most people think of government inefficiency, talk about what they've been, why they've been so early in a lot of these areas like artificial intelligence. And then ultimately, how can we help them use it better? How can your companies use it, help them use it better to be more productive.
Now, it's a great question and yeah, you wouldn't think that, but you know, you go through it, if you look at the, the iPhone, you know, again, a lot of what you use on your iPhone has been developed in collaboration with the government. And you know, you think about not only collaboration, but in funding. Siri was actually an acquisition that Apple made early on. It was a government Funded business that developed that capability.
Wow. And most people never knew that about Siri.
Yeah, exactly. That's what I was saying. Actually the initial algorithm for Google was developed in collaboration with the government. You obviously think about Tesla, you think about Elon Musk and the ecosystem he's involved with, SpaceX, a lot of those capabilities, technologies developed through what's called these customer funded research and development programs, CR&D. And what happens is the government will invest, not only invest money, but collaborate with companies and then the IP actually can be utilized and leveraged by that company unencumbered. Typically in most cases, in some certain cases of, you know, where national security is involved, that is not the case. But again, broadly speaking, most cases it is. And so therefore, when going back, you know, every year the US Federal government spends hundreds of billions of dollars investing across the glob globe with companies through these customer funded research and development programs. So that's kind of the genesis and again goes back to everything we do. The Internet, obviously not necessarily Al Gore, but it was developed through DARPA funding. DARPA is the Defense Research Project Agency for the again, Department of Defense. IARPA is the intelligence agency, research funding agency. So that apparatus has been responsible for a lot of what we see in terms of technology. Now the government on its own would not be able to obviously extrapolate that and exploit that technology to the benefit of society without the commercial enterprise. So that's why it's important that companies that are the beneficiaries of these customer funded research and development programs then take it and leverage that technology, that capability, we call it that qual, that qualification and drive it out whether to the enterprise market or the consumer market. So you know, it is something that isn't as well known. But having now been involved in this area for so long, that's really big reason why we decided to stay focused in this area. The first company I mentioned, small company that became the cornerstone to a public company we took public called Integrated Defense Technologies. That first capability, I learned about this again it was 1998, it was a hybrid electric technology and developed by the Army. And we said, well wait a second, it's a very unique and obviously very unique at the time, 1998, how do we leverage this and not only move it further into the Defense Department, but importantly into the commercial market. We were able to do it. And this was a customer funded R and D program that the company, this little company had at the time it was less than 50 million of revenue. So that.
Ramsey, I have a question that Kind of ties, maybe two things we've talked about here around what's happening with Doge efficiency. You mentioned hundreds of billions of dollars a year are spent on these customer funded research programs. So what are you hearing right now? Like, is that. Because I think one of the tensions that investors feel who are sitting and thinking about what's happening in the world is okay, we know that there's a lot of waste, we know that there's a lot of excess spending from the government, but we also know that there's baby in that bathwater, so to speak. So what are you hearing is going on with these important programs, not just out of darpa, but also even something out of like USAID that's been totally shut down. I mean 100% of what they were doing wasn't all bad. Right. You know, there's a lot of waste in there. But so like not on one specific of these agencies, but just broadly speaking, what are you hearing as far as like the solid programs that are driving innovation, driving commercial technology, driving jobs, like, is there still support for those things or is it a complete reevaluation?
You know, I think, you know, it's a, it's a complicated question, good question and one we've grappled with as well. But I will say, you know, I think, look, there's like, like you said and I've talked about there, there's clearly areas of opportunity relative to waste and we should be tackling that. We should be aggressive about that. And I think, you know, even identifying within the ecosystem, the defense ecosystem, you know, why are these programs existing? What's the raison d' or? Why should they exist? You know, what are you, what value are you providing? Those questions should always be asked. Yeah, you know, but, but by and large I'm, you know, from where we sit and just, you know, focused on these, you know, these areas that, that I've talked about, there is so much good that comes from, you know, again, you know, these, these types of programs and you know, whether it's defense or health care, education or otherwise. So what, what, what we see is clearly there's a lot of, you know, there's a lot of, you know, deep reviews and a lot of again, hesitancy on new procurements potentially in certain areas. But like again, going through the must versus the nice to have discussion at a high level, that's really what delineates, you know, the value ultimately. And it's not very hard to figure out, quite frankly, once you delve into, you know, these programs, what are the must haves versus the nice to have. There's clearly things on the nice to have side. And you know, look, this has been definitionally the case for the last, you know, many decades. I mean, even think about since we entered into a never ending war in Iraq and Afghanistan, we have what's called supplemental spending, you know, that ballooned into almost $180 billion of expenditure a year. A year actually in some counts north of $200 billion. So on an annual basis. So look, there's the element of what's nice to have, but there's also an element of, at the end of the day, the world's not getting any safer. And I'm talking now, I'm back on the DOD side, the defense side and intelligence side. The complexities of the world, you know, are greater now than they've ever been. There's a fourth domain of warfare, space that is, you know, unchartered in certain respects and where we as a nation, the United States, don't stand as strongly as we should because in some part, you know, China, for example, has stolen all of our IP in that realm over the last two decades. And you know, so there's elements of areas where, yes, we're quote, wasting, but there's elements where we need to spend more and be more aggressive relative to critical areas that will not only protect our national and global security, but quite frankly, our economic security in the long term.
That's an interesting point. I mentioned at the top of the session here that, you know, I have family that's active duty military. My brother is actually a fighter pilot. He flies F6 F16s. And, and you know, my brother in law is a lieutenant colonel in, in the engineers. Dad's an infantry officer, retired. And so, you know, the family Thanksgiving conversations, everybody catches up on what's going on in their jobs and it's really, you know, what global national security issue are we facing now? And I've talked to my brother a lot about this, the fighter pilot. And I asked him, you know, okay, well we hear about, you know, the threat that China is we. And specifically as you reference it, Ramsey. And I said, well, surely like our technology is still better than theirs. And he, and I won't forget it. It was several years ago, he looked at me and he says no, like flat out no. And I was like, well, how can that be? We spend so much money on it. And he's like, they have things that we can't even do and we have things that they can do. And it hits home Differently when you think about loved ones going and putting themselves at risk. I'm curious, Ramsey, where do you see the greatest opportunities for capital to go into, to not just make a difference on the battlefield, wherever that might be, but also to generate a good return for those dollars that go in?
Yeah, well, first off, thank them for their service. And you know, we do a lot to try. We talk about businesses, but it's all at the end of day, people. And we do a lot in that realm to trying to bring as many of our military folks post service into, you know, the companies that we own, including here at Veritas. But I may have them, I may.
Have them call you.
Yeah, no, please do. I'm always happy to. That's something I always love to do. Try to do what I can.
He's got a, he's got a very cool job. He's the commanding officer of the weapons test squadron for F16s right now.
Oh, wow.
He used to blow stuff up.
He does. Yeah, he does.
That is an interesting job. And by the way, you know, I don't think, I don't take advantage of where we sit and what we do. I, I had been able to do things that quite frankly, you know, not a lot of people have, you know, taking off, landing on, on an aircraft carrier in the middle of the night, you know, actually going into a war torn. Afghanistan, Kabul, Afghanistan, because one of our intelligence community customers wanted to discuss certain, certain things that were going on. This was right during the war in Afghanistan. So I feel I've been, you know, fortunate enough to, to be able to do some interesting things based on where we sit and what we do.
I pushed him to take me up in one of his planes and we haven't gotten there yet. I'm just, I'm just not asking, I'm not asking the right way yet.
You might have to step up your Thanksgiving dinner.
I probably do. I probably do. Anyway, sorry, you were saying, Ramsey, about where, where, where, where are the interesting opportunities right now?
Yeah, I mean, I think, look, at the end of the day, our focus, that's where I'm going to lend it lead to, is, you know, in technology. And again, technology is such a change agent in many respects, a positive one. And you know, obviously there's risk relative to it as well. But you know, we've been thinking about and talking about, I talked about AI, data and Natalie, the power of data. Data is more powerful than any other natural resource that we have. And now you're seeing that come to fore and obviously it's becoming more commercialized and more accessible to get everybody through whatever you want to chatgpt or otherwise. But Quantum, there's a lot of different areas within the overarching technology market that we're focused in on, but it's not only about the capability itself in terms of technology. It's kind of the end use in the market. And that's where we spent a lot of time too, learning about the ecosystems that could benefit from again, high tech capabilities and initiatives such as Quantum or AI or machine learning or whatever the case may be.
Well, let's talk about that for a second because Tony and I had a fascinating conversation with Robert Smith from Vista and we talked about how agentic, you know, AI is really, really, really what the next wave is. And of course I had to, you know, ask him to clarify for the audience, would you explain what agentic means, which is just using agents effectively that are able to accomplish what people would normally do. So how much are you seeing that right now in the world of defense, healthcare, education, et cetera? Is that in being implemented yet or is that still yet to come?
Yeah, no, it's been, it's been in implemented and for a while, it's been in existence for a while. I think, you know, it's, it's an IT process. You know, as, you know, these agents become smarter as the more they do and the more they're asked to do and the more experience they have, so to speak. And, and that's what you see relative to, I think more so when I talked about, you know, again, education, personalization of education, you see the agents essentially becoming personalized teachers and understanding what the weaknesses of a student are based on interaction on, on tests and otherwise. And we've seen that through our portfolio companies in the edtech space. And that's going to be something that becomes more and more, you know, again apparent and teachers will actually, and again, it's a cultural shift. It's a seismic culture cultural shift. So that's really the inhibitor to this, you know, even taking hold faster than it, than it is. But across every one of those areas that you highlighted, defense, healthcare and education, you know, fintech, you know, accessibility to banking and rural communities, I mean, you're gonna, you, the agent element is such an important part of it, but it only gets better as time progresses and more of, you know, the capabilities are shared with, so to speak, the agent. And the understanding therefore becomes one where, you know, it's more of a predictive kind of enabler than it is even a reactive One understanding what those needs are before they become actual needs and driving, you know, opportunities there and, but we, again, because of the proximity and I don't want to, you know, this is, shouldn't be overstated, but we have seen this for a long time within that government ecosystem and like because of that tip of the spear that I highlighted. So it's not something new to us from an enterprise or a government standpoint, but now it's just becoming more true to form in the, the commercial marketplace.
I'm going to ask you a question, and I'll ask for your forgiveness in advance, Ramsey, but I'm going to ask you a completely unfair question because we always love all of our children, so to speak. But in the world of fintech, health tech, defense tech, if you could only do one of those and you had to pick, which one would you choose? I told you it was unfair.
Do I have to give an answer?
I'd really prefer it if you did. It would be better for the, for the audience to hear it. But it's, I mean, where's the best risk reward? Let me, let me make it easier for you there.
Okay. Risk reward is different than personal liking. So I'll answer both, I guess so. Risk reward. I think, you know, we're still in very early innings for, you know, cross healthcare and education. I mean, quite frankly, the use of technology in healthcare and education lags, you know, many, many, many other industries. And unfortunately, you know, that that's the case because it hits us very hard as a result of it. So from a risk return standpoint, I think, and because of the fragmentation of those markets, I think clearly over the Next, call it 10 years, you're going to see a ton of opportunity there that where you can actually create, you know, a true upside, you know, kind of scenario relative to returns if you, you know, obviously pick the must haves, like I mentioned, and then do with those business where you can. So I would point to them. But from a personal standpoint, that national security realm is something that I've enjoyed. You know, I enjoy going into what we call, you know, secret compartmentalized facility, a skiff, skiff, and hearing about things that are, you know, again, so far, should we say, not in the realm of mainstream that, you know, just, it just piques my, you know, intellectual curiosity.
How do you protect your mind? How do you protect your mindset and your, your, your, your view of the world and not become so jaded or dark? I mean, because I'm sure you've heard some very troubling things, right? I mean, I, I, I struggle coming home from work, and then I walk inside my house and I've got these four little kids and, you know, and I'm, and I'm not dealing with world issues. I mean, how do you do it? And, and, and go back and forth between these worlds? It feels like that would be, yeah, very. Maybe you have a great therapist on speed dial.
No, you know what? Maybe my, yeah, definitely my family, my dog, for sure. But I would say this, you know, look, and it's funny you say that because I've come back from meetings in Washington at a skiff, you know, and, and people here look at my face and they're like, oh, boy. They're like, oh, this is not a great, that was not a great one. So look, at the end of the day, you got to be able to compartmentalize as you all do, and you got to be able to, you know, continue to, you know, just push and wake up the next day and say, okay, this is what I need to do to move forward. But it is, it's, sometimes it is challenging because you hear, hear things and see things that are scary. I mean, I, I, again, 15 years ago, I had a skiff session whereby I left and I came here. I couldn't talk about what I saw, but, you know, I could at a high level, talk about, you know, it was China and I was seeing things back in 0809 that were very alarming. And, you know, obviously a lot of that's played true to form in terms of where, where we are today. But, yeah, it is, it is a challenge because there are certain things that you just don't expect to hear or see. But it's all about, you know, again, that balance and having that foundation, like you said, to come home to that, you know, you know, you know, where the priorities are and you focus in on that as well. So.
Well, one of the most common questions that, that, that we get. I love to hear your thoughts, is that, you know, five years ago, seven years ago, Robert Smith, actually, he apologized. He said, everybody, I told for your children to go study how to write code. I'm sorry, that was a bad piece of advice. So where should, as you guide your, you know, your family and other people and recommend for their children, what should they be studying? How do they prepare for a world that is changing so fast?
You know what, And I, and I say this with the utmost humble, you know, humbly. It's very difficult, you know, to understand because quite frankly, I think the next Decade is one we're going to see change that we've never seen before. You know, we talk about industrial revolution, we talk about the Internet, we talk about things that, you know, have transformed society for good, for bad. We're going to see things the next five to ten years that are unprecedented in many respects. You know, a lot of good will come of it. I truly believe, you know, like I mentioned in health care, you're going to see a lot of progress relative to being able to, you know, improve that quality care through the identification of issues well before they become, you know, manifested as more major issues for somebody. So I think, you know, you're going to see a lot of positive, there's going to be a lot of obviously, you know, risk too as well. So, you know, clearly there's going to be industries that grow from here relative to AI, for example, and you know, what that portends. Engineering and however you want to call it different in different areas. Obviously Robert was an engineer, as an engineer, but the understanding of that science is something that I think clearly will be of value and how to quite frankly keep the guardrails relative to that science are going to be as much of value. But it is definitely uncharted territory in many respects. Clearly a lot of the work being done and by the way, we're not insulated by this. You know, we talk about this here at Veritas. A lot of the work, you know, some of the work that we're doing here, you know, two, three, four, five years from now will be done by these agents. And you know, we'll clearly lend itself to, you know, impact relative to the, the human side. So.
Well, I, I think on that human side, maybe a question is, you know, you, your firm has grown a lot. You, you, your, your team has grown a lot. You interact with lots of different types of people. What, what are the, what qualities or traits are you looking for for a leader within your organization? I mean, part of this is a cultural question of like, what are your, what are your culturable non negotiables and the, the traits that you want to elevate and you want to celebrate and then what are the things that you look for that are just a quick like, no, we, we, we don't do that here.
Very good question. And that's, you know, obviously the people side is always the toughest part. But what I would say our, our kind of core to our, our culture which drives, you know, again, who we look for and what we look for is really that entrepreneurial spirit, you know, My, you know, my father, as I said, you know, he ultimately came to the United States to build a business, to start a company. My brother is on his third startup as CEO and founder in the tech world. And, you know, my partner, you know, Hugh, who, again, I've been with since I was in graduate school at Chicago, he comes from a similar background where his father started this. So we try to look for that entrepreneurial Bentley within private equity. You don't typically see that, but that's really kind of somebody who can leverage this platform and effectively be the CEO of his or her business within, you know, the Veritas umbrella. And that's really kind of a characteristic that it's hard to really gauge as much until that person is within the confines of the firm.
Well, that's the logical bolt on there, Ramsey, is that it's so hard to figure that out before you hire them. And obviously, it's really painful for everybody involved to remove them from the bus, so to speak. But what do you do to try to figure that out? What are some of the signs or the testing or the other ways that you go about saying, okay, is this person going to have that entrepreneurial spirit when they actually get here and you can feel confident in that hire?
Yeah, no, that's a great question. And, you know, look, we have also kind of a bill from within mindset, too. So, I mean, you know, we love. And we've done this many a time where, you know, an associate who has worked here ultimately becomes a partner. And that really, you know, kind of where you see them grow and they see how we operate, they see the entrepreneurial, you know, again, Ben, so to speak, right in front of them. And, you know, some people are comfortable with that, some people are not. But the identification really is driven by what you'd expect. You know, when. When you're bringing in someone to the firm, whatever level, from the most junior to the most senior, it's, you know, their experience in the past, how they. And we spent a lot of time, you know, with people outside of the interview process, so to speak.
I can only imagine the background checks you do.
Yeah, you're considering the background checks that are done on me. Yeah. No, trust me, we. We have a good apparatus in that regard. I believe it. And we, we, you know, at the end of the day, like I said, on the investment side, some of it's an art and understanding how that person will react. But in social settings, it's is an important element to it. But, you know, do testing as well as. As you would imagine analytics, but you can't always get it all right. But you know, and we brought as, as I said, people in, senior people in from the outside, but we again developed a lot of people who have become partners here at the firm from the earliest days in terms, actually the, the two co heads of our flagship fund, Dan and Jamie, both were associates here and now they're obviously not only partners but you know, running the flagship fund here at Veritas. So you know, I think, I think that's really, you know, something that you develop and hone over time. You learn from your mistakes as much as you do in your investment side. You do it on the personnel side. We're still going to make mistakes, but you, you learn from those, hopefully minimize those and, and you know, get, we've been fortunate where we've gotten it right much more than we've gotten it wrong.
It's, it's definitely a learning process and it's a constant learning process and it never stops because we're always trying to get better. So as of come to the end here, I want to ask a question that really is forward looking. So you know, let's take a look inside of your crystal ball. Imagine that we're sitting here having this conversation five years from now. How will the world have changed in the way in which you're investing and the types of companies you're investing? Where do you see us five years from now?
I do see more of a chasm between again the leaders and the laggards. And I think that goes to not only the companies that we are looking at and investing in the capabilities because the technology element's going to really drive a bigger gap between, as I said, the leaders and the laggards. But I see that within private equity, you know, what I, what I, I had hoped for had not happened, but I think will happen over the next five years is there's going to be more of a discerning kind of vote by our customer, the investors, the limited partners as to where capital will be deployed. A bigger, you know, kind of, I think over the next five years in private equity, a bigger, you know, again, percentage of that capital will come from, you know, again, the retail investor, the high net worth investor. And I think there'll be much more of a discerning view of, you know, who are those performers who have a differentiation in the marketplace, who have a moat, who have a barrier to entry, have, you know, again, a long history where you can actually assess and understand, you know, what that differentiation is. And how does that play out in terms of what's most important to an investor? The returns. So I think you're going to see a lot of, you know, these third tier, four tier firms no longer exist. And if they do exist in a much smaller fashion. And so that's good. I mean, that, that is a healthy shakeout that the private equity world needs. I mean, there's over 8,000 firms now. Wow. And we all know how much dry powder is out there and we all know how, you know, what a top tier, top decile return looks like relative to a third quartile return. And that shakeout should have happened, but I think over the next five years it'll happen in a, I think a much more, you know, faster way.
I'll, I'll tell you, Ramsey, now, you know, we own stakes in over 95 different firms of all different types, sizes and strategies. And it is definitely beginning to happen to where we see firms that have had competitors kind of nipping at their heels that all of a sudden they're just being starved of capital because the LPs are becoming a little bit more discerning. You know, when you start having scarcity or you have the denominator effect or whatever terminology one wants to use, you have to be very, very careful about what you do with the limited amount of capital that's available. And so they're being more discerning. And I agree. I think that's going to, to escalate from here. Well, Ramsey, this has been a tremendous amount of fun and we really, really appreciate your time to share your thoughts with us and to be very transparent about what is going on in the world at large and specifically in the world of Veritas. Mark Wade, thank you so much for being with us.
Thank you very much. Appreciate the time.
So, I mean, Mark Ramsey is a fascinating individual, not only because of his childhood and living all over the world. And, you know, he told us some other stories in the book. For those of you that have not read the book. You know, Ramsey's interview, like all of them, is really, really in depth and goes into things that we don't have time for in this setting. So we encourage you to do that. But what were some of your key takeaways from the conversation with Ramsey?
Yeah, he, he is a fascinating individual and I bet you there's a lot more there to pull back some of the, some of the things that he has seen and heard well in advance of them happening and, and his awareness of what's happening in the world. I was Lot to unpack there. But I thought his comment around having a mindset shift. He said it in the context of what's going on in health care and fee for service versus accountable care organizations and value based care. But really that if you take that concept and you apply it into all these areas that they're, that they're investing in and that we talked about is that the, the world is going in a very new direction. Right. It's, it's, it's going in a very new direction that will require mindset shifts by individuals who want to take advantage of those changes. I mean these changes are happening, they ain't going the other direction. And anytime change happens, it presents challenges, but also opportunities.
Right.
And, and it feels like that's someone who understands that if you think being where you are and, and staying where you are is going to keep lead to the same types of results, that's not going to happen.
Well, it's so hard about both healthcare and education is they just, you have to have a willingness to change by such a massive number of people to look at the world in a different perspective.
Yeah.
I mean people will stay the same until the pain shift.
Carecraft, carrier, turn it around, it's an.
Aircraft carrier in a bathtub is what we're trying to do here. But I mean people will stay the same until the pain of making the change is less than the pain of staying the same. And unfortunately we're just seeing such bad results in healthcare in particular. I think education in some areas is getting better, but in other areas is not. But for us not to use technology that all of us can use to plan our vacations, our meals in the evening and not even use that in schools and in hospitals is shocking and amazing. But I don't know what's going to really cause that change. But hopefully innovation will drive the change because those who don't adopt it are just simply going to get left behind.
It's a mindset shift. I also thought his comment, I love it when like you always, you hear this consistently from people like him who have been very successful and whatever they do is that there's a sense of he said, he said, what do we do here? Right. Like it was very. The answer was productize intellectual property. Take something, intellectual property is something that, that is not easily copied, it is not easily replaced and productize it. Right. Figure out how to take that. And of course, he gave in the Context of the 25 Years of History that Veritas has of operating these various markets and these market Segments and with these different types of agencies. And so that that creates a proprietary intellectual property set that then you, you can then go monetize it in various different ways. And that's when you talk about moats and you were talking about moats in the conversation. That's a real moat. When you have that information and then you can use it and apply it in various ways. That's how you generate different types of returns.
Yeah, it's one of the reasons why we have as an organization have been so focused for almost 25 years ourselves on, you know, domain experts, people that are sector specialists, they do one thing or two things and they can just know more about that area than others. It doesn't mean that generalist firms cannot be successful. There's a lot of really good ones out there, but the ones that really just have a niche, they take advantage of their informational advantage in order to be able to generate returns. It's really, really fun to watch when that happens. And Veritas of course is a great example of that.
What did you think his comment around like the future and unprecedented change. Right.
It's terrifying. I mean I've got a three year old grandson and a six month old granddaughter and right now I literally have no idea what to tell them that they should study other than just be very well rounded, very grounded in understanding things and you know, to quote Robert Smith again, just learn how to figure stuff out.
I feel like that's a, that's, that's like pushing people back towards like classical education and like, and like just like logic and rhetoric and.
But it really is, it's all about, it's literally all about being able to solve problems because of the fact that we don't know what the world is going to be like in five years, 10 years or even five months for that matter. And so for a child or a young adult to be able to just know, I don't know what I'm going to have to figure out, but whatever it is, I'm going to figure it out and to have the stick to itiveness to do that. And the hardest part, folks you know that are listening, I got to tell you, the hardest thing is to let the children fail enough to have to figure it out on their own. And I see it over and over and over again. I made a lot of mistakes as a parent to our 29 year old son, but just making them be independent enough to have the blessing that is that they have to figure it out themselves.
We don't learn anything from success. We really don't. I mean, you're a very special person if you can look at your own successes and say, I'm going to learn something from that. It's. It's the. It's the perceived failures. And I say perceived because inside every failure. I mean, think about myself personally. Like, I have a ton of failures, quote, unquote, in my life of things that didn't go the way that I wanted them to. And then in those moments, you do a little bit of soul searching and you think hard about, okay, why did this happen and how do I make it not happen again? That's when progress.
Well, that's what. Yeah.
And I'll quote Tony, in this situation that. Look at all those situations as a gift. Life is either happening to. Quote Tony. Life is either happening to us or for us. And if we take a situation that we perceive as a failure or a tough spot and we grow from that, then ultimately that's a gift because of the fact that we can use that later to be even more successful in the future in whatever life throws at us, because we know that we're going to get curve balls and we know that things are going to be thrown at us no matter what we're doing for our career or in our families, et cetera. Well, Mark, obviously this was a tremendous amount of fun. And, you know, listeners, we really, really appreciate you being with us. We look forward to seeing you next time.
More from Rob





Tony Robbins Helps Her Use the Power of Her Own Mind to Manifest A Better Life