Vinod Khosla on AI’s High Costs, Circular Financing, and Massive Energy Needs | Oct 22, 2025
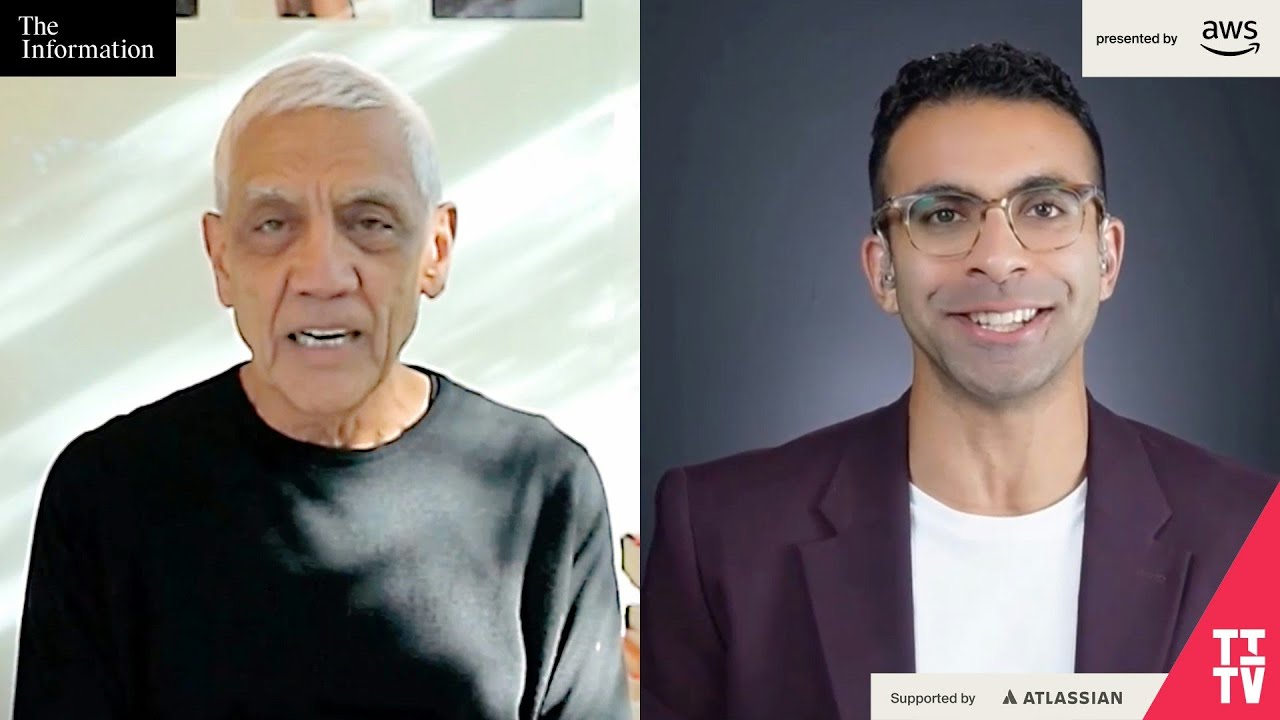
Vinod Khosla breaks down AI economics: slim margins now, massive power needs ahead, and circular financing deals between NVIDIA, Oracle, and OpenAI. Most AI startups will lose money. The episode also covers TikTok Shop's new ad tool, AI solving returns in e-commerce, and an AI-powered online college that personalizes learning for each student.
Chapters
Welcome everyone to The Informations, TITV. My name is Akash Pasricha. It is Wednesday, October 22nd. We have got a great show planned for you today. We have got Vinod Khosla coming on the show for a discussion about what he thinks of all of these circular financing deals in AI. And who is best positioned to challenge NVIDIA. We're then gonna talk about our new story out today about what creators think of TikTok and TikTok Shop's new advertising strategy. Plus, we've got a great opinion piece up on the site today about how AI can improve the shopping experience. I'll be joined by the author Lee Haslett-Chen, founder and CEO of Howl. And finally, we'll end with a conversation with the leaders of Campus, a fully online for-profit college backed by the likes of Sam Altman and Shaquille O'Neal. We've got a busy show to get to, so let's get let's get right on into this. Vinod Khosla is one of the best-known venture capitalists in Silicon Valley. His firm, Khosla Ventures, is of course an early investor in OpenAI, but really it has become one of the broadest portfolios in venture capital, having backed fintech companies like Stripe, consumer companies like DoorDash, space companies like Varda, and several companies in the energy and biotech sectors. Last night, I sat down with Vinod to ask him about how he sees AI companies grappling with high costs and what he thinks of all these circular financing deals and also how we're going to satisfy all the power that AI is going to need. It was a great conversation and I'm excited to play it for you. Here is my interview with Vinod Khosla. Vinod, welcome to TITV. It's great to have you here.
Well, it's always exciting to be here.
So before we get started, I just wanna set the stage a little bit because our subscribers at The Information know your career very well. They will know that you don't consider yourself as much of a venture capitalist as you do a venture assistant. They will know that you believe that AI is going to replace 80% of jobs in the long run. And they will also know that you are a steadfast optimist. And one of the guiding mantras in your career has been that skeptics never did the impossible. And so with all that in mind, I want to zoom in on that third point. Because it feels like right now, even for people who are very bullish on AI, the technology, there is enough reason to be at least somewhat skeptical on AI, the business. And so where I wanna start the conversation is, Vinod, is there anything that you are skeptical about right now?
Well, to start with, I think if you're going to do something significant, you're gonna have to be an optimist. But not only just an optimist, a knowledgeable optimist. There's too many skeptics who live in the past and will extrapolate the past to invent the future. That's a bad thing to do. Inventing the future you want is the right way, and optimism is key to that. Having said that, I think the one thing I don't know, and there's things I can reasonably project and things I can be uncertain about. The thing I'm uncertain about is timing of various breakthroughs that we expect to see in the next 2 years, 5 years, 10 years. Almost certainly, it's easier to predict AI in 2035 and past probably 2030 than it is to predict it today. And what will happen next year.
Right.
So I'm not skeptical, but I'm less certain about the pace of development of certain capabilities that are essential to expanding use of AI.
Right. Well, let's talk about the current state of play. I want to get a little bit more granular here for a moment. One of the topics that has been talked about a lot in our coverage are the margins that a lot of these companies have on their AI products, whether it's cloud services or even AI application companies. And one of the challenges that we've highlighted in our coverage is that margins are slim right now and companies are finding ways to expand them. How do you think this goes in the long run?
I think the way to look at margins is when AI is a substantial business. Yes, it's large business, tens of billions of dollars, but it's not hundreds of billions of dollars. And so the question to ask is where will margins stabilize? Uh, I think some of it depends on R&D breakthroughs by the various companies and, uh, knowing who gets what breakthrough, which is, as I said, uncertain with respect to who and timing. Uh, I'm pretty optimistic about what OpenAI is doing. I do think if you provide value and you have differentiated models, uh, you will have good margins. Look, at the pace at which pricing is declining, both in supplying, uh, inferencing to the, uh, AI companies and the price at which things are sold. Uh, it's hard to predict the dynamics, but it will settle down. Good returns on capital, uh, invested. So I'd be surprised if we don't have healthy increasing margins well into the, into the early 2030s.
And, and, and which of the two levers do you think is more likely to get pulled on most? The idea that will costs go down for these chips that are very expensive right now? Or on the flip side, we had one of your founders on the show, Amjad Massad from Replit. He talked about this idea that the models might not get cheaper, but rather he's looking to actually increase his prices to widen his margin. So if you think about what people are willing to pay and then the cost of the chips, which one of those two levers do you think is most likely to widen margin in the next couple years?
So there's a number of ways in which cost of supplying inference will go down. One, chips will become more economical in per inference. I do think the algorithms will get much better, which means the software will get better in the amount of compute needed per inference. So there's two vectors. You can make the algorithms 10x more, more efficient over time. I think that will happen. The cost of chips will go down for a given number of inferences. So both those are vectors for cost reduction. The question of pricing on the input side, what customers will pay, will be a function of value. If Amjad, and I love that company and what Amjad is doing, If he keeps adding more and more value, he will be able to charge more. So that's a question of value addition. And that's where there's lots of headroom. You know, when you're taking something that costs, say, a professional, an accounting professional, for example, or, or a design product designer, and you're paying them $100 to $300 an hour and your cost is $1 to $3 an hour, you have lots of pricing room if you can complete— provide more complete solutions. So I do think price per hour of worker time equivalent will increase pretty dramatically also, as will, uh, as will the decline in cost per Vinod Khosla: So, how do you square this model? This business will be healthy starting, let's say, 2030 and beyond when scaled data centers will be in operation.
How do you square that with this matter of enterprise software companies, for example, buyers of enterprise software? I'm talking about businesses in general. They are struggling to find the value right now, at least on an ROI basis for much of this AI software. I mean, the reason I'm asking the question is because talking about raising prices, they're not seeing the value right now. They're very slow to adopt this AI software. So how do you square those two realities right now?
So you have to look at a couple of factors. One, where is value being provided? Great. In software development, it's absolutely great value. So companies like Replit and Cognition, which we are both investors in, Vinod Khosla included, all growing very, very rapidly because they're adding real value. So there are functions in which the product isn't complete or mature. And so you need almost so much handholding, the economics break down. I would say another factor that most people haven't considered, most enterprises who are executing AI are doing it with their people who are not qualified to execute. It's like saying, hey, we have a race car and Joe Blow can go drive it, and he's not going to get most of that race car.
So they need to hire different people.
I think they need to take a very different approach. They take an online IT software person, say, build an agent for me and hope it works great. It's not the way it's working. So generally, If you take a company like Distil, which is in our portfolio, if they execute a project for a large Fortune 500 company, it goes swimmingly well. If in-house people in the same company execute it, it goes very poorly. So, uh, in each of these, even the in-house people will get better over time. So the third or fourth generation of execution will do better because their people will get trained. But they're really not qualified to operate in this area, while the AI-native companies are able to do, get real value. And they're even able to pick the projects that will be valuable and the projects that are more experimental.
I want to pivot to talking a little bit about some of these circular deals that we've seen happening in the AI sector. I mean, NVIDIA, for instance, has been at the center of some of these circular financing arrangements. Do these concern you at all?
Well, they don't. They do and they don't. It's hard to tell what the details are behind each of these debts. If Nvidia is financing customers to buy their chips, that could be perfectly reasonable. The question, so, in many, many industries, look, General Motors finances its cars too, right? When a consumer buys it, it's just a regularized business. The question is hidden in the contracts that are mostly not publicly available. Who's taking on what part of the risk? Is it an enterprise? Are you saying a customer you're financing is viable or not? Are you saying the risk is the customers or their customers if they've done a contract with somebody else to buy X million dollars of inferencing? So where's the risk hidden? Well, and contracts is the key question before one can apply. And frankly, most of those risks and who takes what risk is in the fine print and not visible to almost anybody outside.
I take your point on the fine print. I guess what I'm sort of trying to assess here is the systemic risk in the circular financing at large. And of course, I take your point about, for example, General Motors financing the purchase of a car. But, you know, in a world where you have a chip company financing the— investing in OpenAI, OpenAI buying Cloud compute from Oracle, Oracle buying chips from NVIDIA. I mean, that is a sort of circular loop that I think a lot of people have sort of raised flags about. Does that whole cycle not raise any flags for you or cause any concern?
Well, I would say I don't care. I don't care for the following reason. If NVIDIA is taking a bad credit risk, that's their problem. Right. But if NVIDIA loses $50 or $100 billion, does it kill the company? Probably not. Uh, and I suspect Jensen's pretty smart about what credit risks he's taking with which customer. Is Oracle taking a larger risk? Possibly. It depends on the details of the contract between NVIDIA and Oracle and Oracle and OpenAI or other people buying their, their cloud service. So you have to think of it as traditional business and say, where does the risk lie? If Oracle goes under, for example, because they, they took the risk of $100 billion spend and didn't get that back, then it's their problem. If Oracle disappears from the scene, Do I care? No. Uh, I hope they don't. I think the ecosystem will be healthier, but people are selectively taking risk. Now, Corvi is taking a lot of risk with the money that belongs to certain lenders to Corvi. Do the lenders have risk? I don't know. Does Corvi have risk? And Oracle's doing the same thing. It's taking risk, but I don't know the details of these contracts.
So, But broadly speaking, the level of risk that this has become sort of ubiquitous throughout this AI ecosystem, that doesn't concern you at all?
I would say the fundamental notion of will there be more demand for API inference calls doesn't concern me at all.
Right.
Will there be, the fundamental is how many, how many inferencing calls we'll see in 2030? And 2035. That generally doesn't concern me because I believe AI will add a lot of value. Look, the US economy is $15 trillion of labor alone. Just labor costs in the US economy, $15 trillion. If you could replace $5 trillion of that, there's plenty of room for inferencing to be paid for. If you can do that. Uh, so again, I said the fundamental is, is there demand for AI inferencing the next 5 years, the next 10 years? I'm not worried about that.
Right. Who do you think has—
how clever a contract and who takes on risk if demand is slower or faster to emerge? No, that's for individual companies. If they did a bad deal, they'll go under. If they didn't, great. If everybody does great, which is possible, that AI just grows so fast that nobody has any risk, great. But I'm not responsible for a lender financing a data center. If they fail, their problem, not mine.
Right.
I care about the innovation ecosystem that drives more API calls in AI.
Who do you think has the best chance of challenging NVIDIA?
Well, obviously AMD is trying things, uh, ARM is trying things, Broadcom is trying things. NVIDIA is in an enviable position, uh, because they have so many different things they can do in parallel because the cash flow they have, right? Now, do I know all of Jensen's plans inside and how many different things he's Klein? No. In fact, nobody outside really knows when he's going to announce what. My bet is he has a pretty precise roadmap to 2030 and beyond. So hard to say, but—
So there's no one company that you are really sort of putting your eggs in here in terms of, I think this company is closest on NVIDIA's tail right now.
Well, AMD is doing pretty well by signing, looking at their deals. Broadcom's doing pretty well, but are they going to grab majority share and be larger than NVIDIA? I wouldn't expect that today. Can they take reasonable share, especially at slightly lower margins? Yes. Hmm.
What about all these chip startups that are popping up?
Well, I haven't— I've seen a lot of specialized Chip startups that do one thing. You can run your whole model locally in your shop. Well, that's a market. It's not as large as the data center inferencing market. So there's many sub-markets that the chip startups can do okay in. But I haven't seen the chip startup that could completely blow everybody away. Now, if you have a sudden breakthrough in photonic chips that can do multiply-accumulate inferencing functions, and cut the power consumption by 70% for inferencing. That's entirely possible, even likely, sometime in the next 5 years. And I hope some of those show up because it'll change the power equation, how much power we need for AI. And frankly, most of the data center investment can be repurposed with a new kind of chip that gets slotted in.
Um, I, I want to call it—
it's actually pretty promising. Uh, I suspect digital semiconductor chips are going to be hard to beat NVIDIA at in a massive way. In specialized segments of the market, you can beat them, right? Uh, but generally you'd have to have a radical breakthrough in technology. Photonics is one of them. There's a few others. But I see the most promising candidate for an alternative to NVIDIA becoming from photonics. Yeah, one can scale it, and photonics typically is hard to scale. Now, we were builders of one of our portfolio companies a long time ago. Infineon built the first photonic chips ever. So I think we understand that space a little bit, but we'll see what comes along. Right.
I want to close by talking about the energy side of, of the AI equation. You, of course, have been in energy for a long time. You've made big bets on fusion, among many other technologies. And the question that I want to help get your perspective on is this idea that a lot of these energy bets are going to still take years to scale. Meanwhile, the energy demands that AI will need to sort of satisfy. I mean, those demands are right now. And so, help us reconcile this idea that we need power now and it's going to still take several years for many of these new energy technologies to scale.
So, the simplest way, very, very short term to address electricity demand in the country is pricing. Vinod Khosla: Look, it's— this is why the economics of marketplaces work. Prices will go up some as we consume more pricing for data centers. Data centers themselves can get to be aggressive sources of power management. You can consume at certain times of the day for training runs and other times of the day for inferencing. You can dial up the performance or dial down the performance. So data center input of electricity itself is a variable that'll probably be part of electricity trading. There's some good startups in that area. I think there's a short-term solution, which I think is Superhot Geothermal. I think we can get to gigawatt-scale If you imagine a couple of extra gigawatts of demand emerging every year, some of it will be met through pricing energy appropriately. Some of it will be met through shorter-term projects. Geothermal is one that's much shorter-term than, say, fusion. Fusion's a possibility, but I think fission to me will take the longest. —even compared to fusion. But we'll have an array of factors. We'll have more natural gas turbines coming on. We do have companies where you can start with natural gas and switch to hydrogen whenever the economics warrant it. So, there's a number of ways to adjust, but it is a non-trivial problem.
And so, all these data centers that companies like OpenAI are springing up very quickly, I mean, The simple question I wanted to get your take on is, do we have enough power for these facilities?
Well, first thing to keep in mind, it takes a couple of years to build a data center. You're building a— But many of them are coming up much faster than that, right? There's a few hacks, but fundamentally, if you're trying to add a gigawatt of data center, which is about $30 billion of spend, Uh, it'll take a couple of years. I don't think that's a 6-month or 12-month or even an 18-month project. Uh, then there's demand-based electricity consumption as a tool. And then I think things like geothermal and other technologies will come along. Some of them will be natural gas, uh, fired. Uh, I hope there's no more coal facilities. You know, Main Spring installs capacity for data centers that can switch seamlessly from natural gas to hydrogen when you want to go clean. So, you can decide how much you want to pay for power and what carbon reduction you want and increase the carbon reduction over time. So, that's one solution. All I'm saying is there's an array of tools. Not non-trivial. This will be a serious issue and policy is trying to address it, but I do think there's many solutions.
Last question for you. You know, you wrote this op-ed for us a couple months ago in The Information. It was called, well, it was about the bonkers valuations in AI right now. And one of the things that you mentioned in the piece was that you think that venture capital as an asset class is likely to shrink over the coming 10 years. And I wanted to ask you what the repercussions of that are in your mind. The obvious one that I thought was perhaps startups might actually get better because there's less capital to go around and the better ones would get picked. Is that the main repercussion of this or what are the other repercussions that you see happening?
Let me suggest, you know, I think that op-ed was misinterpreted a little bit. What I said was, uh, AI valuations in general are bonkers. For the best companies, they're not bonkers. And if, as a venture capitalist, you have access to those 2, 3, 4% of the startups, there'll be huge wins. You will do well. You will have great returns. The people who are plying money in, without having special access to these opportunities for whatever reason, will suffer in venture capital as a class. I think broadly, for funds raised in '24 and '25, will have decreasing returns, returns will lower because they're not getting access to good deals early. They're paying higher prices much later. Some of the robotics valuations are getting bonkers. I would venture to guess 95% of those startups will lose money.
So, so the take home here is we need special access to deals essentially to be successful.
It's more than that. I think I like to say most AI startups will lose money. But more money will be made than lost. That means it'll be highly asymmetric. 2-3% of the startups will account for 85-90% of the valuation by 2035 of market cap of companies. So that asymmetry, which has generally been true in venture capital, but we will be significantly more asymmetric in AI. Because of this valuation wave, I think is the reason we will see average returns decline and the best returns for the top firms will do okay, will do well, in fact, because AI is such a large opportunity.
Right. Great. Well, I think that's a good place to end it. Vinod, thank you so much for being here. That is Vinod Khosla here on TITV. We will have you on the show again very soon.
Thank you.
That was Vinod Khosla here on TITB. Okay. TikTok is taking a new ad approach as it gears up for a sale of its US business. In recent weeks, TikTok Shop has been pushing sellers towards a new ad buying tool that promotes videos linking only to TikTok Shop, but lots of merchants are saying that they have had issues with it. I want to bring on our e-commerce reporter, Anne Guillen, to talk about her story on that topic today. Anne, welcome to the show.
It's great to have you back. Hi, Akash. Great to see you.
So let's talk about this, this thing. GMV Max is something that TikTok has rolled out for its TikTok Shop initiative. It's a heck of a name. And so why don't you tell us what GMV Max is and what the idea was here for TikTok when it rolled it out? Sure.
Well, the name is pretty self-evident. The thinking behind the new GMV Max ad tool is to allow TikTok Shops sellers to maximize the GMV or their total sales through TikTok Shop.
The gross merchandise value, volume.
Is that right? Yes. And so the— what this tool does is it takes videos that other creators are already making that are featuring products through TikTok's affiliate program where creators can promote products on TikTok Shop. And get a cut of any sales that result from their video. So this ad tool is basically identifying videos that are already out there on TikTok that are performing well, made by creators that are promoting these products, and then kind of repurposing them as ads. And the pitch to merchants is really that this is an automated, easy way to take content that's already performing well on TikTok and just boost the reach of it as an ad. And so the, the pitch to merchants is really that it's supposed to be kind of this low-lift way for them to maximize their sales on TikTok Shop.
And this was mostly targeted towards smaller merchants that were starting out on the platform.
Yes. Well, TikTok likes to highlight that a lot of the, their shop sellers are small businesses, small sellers that don't necessarily work with an outside ad agency or have in-house marketers. So I think it seems like that is kind of who this tool was geared towards. Uh, but just in talking to merchants, you know, a lot of the biggest sellers on TikTok Shop are big brands. They are companies that are working with outside marketing agencies, and so they've kind of run up against what they feel are like the limitations of this tool, um, just because maximizing sales on TikTok Shop isn't always, you know, the most important goal for a brand that's already a little bit more established.
So, so I, I want to talk about, about the bigger brands here in a second, but broadly speaking, has this helped with, with smaller brands, or I mean, what, what do the, the little guys think of this?
I mean, I think that that from TikTok's perspective, you know, like you mentioned, they're gearing up to spin off their US business. We were also heading into the holiday shopping season, which, you know, is important for every retailer, but especially for TikTok Shop over the past few years, it's really been a make or break time of year for them. So I think the— I think it seems like the reasoning behind pushing this tool now is especially just going into a time when a lot of people on TikTok are primed to be buying things, to have more videos in, in the feed that are kind of explicitly tied to TikTok Shop products.
And I guess for the bigger brands that are— that have access to advertising agencies like you mentioned, and you pointed this out in the story, I guess part of the idea here is they actually have budget to create their own ads. They don't really need to make need of all the smaller creators that are pointing to their products that they, I mean, they want control over, over how their product is actually displayed.
Right. I spoke to one brand in particular who they've had a lot of success with TikTok's affiliate program in the past. They've worked with a really wide range of creators and basically allowed pretty much anyone, regardless of the size of their following, to promote their product. And they saw a lot of success from creators that didn't have a big following or hadn't really ever gone viral before going viral with their product. And so that was a lot of the appeal of TikTok's platform originally for them. But this brand says that since the introduction of GMB Max, the pool of creators that are able to really have videos that break out and reach a lot of people, that pool of creators has been greatly reduced. And so I think for this brand, it feels like, you know, their thinking was the original appeal of TikTok was access to this really large pool of creators and, you know, all different kinds of people who could promote their product. And now they feel like that reach has been pretty limited.
And they've actually seen their revenue decline in some cases.
Yes, they have. And so it's interesting because this brand, they, they saw a lot of success on TikTok in the past and they're actually considering moving some of their budget that they were spending on TikTok, either on ads or on sending products to creators to promote, they're potentially moving— they're potentially weighing moving some of that budget to other creator platforms like ShopMy.
If you sort of compare this to other platforms and how they approach the creator-brand-platform alliance and relationship, it's, it's kind of a— it's a complicated triangle to navigate. You know, if you compare what TikTok is doing to other platforms and then you sort of zoom out a bit and think about what this says about brands' strategy themselves, how do you sort of think about those two things?
It's interesting because creators and influencers have become such a powerful marketing tool that every brand wants to leverage in some way. And I think the introduction of some of these new automated advertising tools sometimes feels like it's kind of at odds with, you know, how brands want to market themselves. And so, I mean, you've seen Google and Meta roll out automated advertising tools. Mark Zuckerberg told Meta investors earlier this year that he envisions a world very soon where you as an advertiser can come to Meta basically with your credit card and a budget and describe to them, you know, what you want to get out of an ad campaign, and they can spin up and run and manage an ad campaign for you all using AI. So I think it will be really interesting to watch going forward how brands and marketers kind of balance that need for control and wanting to be disciplined in their spending and be creative in their marketing with these tech platforms wanting to grow their ad business and kind of make it easier than ever to sell more ads. Okay.
Well, Anne, it's a fascinating story. Thank you so much for coming on and explaining to us. That is Anne Guillén, our e-commerce reporter here at The Information. Okay. Continuing with our e-commerce coverage, the retail landscape is shifting with the growing adoption of AI. Recently, OpenAI announced that you can now shop through the platform with merchants like Etsy, Shopify, and Walmart. My next guest wrote an opinion piece for The Information out today about where AI can really transform the shopping experience. You can read that on our website. Joining me now is Lee Haslett-Chen, founder and CEO of Howl. Lee, welcome to the— welcome to TITV.
It's great to have you. Hey, Akash, it is great to be here.
So I'm excited to talk about this piece that you wrote. What made you want to write it in the first place?
I've spent the last 10 years as a founder in the technology and commerce space, and this is a really fantastic time to be in this industry. So AI has the promise to make things easier for shoppers, and I think the movement, the momentum, the sense of change is really tangible. So as you said at the very beginning, there has been a bevy of really significant announcements by OpenAI in commerce over the past few weeks. And I see a huge push from other AI companies and startups to use AI to change how consumers find products. Hmm. I felt very personally inspired to sit down and actually play with these tools. Right. And my tech nerd self was like, great, there's some interesting features and buying is more convenient. But my consumer self actually was like, wait, I don't feel satisfied.
So, so let's, let's get into it. I mean, one of the great parts about your, your piece here was basically what shopping could look like down the road. And so the question I wanted to ask you is, what do you imagine shopping looking like 5 years down the road now that we have these AI-inspired tools coming about?
Yeah, I think the biggest opportunity is Returns. Okay. So I'm actually staring at a returns pile right now. Okay. And it makes me feel kind of bad about myself. Why? Because I think as a consumer, we're told that returning products is our fault, right? There's almost like a moral deficiency because we have to return something. Right.
And then you gotta go through the whole process too. You gotta find the code, you gotta print out the slip in some cases, figure out which which depot to drop it off at.
It's terrible. And then I looked it up. The National Retail Federation reported that there's $890 billion of returns in 2024. Okay. That is a huge headache for a lot of people, but it also speaks to me that returns are a feature of today's commerce ecosystem. It's not a bug. Let's not pretend like returns are the actual problem. The issue is that nothing is making it easier for shoppers. And I think AI can solve this.
And, and this, this, I, I was interested in this because this sort of connects to another discussion we've been having on the show, which is that some of the lowest hanging fruit in terms of tasks, uh, stuff, you know, I'm thinking about the boring tasks in our life, like companies dealing with documents or even writing drafts. Yes. I mean that it's the boring stuff really that AI is going to take over. And really offer significant ROI for in, in the early cases. It's not the, the most complicated things like AI will find an entire outfit for me or something like that.
We are impressed by AI, significantly impressed, but now please solve some of our boring problems. Right. Um, and I think like normalizing returns, it's a win for consumers. And what's not discussed is that it's a win for businesses as well. Right. So like. Every return starts with the desire to buy something. Now you have a chance to fix that. You can come back with a better recommendation, like actually create a repeat business and repeat purchase model that drives loyalty. The economy will benefit from that.
Now you, you talked also about recommendations in, in your piece, which I thought was interesting. We've heard a little bit more about that, but I kind of want to get a little bit into what you were doing at your company, Howl. What exactly is Howl as a business right now and how are you using AI yourself?
Yeah, great question. So Howl is a creator commerce platform. We are the market leader in consumer tech, in gaming and sporting goods. So through partnerships with folks like Sony and Samsung, Nintendo, Walmart, we've driven over $1 billion in retail sales. Okay. When I look at brands, creators, social, AI, we're actually already in the same ecosystem. And that's because to power commerce, AI companies need product reviews. They need information. They need recommendations and not just from anyone, from experts. So we like to say that, you know, creators are the PhDs of commerce. They make viral content. They make the types of reviews that already sell billions of dollars of products. So if you're building out AI today and commerce, you must have a creator strategy.
Let me ask you this. We just had a segment, we just had our e-commerce reporter, Anne, on the show talking about a new effort that TikTok had been rolling out with TikTok Shop to help smaller brands, um, you know, find traction for their products on the platform. Um, you know, as it relates to helping some of these brands use AI to make more money, Do you see an opportunity there, or how, how do you see that playing out? Absolutely.
I think there are a lot of slept-on companies as we think about AI and commerce. So there are big plays right now, right? Like the browser wars that launched yesterday, let's say with Atlas and OpenAI, Perplexity's Comet. But there are also companies that are enabling marketers, brands, and designers to be more successful using AI. So these are not companies you actually know.
Who, who, who are we sleeping on? Tell us, tell us the name of some of these companies.
Yeah, it's Canva, right? It's Figma. It's Shopify. These are the companies that are giving AI tools, storytelling tools, product design tools, technology tools to the actual marketers and brands making these products, as well as to creators who are making this content. So I think of it as if there's infrastructure and there's research and there's consumer, there's a whole B2B ecosystem that also supports that. And this is that ecosystem of companies who drive innovation.
Well, Lee, it was a great op-ed. Again, uh, to remind people, you can read that on our website right now. I appreciate you coming on to chat with us about it. That is Lee Haslitschen, the founder of Howl and author of a new opinion piece at theinformation.com, live right now. Okay, earlier this month, online education company Campus bought Sizzle AI. It's a deal that will see Sizzle AI founder Jerome Pacenti join Campus as CTO. I want to bring on Campus founder Tade Oyorinde and Jerome to talk about what they've got cooking. Tade and Jerome, welcome to the show. It's great to have you.
Let's go. Thanks for having us. Yeah.
So look, Tade, I want to start with you. What does Campus do? Let's talk about that and we'll talk about the partnership in a second.
Yeah, look, we bought a 2-year college a few years ago and we're rebuilding college for the AI era from the ground up. I think that if you look at the country today, a lot of young people with $2 trillion of student loan debt. They don't think that there's any great life that they can build in America. They don't think they can afford to get a great job and then sort of buy a home, live in a great neighborhood. None of that feels like it's on the table. And a big part of it is the student loan debt. So we wanted to buy a new college, to buy a college and sort of redesign the model from the ground up. And so Campus Today is a 2-year college where all the classes are taught live online. We're not teaching sort of theoretical nonsense. It's all sort of practical skills that'll make you employable. And the classes are taught by a distributed network of professors from top 50 universities. Think UCLA, think Princeton, think NYU. And then after 2 years, students get to transfer into the 4-year university of their dreams with basically having paid nothing for the first 2 years because of what's called the Pell Grant. So our tuition is less than the Pell Grant, so students pay nothing out of pocket 86% of the time.
So Jerome, there's, there's a lot going on here. What was the vision for the partnership here between Sizzle AI and you coming on board and then how that plugs into campus?
Well, I've been in technology all my career, you know, but today, you know, we have some pretty fundamental problems in society, right? Housing is unaffordable, healthcare is unaffordable, higher education is unaffordable. So I want to use technology to make a difference in people's lives, right? I want to tackle some of these fundamental problems with campus, with the opportunity to really tackle one of these problems, which is making you know, elite higher education available to everybody. And that's what we're planning to do with AI and with the best teaching professors.
Tadej, when you think about this question here, will AI replace teachers? What do you think is the answer to that 10 years from now? I mean, you know, we've had folks— actually, Vinod Khosla was on the show just before you guys earlier in the segment, and he has talked about the idea that AI can empower people with their own personalized tutors in the long run. I mean, that is one way of looking at it. The other way of looking at it is, hey, AI can just teach you everything entirely. Where do you think education sits 10 years from now with AI?
Yeah, Jerome just said it. Teachers aren't going away. Professors aren't going away. Actually, on the contrary, they're going to become a lot more important. I think the professors and the teachers, they're going to inspire students. It's all about relationships. Students actually need to get excited about motivated, to actually be successful in these courses. Um, the thing that AI is really good at, and Jerome's tech and the team he's built is actually number one in the world at, is the intersection between AI and actually understanding learning. So the tech basically assesses every student and then creates a real definition of what they understand, what they don't understand, down to the atomic units of understanding, and then creates a personalized pathway through the curriculum until they get to success. So it's not every student that's starting every class at the exact same starting point., and our tech now actually deeply understands what specific deficiencies students have and then helps them plug it and achieve mastery. No one else is doing this.
So, so, so basically every student is, I mean, they come to you, they say, hey, these are my goals, this is what I want to learn. And every student gets sort of a different course load. Every class is, is different and depends on what they learned the day before.
Within the context of each individual class, you're taking Calculus 1, for example. Do you understand all of the building blocks that you needed from algebra to even start really understanding the basics of calculus? And if you don't, right now, in every other college in the country, every student still goes through the exact same exercises, the exact same lessons, the exact same homework assignments. That makes no sense. In reality, what you want is to customize based on a student's starting point in Calculus 1, a personalized pathway through the curriculum to get them to actually succeed, that deeply understands what they know and what they don't. It's kind of like what my mother did for me and my siblings when we were homeschooled. Got it. Got it.
So, so, Jerome, I guess what I'm hearing is it's less about sort of, you know, what a chatbot can do and it's more about how we can actually deliver a customized course load. That's where you see the potential.
I mean, the goal is twofold, right? One is to make the education more personalized. So before the class, during the class, after the class, how do we offer to each student something that's going to put them back to level? You know, how do we adapt the exercise and the practice to them? The second is, how do we assist, you know, the teaching professors and TA so that they're more effective? They focus on the things that matter, for example, spending time with a student, answering their question, coaching them, reacting to them, and less on things that can be automated, like grading or creating exercises. So our goal is really to make the one-on-one interaction with the staff a lot more effective and personalized.
Tata, you guys have been around for a while. You also have venture backing. Where is the company at right now in terms of revenue and profitability?
Yeah, look, I think it's obviously a big mission. I think a lot of people who care about this country have gotten involved. Sam Altman led our seed round, Trey and Peter at Founders Fund led our A, and Ken Chenault and Niraj from General Catalyst led our B. We've raised over $100 million. We're growing really quickly. We don't break out revenue and report that, but you could probably sort of back into it. You look at our tuition, it's about $10,000 a year, and we have about 3,000 active students.
So you could do the math, I'm sure. And I should say that along with being the head of the company, chancellor is your official title, which I'm sure is perhaps a title that everyone wants at some point in their life if they want to get into education.
Look, I'm a big Star Wars guy, so maybe that's some reason why we did this whole thing.
There you go. Well, Tadej Andzurov, thank you for coming on the show. I appreciate it. Uh, we'll have to have you back on again. That is Tadej and Jerome from Kampus here on TITV. And with that, that does it for today's show. A reminder that we are on this stream Monday through Friday at 10 AM Pacific, 1 PM Eastern. I want to thank Amazon Web Services, who is our presenting sponsor for this production, and I want to thank you for tuning in. We really do appreciate your viewership. I am already excited for our next show tomorrow. Have a great rest of your Wednesday. Bye-bye for now.
More from Vinod

EXCLUSIVE: Vinod Khosla warns AI will upend jobs and healthcare sooner than expected | GSIF 2026

Vinod Khosla: AI Tutors, Doctors & Farmer Experts For 1.5B Indians | AI Summit 2026

India AI Impact Summit: Vinod Khosla on Why 2047 Could Free Every Indian from Survival Work

‘There Will Be A Lot Fewer Jobs In 20 Years…’: Billionaire Entrepreneur Vinod Khosla On Impact Of AI