Debt Validation Fund II - Quick Overview Video - DVFII | Titan Impact Group
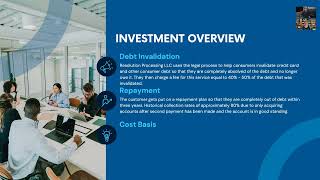
Debt Validation Fund II is a $50M fund that buys consumer debt at 25% of face value, primarily from first responders and their families. Investors receive 20% annual returns (25% for $1M+) over 36 months, with the fund targeting 80% collection rates on roughly $6,000 average receivables purchased for $1,500 each.
Questions this video answers
$50,000
$50 million
36 months (estimated)
20% annualized, paid quarterly
25% annualized for investments of $1,000,000 or more
Chapters
Foreign. And welcome to the quick overview of the OCG Debt Validation Fund brought to you by OCG and Titan with myself and Catherine Bell to be able to bring this absolutely awesome investment to you to show you what we're doing here with regard to accounts receivable debt and helping people get out of debt while at the same time making a great return on our capital and, and mitigating risk through the proper collateral associated with our debt. So let's talk about this really quick so you guys can get a general understanding of what this looks like. We do have a deeper dive video if you want to go take a look at that as well. Once you kind of get your feet wet with this quick video. So the first thing to understand here is some of the key points is we are lending capital secured by accounts receivable contracts at an estimated 25% of the value of that receivable. So it's pools of these giant receivables or these micro receivables with pools of them all together which mitigate our risk because we're looking at collection ratios of around 80% to mitigate our risk across the board. So if we're lending at 25% of the value and their historical collection ratio is 80%, we're able to significantly have good collateral there to protect ourselves in case there's any downside risk of the market. It's an estimated 36 month term on the investment and interest only payments. The the investment is $50,000. So is the minimum investment. You can go up to as much as you want. This is a $50 million fund. So we have the capabilities of growing significantly with this. There's a 20% annualized return that's paid out on a quarterly basis starting in quarter one for up to three years for this promissory note. So on $100,000 investment, you're looking at a $20,000 a year, which is $5,000 per quarter, which is an amazing interest rate on your funds. And what's great is if you put in a million dollars or more, you actually make 25% on your money as well, which is a really cool strategy to incentivize larger capital investors because that it's less work for us, we can actually implement that and it's much more efficient on all aspects for us. So we actually, what's really cool is we're providing a social benefit. And I want Catherine to explain this in a little bit more depth because this is her wheelhouse and it's the most amazing thing in the world to be able to do this for people.
So for those of you who know, have been following you know, forever, is that, you know, everything that we do must leave every person, property and community better than we found them. And that is exactly what this does. And the other piece that I love, love, love about it is it allows us to be the bank and allows our investors to be the bank. If you understand investing being the you, out of all the positions you can be in any investing transaction, being the bank is the most secure because the bank always wins. That's exactly what this is. But here's the impact inside of you. I want you to understand what this is, is that all of these receivables that are here are all coming from first responders and their families. So what does that mean? We know that first responders, you know, do not get paid absolutely what they're worth. They give everything. They truly are the heroes of this country for sure. And inside of that, you know, financial literacy is the unfair advantage. So because of the lack of financial literacy, a lot of these families got themselves into positions with this credit card debt, you know, no fault of their own. And by being able to come in and literally work with these families and invalidate this debt and bring it down significantly so that they literally can breathe. Because we know that money is like oxygen. The more you have, the easier it is to breathe. The more you have these you can breathe, the bigger the difference in the world you can make. So we're literally giving these families oxygen by helping invalidate this debt. There is a portion that they still have to pay, but now it's actually in a manageable bite sized piece. That's the first piece. The second piece is that we actually bring in financial literacy for these families. So we teach them how money works, how to tell money where to go and then how to invest. Because we know that the average millionaire has seven streams of passive income. And so by teaching these families how to create these passive streams of income, think about this. Now they have the breathing room because their finances are taken care of, which allows them to continue to pouring their hearts into being of service in the way that they are as first responders. Because we know that that's where their heart is. That's why they are first responders. They don't go to be first responders to be financially free. They do it because that's where their heart is. And so this is a beautiful way for, for our investors to be a part of saying thank you, thank you for the heart that you Give thank you for all that you pour into our, our communities are, you know, all these things that you do and this is your way to do good while doing well. So just know that that is, there's a major ripple effect impact that is being made on all of these families. And you know, Matt, I'd love for you to share about, you know, that.
The, the, the, the military vet that we just helped, that he was actually able to invalidate about $70,000 worth of credit card debt, which is absolutely amazing.
And, you know, breathing room, right?
Yes, absolutely. It puts him on a path of actually success versus just, you know, struggling consistently to be able to actually get by. And, you know, we really try to focus on discount programs for military, for active, for active duty and vets as well as, you know, police and firefighters and getting those discount programs. The actual debt and validation services are available to others as well, of course. But at the same time, we are focused on those discount programs and those programs for those military and vets and, you know, police and firefighters and the shields that they hold for us to try to, you know, help the community. So really, really cool strategy to help people. And so what is debt invalidation? What's actually occurring is we work with a company called Resolution Processing, where they have attorneys that help people completely invalidate their debt because the creditors are not abiding by the Fair Credit Practices act and many other legal requirements to help consumers and protect consumers from unscrupulous creditors. So they use multiple ways to help them completely absolve and get them out of debt, where that debt is wiped off of their books and they do not owe it anymore. And they typically charge a fee of 40 to 50% but with no interest that's paid off in 24 months and they're out of debt. You know, in that situation, in that timeframe, which is really, really cool, you're taking someone that has, you know, 20, 30, $40,000 worth of credit card debt, $1,500 minimums and, and 30% interest, and cutting that debt by 60%. And then you're going through and saying, now we're going to have a small monthly payment with no interest. It's fully paid off, and you're out of debt in 24 months and all that other debt is wiped off your books in that, in that situation and wiped off that. Off the map, which is really, really cool social benefit to give people. The consumers get on this payment plan and get out of the debt within 24 to 36 months. And there's this historic Collection ratios on this debt is around 80%, which is really what protects us because we're buying pools of this debt at 25% of what it's worth. And so if we have an 80% collection ratio, that's 30% of our collectible value associated with the actual asset. So if we're looking at an average receivable of around thousand dollars, it costs us in marketing fees and finding those clients and setting them up about 1500 dollars in investable capital to bring that to light. So and looking at this from a mapping standpoint, you have affiliates that are going out and finding these contracts and finding the clients that need this service, that need debt and validation and they find them for resolution partners, what sets them up and helps them find the right attorneys and sets up all the legal, sir, the, not the legal services, but the administrative services to you this whole entire process up. And then the client signs up with that contract receivable and does legal fee legal fees with the attorneys where $250 of their payment goes towards the resolution aspect of this, the administrative services, the setup, all the back end work and overhead and then another $100 goes towards the actual legal services that are being obtained on a monthly basis by them. And then we come in and as investors and we retain that $250 payment for putting up the fifteen hundred dollar investments and our funds are secured against those pools of accounts receivable with a UCC filing to protect our interest in that asset. And so if you break this down on what's actually happening here, the affiliate marketing company goes out and finds Those consumers with 20, 20K in credit card debt. Then the affiliate marketing company signs them up after two payments, they're able to get that fifteen hundred dollars. There's a clawback if they, they don't actually make two payments on these debt and there's proper quality control that's put in place before they're ever even signed up for that contract. And then they enter the contract with the, with resolution processing and the attorneys to be able to absolve that debt and then they're able to slowly invalidate their debt and completely get them out of debt with an average receivable balance of about $6,000 instead of, and a cost to us of about $1,500. Then the monthly payments start out and they average over 24 months about $250 a month with that 80% collection ratio. So the attorneys are also doing the actual debt and validation services over the 24 month period of time. And the consumers are in, the debt is invalidated and they no longer owe that within the 24 or 12 to 24 month period of time. So if you do the math, which is the thing CPAs love of course, is we do $5 million of investment at a fifteen hundred dollar cost, that's 3,333 contracts. So a giant pool of these contracts at $250 payments each, that's $833,000 a month of actual payments on a $5 million investment, which is a significant payment on the amount of capital that's actually invested. So on $5 million it actually creates $20 million with the receivables, that's $16 million collectible, which is really, really cool to see and from a risk mitigation standpoint. And that is your quick overview of this. If you're interested in working with us, we have a portal with our website. Through our website you can contact Catherine or you can contact myself or one of our investment partners that we work with to be able to understand this investment more, ask questions, get the legal docs and if you're comfortable enough, after your due diligence moving forward with us. So thanks so much. I really appreciate it and it's always amazing to work with Catherine in this way and be able to bring this to you guys, these different investments.
Yes, thank you. Thank you everyone. This is extraordinary.










