How I Manage My Business Finances as a 6 Figure Entrepreneur
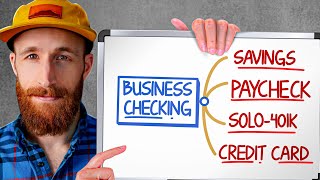
Greg Faxon (creator) explains a personal system for managing small-business finances to reduce stress and make income predictable. He recommends separating accounts (business checking, business savings for tax and profit, personal checking for owner's pay, a solo 401(k), and a business credit card), allocating baseline revenue (example baseline $18,000/month) into tax (15% → $2,700), profit (5% → $900), owner's pay, and OPEX (~30 → $5,400), and implementing a zero-sum budget in YNAB to give every dollar a job with automatic transfers and category targets. The video includes concrete YNAB setup steps, examples, and practical caveats (not legal/tax advice; consult a CPA/bookkeeper).
Questions this video answers
$18,000 (USD) per month.
15% of revenue; $2,700 on an $18,000 baseline.
5% of revenue; $900 on an $18,000 baseline.
About 30% of revenue; approximately $5,400 on an $18,000 baseline.
Capital One (online account).
Chapters
In this video, I'm going to share with you how I manage my business finances. I'm not a cpa, I'm not a bookkeeper, but I've run my online business for over 10 years. And during that time, I've created a little system for myself to manage, to budget money and to pay myself. That really works well. It takes a lot of the stress out of running a business. And so in this video, I want to share with you why you need a money management system. And whether it looks like mine or it looks totally different, it's important to have one. What my money system looks like, how I manage the budget, using a software called ynab, and some other things to keep in mind. So let's dive in. Number one is why you need a money management system, and it makes your income consistent even though your revenue will be inconsistent. As an entrepreneur, you're not going to, you know, make the same amount of money every single month in your business. But that doesn't mean you can't pay yourself a set paycheck each month, which takes a lot of the stress out of being an entrepreneur. Having a money management system gives you a monthly revenue goal to aim for, instead of you just aiming for more. You can actually know. Here is the minimum I need to hit each month to be good, and anything above that is a bonus that I can reinvest back. It allows you to save and invest automatically without relying on willpower. A money system separates your business and your personal finances, which is really important come tax time and organizing your books. But it's also important for you to just see your business as something outside of you, as an asset. And finally, it tells you what you can afford to spend on contractors, employees, training, etc. Based on your revenue. If you've ever wanted to invest in a course or hire someone, but you couldn't really know if you can afford it, having a money system can give you the answer to that before you go and make a mistake and investing in something too soon. All right, so number two is what my money management system looks like. And here's what it looks like and we'll simplify it real quick for now. Which is the first account you need is a business checking account. We don't want to be running your business income and revenue through your personal account because that's really hard to figure out. What was a personal expense versus a business expense and how much did the business actually make? So the first account you set up is a business checking account. I use an account from Capital One online. And you know, there's plenty of good accounts out there. I'm not an affiliate for Capital One, but 100% of your revenue goes into this account. And we're going to use an example of if you made 18k, $18,000 on average, US per month. This is important because depending on your average revenue, you're going to set up some automatic savings and transfers and stuff. So let's assume that last year in your business, you made an average of 18k per month, and that's what you want to use as your baseline revenue to establish your budget. So money is going to come in From Stripe, from PayPal, it's going to get deposited automatically into this checking account. Then we have four accounts. So the next one is your business savings account. It's nice to have something with a slightly higher interest rate, but also just to separate some money and put it aside for later use. And so the two types of money that go into business savings are tax and profit. These are using profit first target allocation percentages. And you can go look that up or read the book Profit first. But here's what it looks like. Okay, so depending on your revenue range, you're going to set up a different percentage for each of these different accounts in profit first, they're completely separate accounts. My system's a little bit simpler. You want to figure out what your revenue range is. If we use 18k per month as an example, that puts you in that first 0 to 250k target allocation percentage. So you'd set aside 15% of any revenue that came in for tax time. Okay. For your quarterly estimates, et cetera. So if we do 15% of 18,000, it's 2,700. So automatically we're going to transfer money from our checking to our savings on the same day each month of this amount. The next is profit. Okay, so we want to put aside some money. This isn't just money you pay yourself kind of as an employee of the business. It's you setting aside the excess profit leftover. This is also important for creating a little bit of an emergency fund for yourself in case you have a low month. You can go pull out of savings out of this profit to cover it. So 5% or $900 of 18,000. Again, that's just an example of average revenue we're going to set aside into the savings account. It's going to get automatically transferred. Now, occasionally we're going to actually bring money back from savings to checking. I'm going to show you what this all looks like in my budget in a second. But I want to give you a full map of it. So quarterly taxes, emergencies when you just don't hit that 18k revenue amount and you need to cover yourself or profit draws. So every quarter, for example, you could take 50% of the profit in this account and you could go pay yourself extra as the owner of the business. Next is personal checking. This is an account you should already have set up. And this is where you actually deposit your paycheck from the business. So owner's pay should be about 37% in profit first. It's 50% at the revenue range we're talking about. But you also have some that we're going to put in a 401k. So this is what you use for your personal expenses, right? Your personal checking. And it's interesting, what most people don't realize is that only a percentage of their revenue is actually going to become their paycheck, right? Because there's expenses, there's tax, you're putting aside profit. And if you're investing, part of that is going to be put into investments. And so you might have to make 18k a month just to get paid, you know, $9,000. If you combine these two categories, only about 6k is getting deposited into your checking account and part of is your paycheck. So for example, I have an S Corp, and so this is just, I get paid as an employee of the business. And then you can also deposit some money into your checking each month as a profit draw as the owner of the business. This is stuff you should, you know, if you don't understand it, you should bring it up with a CPA so they can understand how much should you actually be paying yourself as an employee versus how much can you reasonably take as an owner of the business? The next account is some sort of business 401k. So if you've ever worked for an employer, you probably had a 401k plan. You can set up the same thing as a business owner. What's nice about that is that it has much higher limits. You can deposit about a lot more there than just in a Roth ira, for example. And so I have a solo or individual 401k it's sometimes called. And you can make employee contributions and employer contributions. So again, these are just using sample numbers based on, you know, my work with my CPA and using this as an example of 18,000amonth. And you can see these limits. You know, this is in the US this is just for 2024, but this is how much money you could actually put into a solo 401k if you are an S corp like me. Okay, so that's the third account. The fourth account is credit card. Okay. Having a separate business credit card. This is where I put all of my expenses. Okay. OPEX is operational expenses at this 18k per month range, about 30% of that as a rough guideline or 5400 is what we'd want to target for monthly business expenses, Things that you could spe on the business itself. So those are the four accounts. When you have these buckets, it allows you to put money so in different places where it's not just one big number. You look at and you assume that you have money that you can spend on something when actually that money should be in your 401k or actually that money is your paycheck as the owner. Actually, that money is tax that's gonna be due next quarter that you need to keep in that account. Okay, so that's what my money system looks like. If you feel a little overwhelmed, that's okay. You can always go back and watch the video again. But I'm gonna clarify it here for you by breaking it down into step. Actually using a software to do what I just described. I use a software called you need a budget or ynab. My wife and I use this for our personal finances, and you can also use it to budget for a small business. So the first step is to create a budget in ynab. And I'm going to share with you what zero sum budgeting means, which is instead of service, you might have used like mint or something where you're simply setting yourself a goal of how much you want to spend on something and then hoping you don't pass the goal. In ynab, we give every dollar a job. So every dollar that comes in as revenue for our business, we're going to budget pro into a category, and then we're going to spend that down. It's almost like if you ever heard of the envelope strategy where you put money into an envelope. This is very old school for different categories. And then you spend from that envelope. You have an envelope on dining out. And once that envelope doesn't have any money in it, you can't dine out anymore. So that's what YNAB allows you to do with technology. And the first step is to start a budget. I believe YNAB has a free trial and you can create a new budget for yourself. So this is just a blank budget. It'll come out with some default categories, but we're going to delete all of these because we're going to create our own categories. A lot of these are personal type categories. So we've created a new budget. Then we want to add our checking account and our credit card, business checking account and credit card. We're not going to add our business savings account, and I'll tell you why in a second. But let's add those accounts. You can do a linked account, which would automatically pull the transactions. That's what I recommend. Or you can create an unlinked account where you manually input the transactions, which is a pain in the butt. I'm going to use it now just because I don't have the login information, obviously for your business checking account. But if you did it as a linked account, it would walk you through logging in. This is going to be a checking account. And then let's say that the current balance. Current balance is 20k. All right? So we're going to see that account there. And if you have it linked, it's automatically going to pull every future transaction, every expense, every charge. And when you have money coming in, it'll change this number as well. Then you'll also want to link your credit card again. I'm going to use it unlinked, but you should link it with your actual credit card company. And that type is a credit card. And let's say that I had a $200 balance on it and I wanted to pay it off all at once. So you' see your checking account and then it'll subtract the amount that you have as your balance on your credit card, and that will become your full budget, the amount that you have to work with. I don't add my savings account because it makes it easier for me to see the spending breakdown and actually see profit and tax as a percentage of my spending. If it's in ynab, it won't come up as spending, and you can't really see the percentage as easily. So now we want to create our categories. And I wanted to shout out Nick True, who has another YouTube channel who kind of gave me the inspiration for my system. Mine is slightly different, but he uses YNAB and Profit first, which are the two main tools that we're using here. So there's going to be four main categories, and it's going to be based on what we have right here. The first category is going to be profit. Okay. And you can move stuff around here. Then we're going to do tax Then we're going to do owners pay. And then finally we're going to have operational expenses. And if you want, you can kind of put little emojis. I got this idea from Nick as well, just to make it easier for you to see stuff at a glance. Obviously that's totally optional. Okay, so here are taxes. We got profit tax, owner's pay, and operational expenses. Your owner's pay is going to include three main categories. And this is assuming that you're investing in some sort of individual 401k. So we can add subcategories here. So, for example, an owner's pay, I can say my paycheck, Profit Draw and 401K. And you can reorder stuff. I recommend ordering things by the larger expenses or the larger amounts first. And in OpEx, we want to add all of those as well. So you're going to add every request recurring payment that you have. For example, if you use, you know, leadpages, you'd put it in here. And you can set how much to budget for. Let's say you need $10 or probably more like $49 for lead pages, and it goes through on the 24th of each month. And we'd save that target and it would have us budget for that out of ready to assign, which we'll do in a second. So we want to add in all our payments, all our expenses, and then we want to order them for highest to lowest because it's easier when we figure out what we want to cut. Create some extra money. We'll just have expensive stuff at the top and the least expensive stuff at the bottom. We want to put in all our due dates for recurring payments and we want to budget ahead for annual payments. So, for example, let's say I have, you know, my bookkeeping software, and that's an annual payment. So I'll create a target. It won't be monthly, it'll be yearly. Let's say it's December 13th, I need $1,000. Then it's going to have me set aside $250 so that by the time we get there, I have the money ready in the account. So the next thing we want to do is create goals for each category based on your profit first, percentages and your baseline revenue. I prefer using set numbers each month versus calculating percentages monthly, which is what Nick did in his video that I referred to, which I'll link to. And the reason is if I say, all right, I'm budgeting for this $18,000 per month revenue baseline, I Can say, well, I want profit to be 5% of that, and that equals, you know, $900 a month. Because then what I'm going to do later is I'm going to actually go into my checking account and I'm going to create an automatic transfer each month to just send $900 to the profit savings account. We want to choose this number, right? I had the example of 18,000amonth. We want to use it conservatively based on our history. So you could look at the last 12 months. What's the average revenue you made? I wouldn't probably go above that as your baseline because we want to ensure that we're going to be able to bring in this revenue most months because we're setting up automatic transfers and we're basing our expense budget on that. So the next thing is we're going to set up those automatic transfers from our business checking account to our other account. Right. You can see that up here where we're setting up, depending on what we set for revenue, we're setting up these different transfers that go through. And then we want to categorize the expenses and allocate money and ready to assign. I'm going to cut to an actual budget here so you can see what this looks like when it's finished. Okay. I have profit and then profit, savings, tax, tax, savings, all these different categories of owners pay, which adds up to 9020 all these opex categories. So a video editor, payroll tax. And what you'll see is that Ynab pulls the transactions and you can go ahead and categorize them. Every transaction here is categorized for a specific category and it pulls from that category. And then each month you can do, you can take this amount that you've made and ready to assign. And you can assign it to what you haven't funded yet. Right. So underfunded is around 3,000 these categories here. So I can just click on that. It pulls from ready to assign. And then I can go to the next month. Underfunded, I can do that as well and fund all of those categories. Right. So then they'll all turn up green. And if I have a little bit left over, I can put it in the other category. Okay. So some things to keep in mind, this isn't financial, legal or tax advice. You should work with a CPA or a lawyer. I still use a bookkeeper. Even though this is my budget that I manage to stay on top of things, it's still helpful to use an official bookkeeper for, you know, tax records and to send to your cpa. Don't get too crazy with budgeting until you actually have money to manage. Just focus on getting clients and invest in your business so that it can grow. If you're only making, you know, $3,000 a month, this type of budget might be overkill. All you got to do is get more clients and make more money at that point, even if it means going outside the percentages to invest in something to help you get more clients and automate as much as you can, but keep your tabs on your cash flow. Actually come into the budget and be allocating money and moving it around. Okay, hope this video is helpful. If it was, leave a comment below. Subscribe and we'll see you in the next one.